
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
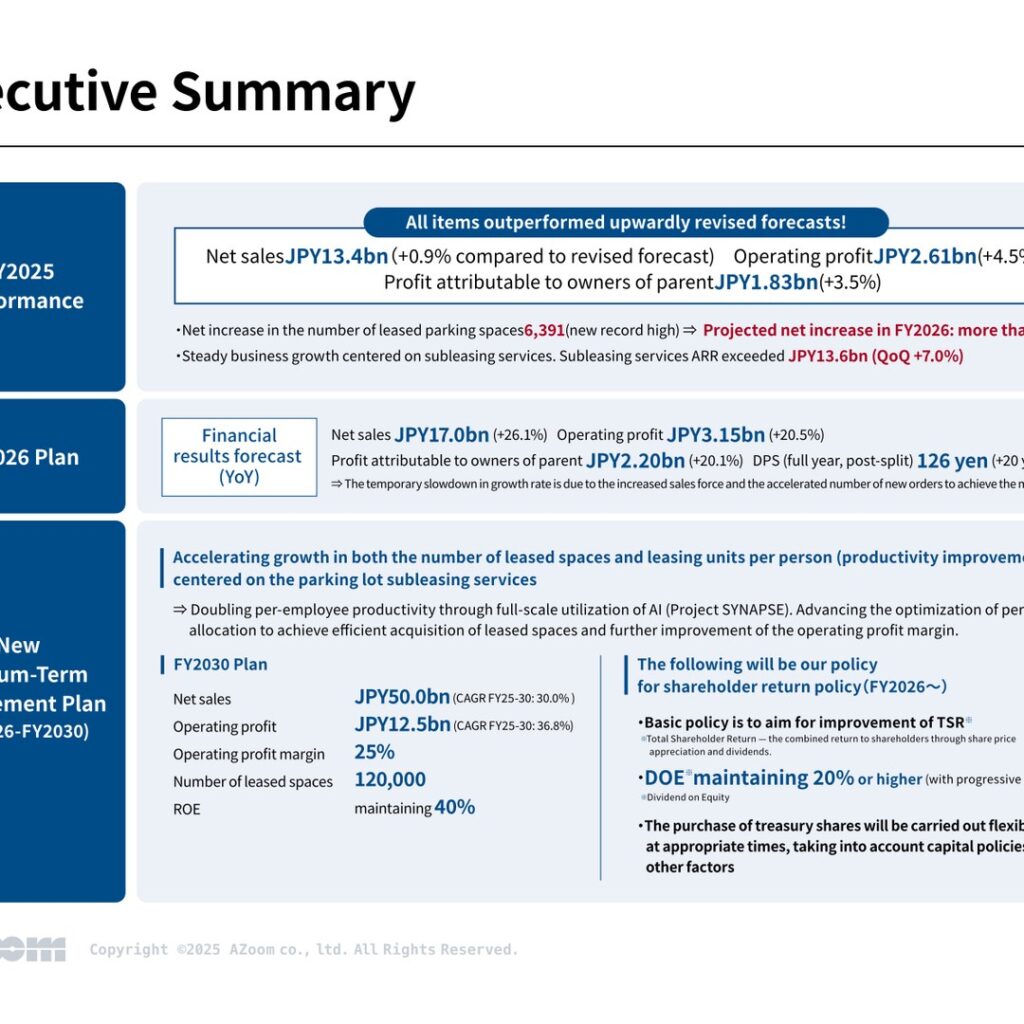
AZoom Co., Ltd. (TSE Prime: 3496) closed the fiscal year ended September 30, 2025 (FY2025) with every line item above its upwardly revised forecasts: net sales of JPY13.4bn (+0.9% versus the revised forecast), operating profit of JPY2.61bn (+4.5%) and profit attributable to owners of parent of JPY1.83bn (+3.5%). Growth was centered on the parking lot subleasing services, where the net increase in leased parking spaces reached a record 6,391 and subleasing services ARR exceeded JPY13.6bn (QoQ +7.0%). The company also launched a new Medium-Term Management Plan (FY2026-FY2030) targeting net sales of JPY50.0bn and operating profit of JPY12.5bn in FY2030.
Consolidated Results (Full-Year Actual)
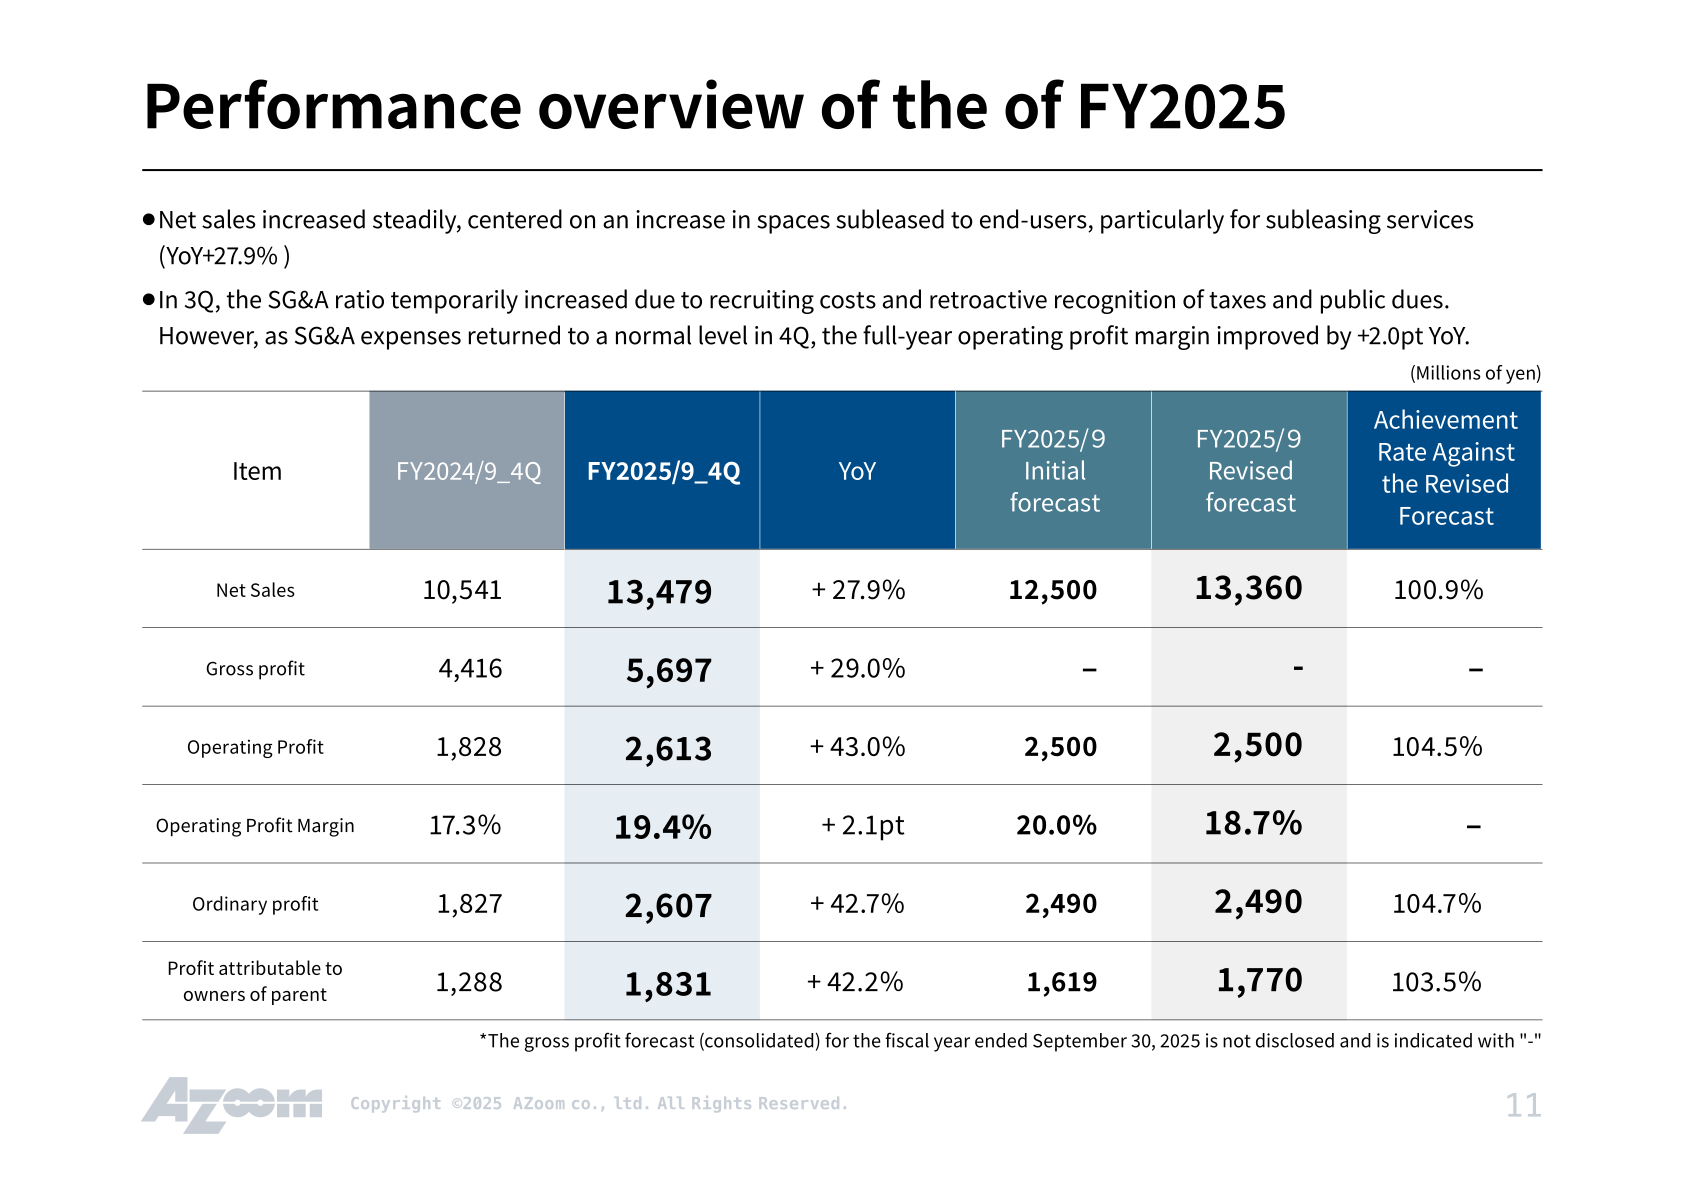
Net sales rose 27.9% YoY to 13,479 million yen, driven by an increase in spaces subleased to end-users, particularly in subleasing services. Operating profit grew 43.0% to 2,613 million yen, and the operating profit margin improved to 19.4% (+2.1pt YoY). According to the company, the SG&A ratio temporarily increased in 3Q due to recruiting costs and the retroactive recognition of taxes and public dues, but SG&A expenses returned to a normal level in 4Q. Profit attributable to owners of parent increased 42.2% to 1,831 million yen, achieving 103.5% of the revised forecast.
| Item (Millions of yen) | FY2024/9 | FY2025/9 | YoY | FY2025/9 Revised Forecast | Achievement vs. Revised Forecast |
|---|---|---|---|---|---|
| Net sales | 10,541 | 13,479 | +27.9% | 13,360 | 100.9% |
| Gross profit | 4,416 | 5,697 | +29.0% | – | – |
| Operating profit | 1,828 | 2,613 | +43.0% | 2,500 | 104.5% |
| Operating profit margin | 17.3% | 19.4% | +2.1pt | 18.7% | – |
| Ordinary profit | 1,827 | 2,607 | +42.7% | 2,490 | 104.7% |
| Profit attributable to owners of parent | 1,288 | 1,831 | +42.2% | 1,770 | 103.5% |
In the parking lot subleasing services, the number of leased spaces reached 35,381 at the end of FY2025, with a net increase of 1,925 in 4Q. The number of spaces subleased to end-users was 32,883 (QoQ +1,755), and the occupancy rate remained high at 92.9% (QoQ △0.1pt). As a result of the capital increase, the company became subject to size-based business taxation, while the effective tax burden rate declined (YoY △1.1pt).
Segment Results
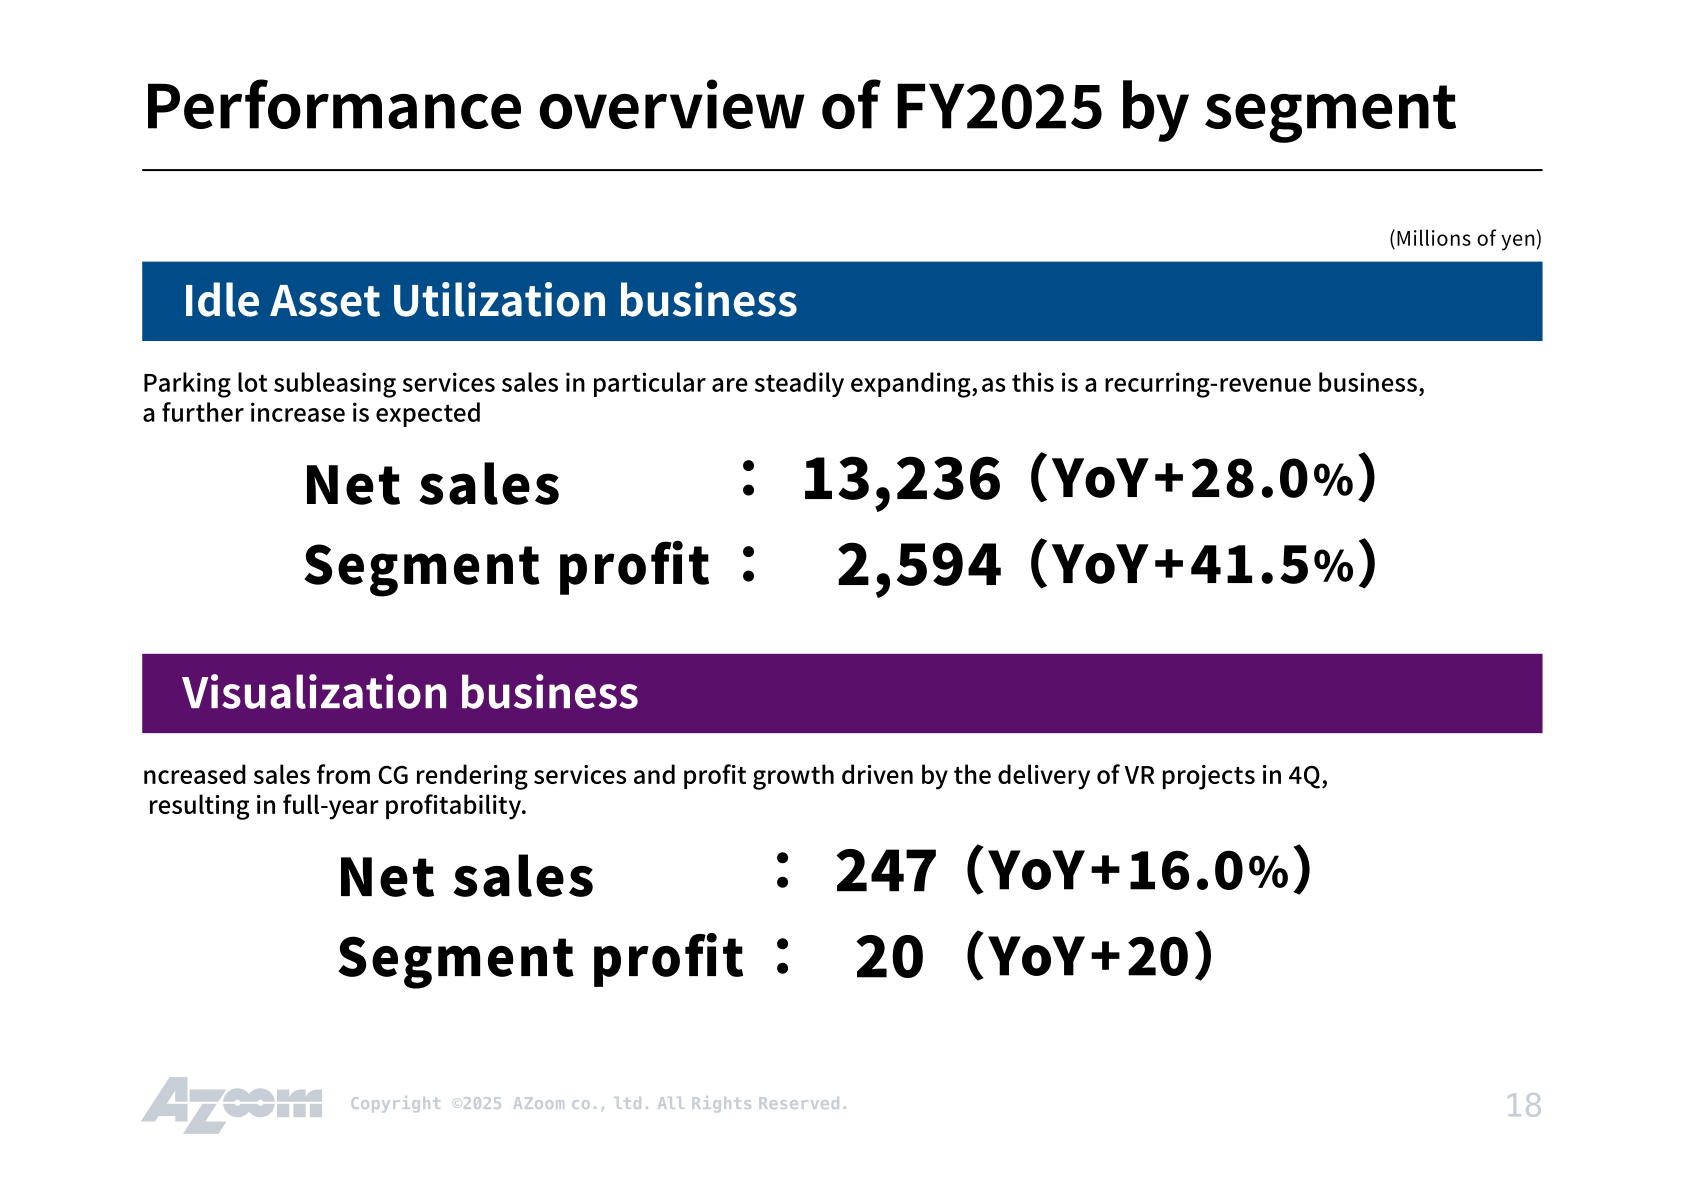
The Idle Asset Utilization business, which includes parking lot subleasing, the parking lot introduction service and other services, generated net sales of 13,236 million yen (YoY +28.0%) and segment profit of 2,594 million yen (YoY +41.5%). The company notes that the expansion of recurring-revenue sales centered on subleasing services is becoming even more clear, and multiple orders for contracted system development projects for Smart Space Reservation contributed to other service-related sales. The Visualization business posted net sales of 247 million yen (YoY +16.0%) and segment profit of 20 million yen (YoY +20 million yen), turning profitable for the full year on higher CG rendering sales (CG perspective-related sales YoY +9.6%) and the delivery of multiple VR projects in 4Q.
| Segment | Metric | FY2025/9 (Millions of yen) | YoY |
|---|---|---|---|
| Idle Asset Utilization business | Net sales | 13,236 | +28.0% |
| Idle Asset Utilization business | Segment profit | 2,594 | +41.5% |
| Visualization business | Net sales | 247 | +16.0% |
| Visualization business | Segment profit | 20 | +20 |
FY2026 Forecast
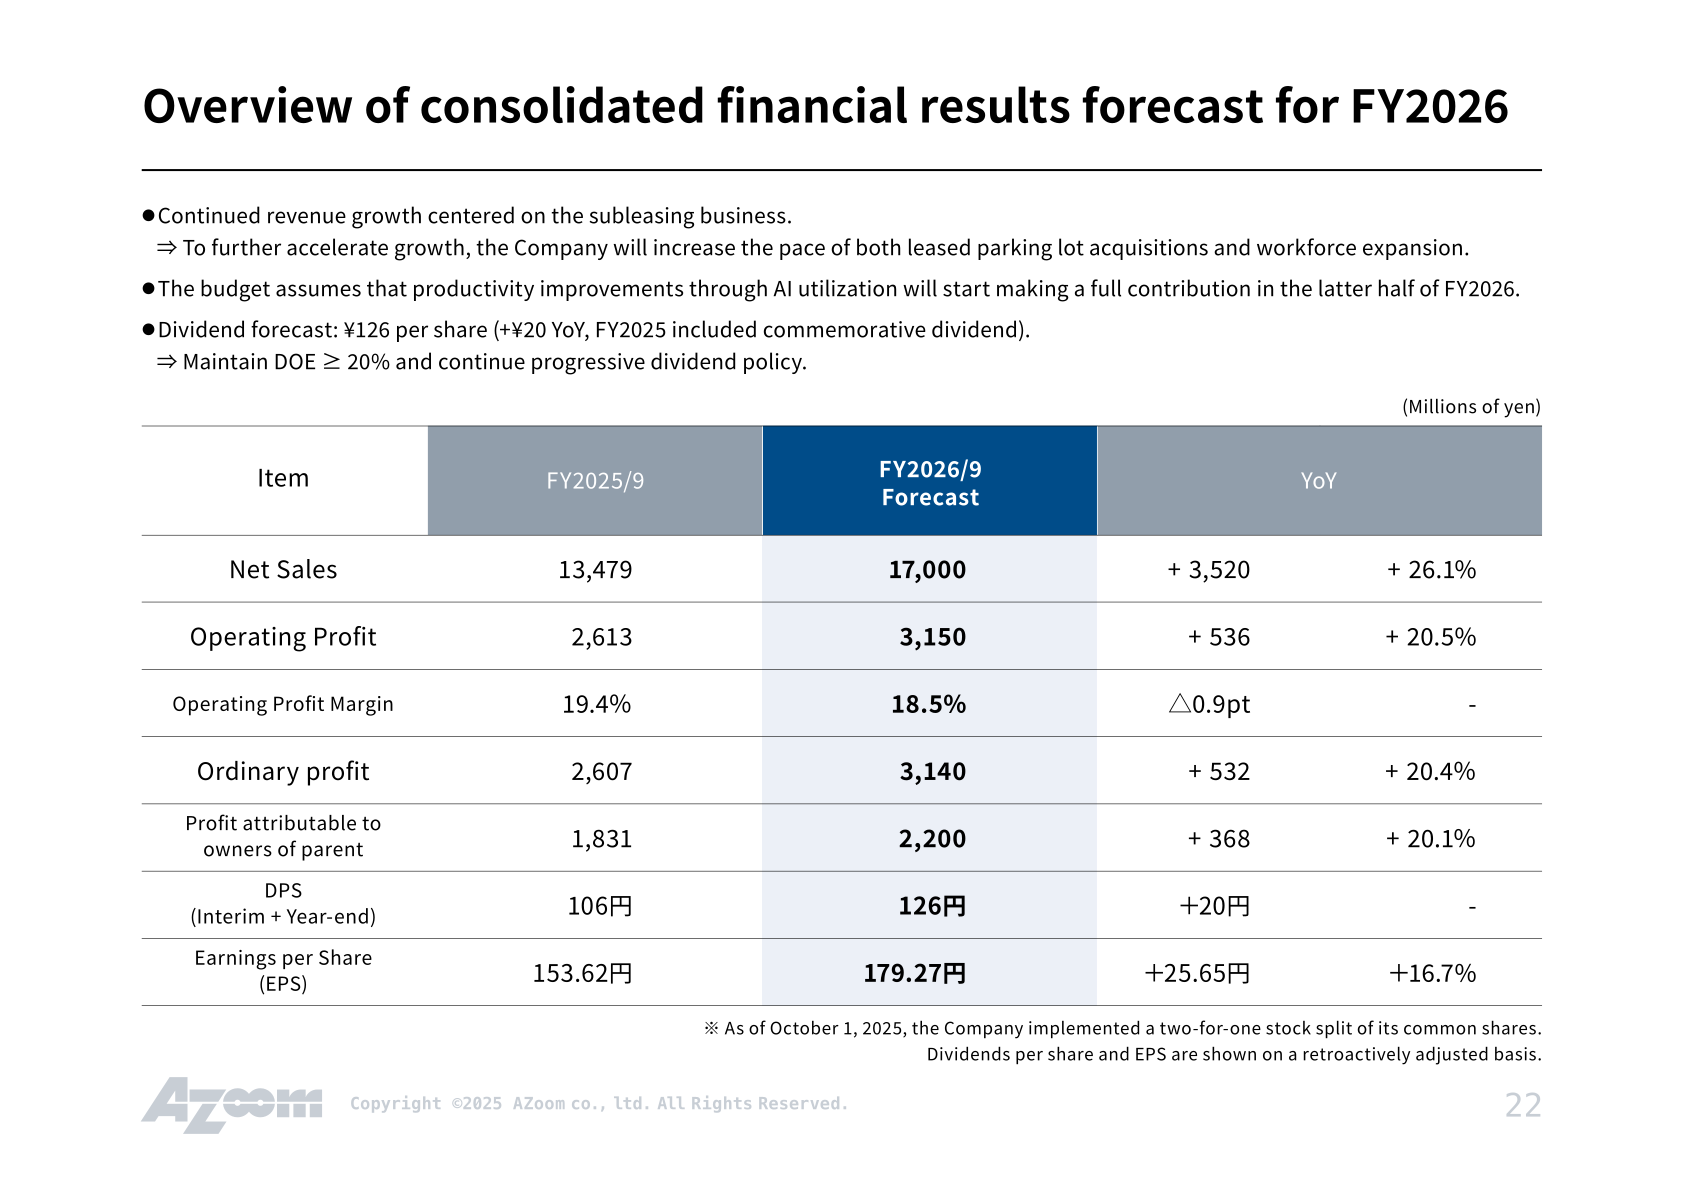
For the fiscal year ending September 30, 2026, AZoom forecasts net sales of 17,000 million yen (+26.1%), operating profit of 3,150 million yen (+20.5%) and profit attributable to owners of parent of 2,200 million yen (+20.1%). The operating profit margin is expected to be 18.5% (△0.9pt). The company explains that the temporary slowdown in the growth rate reflects an increased sales force and an accelerated number of new orders to achieve the medium-term plan, and it projects a net increase of more than 8,000 leased parking spaces in FY2026. The budget assumes that productivity improvements through AI utilization (Project SYNAPSE) will start making a full contribution in the latter half of FY2026.
| Item (Millions of yen) | FY2026/9 Forecast | FY2025/9 (Actual) | YoY |
|---|---|---|---|
| Net sales | 17,000 | 13,479 | +3,520 / +26.1% |
| Operating profit | 3,150 | 2,613 | +536 / +20.5% |
| Operating profit margin | 18.5% | 19.4% | △0.9pt |
| Ordinary profit | 3,140 | 2,607 | +532 / +20.4% |
| Profit attributable to owners of parent | 2,200 | 1,831 | +368 / +20.1% |
| EPS (post-split basis) | 179.27 yen | 153.62 yen | +25.65 yen / +16.7% |
Shareholder Returns
From FY2026, the company’s basic policy is to aim for improvement of TSR (Total Shareholder Return) through long-term share price appreciation driven by EPS growth, while maintaining a DOE (Dividend on Equity) level of 20% or higher under a progressive dividend policy. The purchase of treasury shares will be carried out flexibly at appropriate times, taking into account capital policies and other factors. The annual dividend for FY2025 was 106 yen (FY2025 included a commemorative dividend), and the company plans to raise it by 20 yen to 126 yen per share in FY2026, including an interim dividend of 63 yen. A two-for-one stock split was implemented on October 1, 2025, and dividends per share are shown on a retroactively adjusted basis.
| Item | FY2025/9 (Actual) | FY2026/9 (Forecast) |
|---|---|---|
| Annual DPS (post-split basis) | 106 yen | 126 yen (interim 63 yen) |
| DOE | 19.0% | 22.2% |
New Medium-Term Management Plan (FY2026-FY2030)
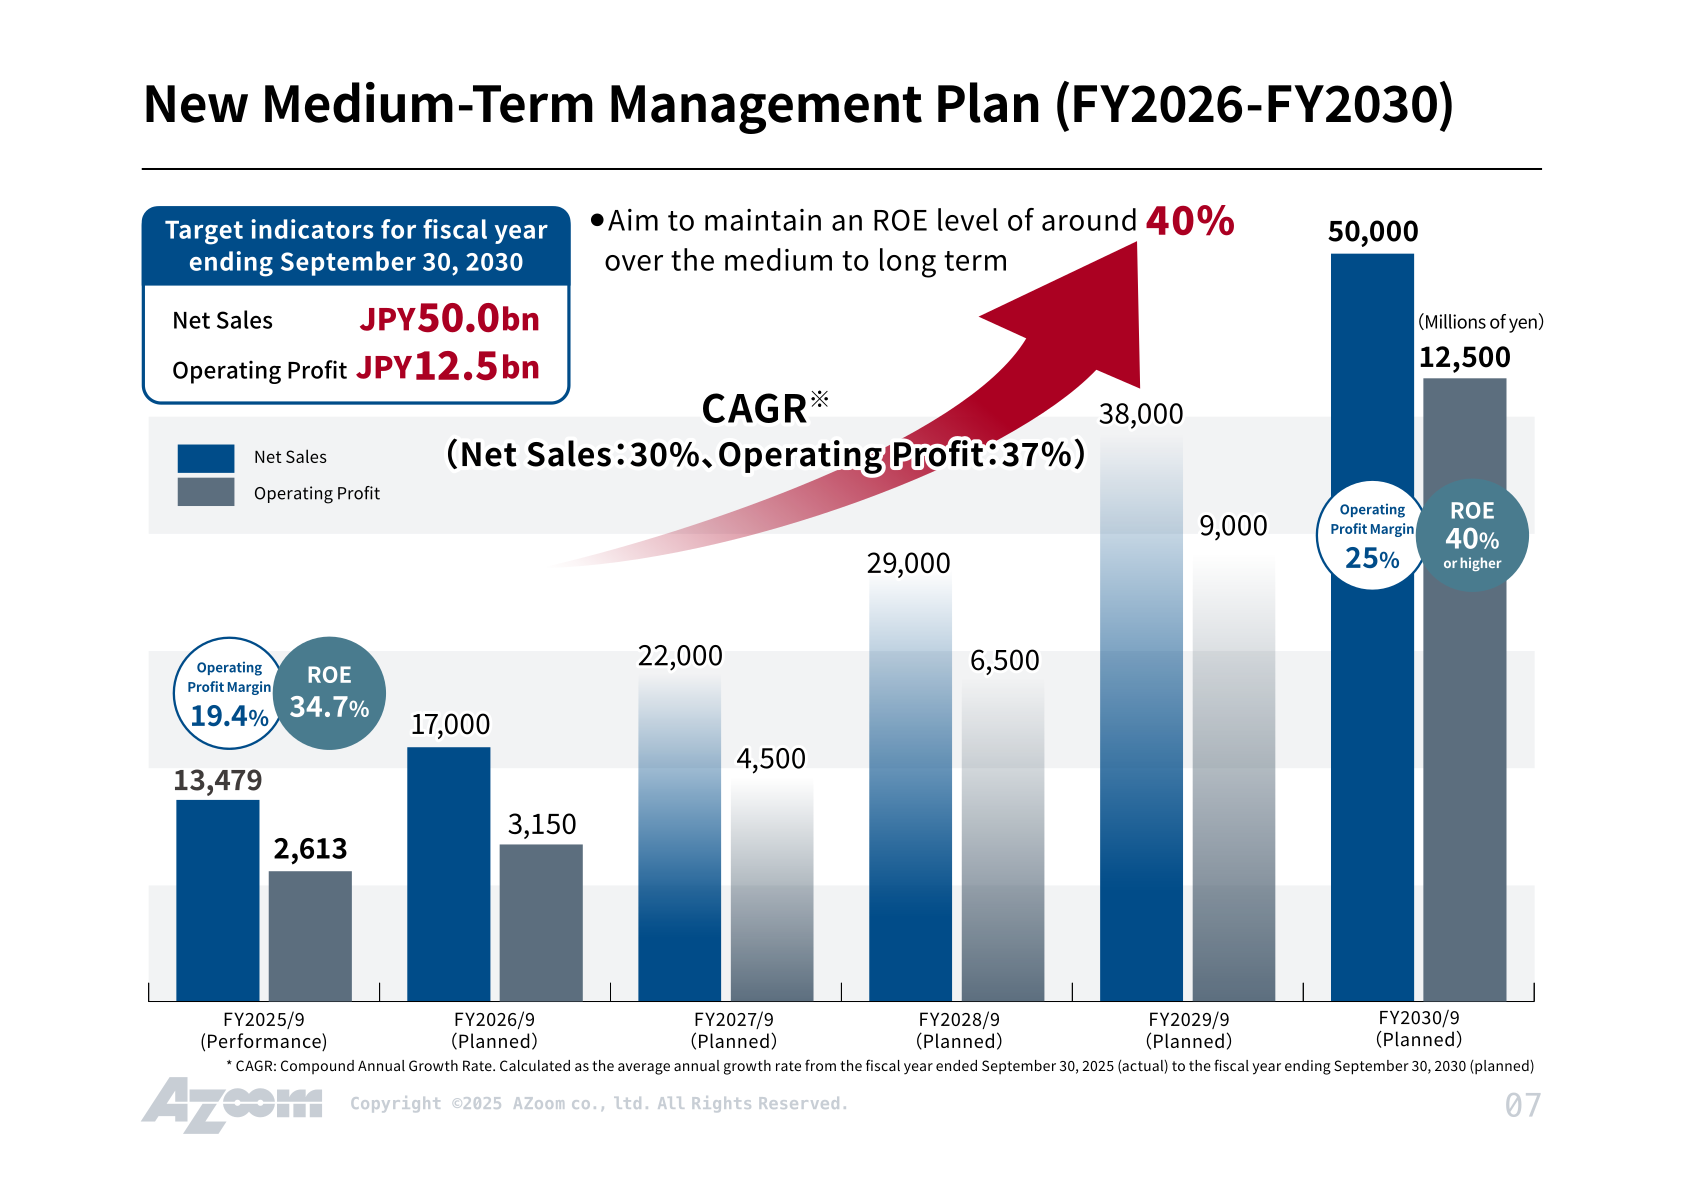
Under the new Medium-Term Management Plan, AZoom aims to accelerate growth in both the number of leased spaces and leasing units per person, centered on the parking lot subleasing services, with the goal of doubling per-employee productivity through full-scale utilization of AI (Project SYNAPSE). The targets for the fiscal year ending September 30, 2030 are net sales of JPY50.0bn (CAGR FY25-30: 30.0%), operating profit of JPY12.5bn (CAGR FY25-30: 36.8%), an operating profit margin of 25%, 120,000 leased spaces, and maintaining ROE of 40%. In FY2025, the operating profit margin was 19.4% and ROE was 34.7%. Under the previous plan (FY2022-FY2025), net sales and operating profit exceeded the plan in all fiscal years.
| Fiscal year (Millions of yen) | Net sales | Operating profit |
|---|---|---|
| FY2025/9 (Performance) | 13,479 | 2,613 |
| FY2026/9 (Planned) | 17,000 | 3,150 |
| FY2027/9 (Planned) | 22,000 | 4,500 |
| FY2028/9 (Planned) | 29,000 | 6,500 |
| FY2029/9 (Planned) | 38,000 | 9,000 |
| FY2030/9 (Planned) | 50,000 | 12,500 |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















