
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: On this site the most recently completed fiscal year is labeled FY2025. create restaurants holdings inc. has a February fiscal year-end, and its materials label the fiscal year ended February 2026 as “FY 2026” and the fiscal year ending February 2027 as “FY 2027”; the body and tables below keep the company’s labels.
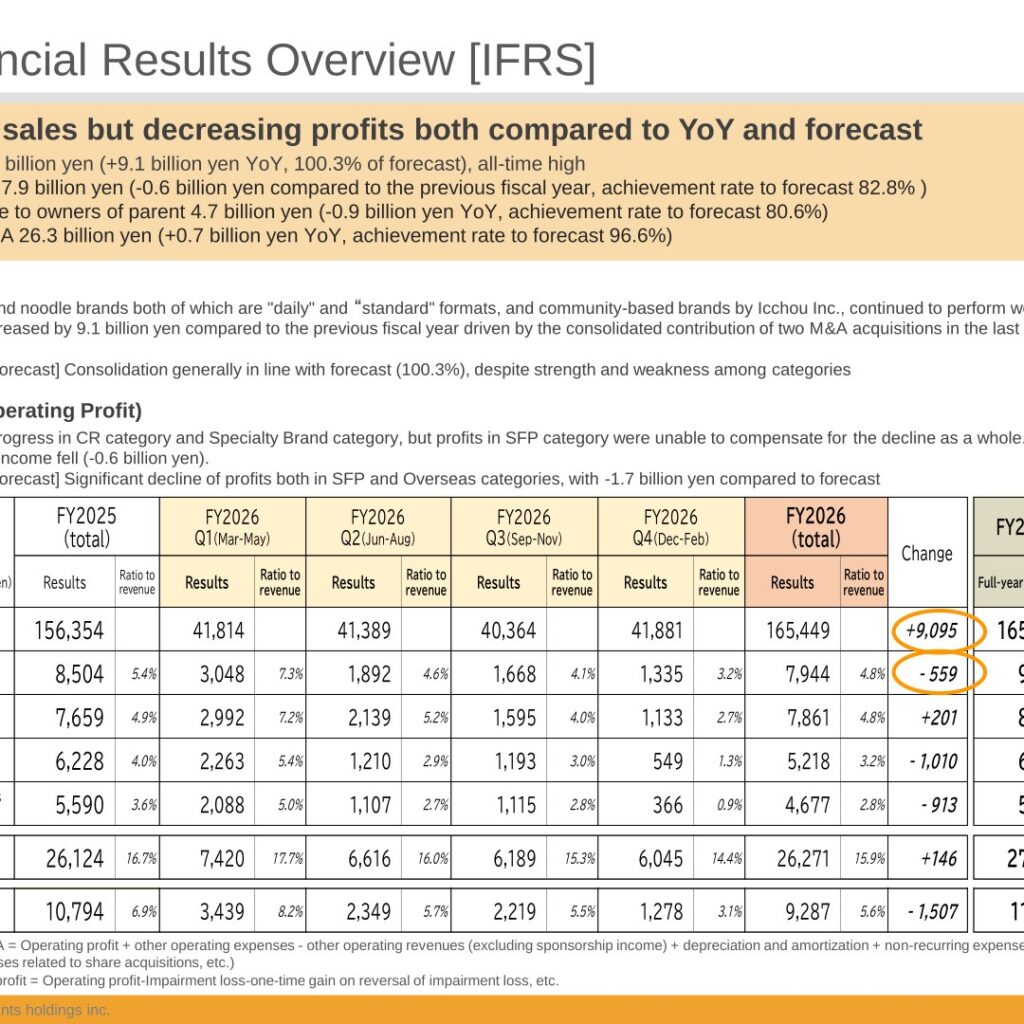
create restaurants holdings inc. (TSE Prime, 3387) reported IFRS results for FY 2026 with revenue of 165,449 million yen (+9,095 million yen YoY), an all-time high, and 100.3% of its full-year forecast. Operating profit fell to 7,944 million yen (-559 million yen YoY; 82.8% of forecast) and profit attributable to owners of parent was 4,677 million yen (-913 million yen YoY; 80.6% of forecast). The company summarized the year as “increasing sales but decreasing profits both compared to YoY and forecast”, with steady progress in the CR and Specialty Brand categories unable to offset lower profit in the SFP category. For FY 2027 it forecasts record highs for both revenue and operating profit, and it announced an absorption merger with its listed subsidiary SFP Holdings effective July 1, 2026.
Consolidated Results (Full-Year Actual)
Revenue growth was driven by bakery and noodle brands (both “daily” and “standard” formats) and community-based brands at Icchou Inc., together with the consolidated contribution of two M&A acquisitions made in the second half of the previous fiscal year. Against forecast, operating profit was 1.7 billion yen short, reflecting a significant decline in profits in both the SFP and Overseas categories. Adjusted EBITDA was 26,271 million yen (15.9% of revenue) and actual operating profit (operating profit excluding impairment loss and one-time gains on reversal of impairment loss, etc.) was 9,287 million yen.
| Item (million yen) | FY2026 | FY2025 | Change | FY2026 Forecast | Achievement rate |
|---|---|---|---|---|---|
| Revenue | 165,449 | 156,354 | +9,095 | 165,000 | 100.3% |
| Operating profit | 7,944 | 8,504 | -559 | 9,600 | 82.8% |
| Profit before taxes | 7,861 | 7,659 | +201 | 8,800 | 89.3% |
| Profit for the period | 5,218 | 6,228 | -1,010 | 6,500 | 80.3% |
| Profit attributable to owners of parent | 4,677 | 5,590 | -913 | 5,800 | 80.6% |
| Adjusted EBITDA | 26,271 | 26,124 | +146 | 27,200 | 96.6% |
| Actual operating profit | 9,287 | 10,794 | -1,507 | 11,600 | 80.1% |
On a quarterly basis, operating profit was 3,048 million yen in Q1 (Mar-May), 1,892 million yen in Q2 (Jun-Aug), 1,668 million yen in Q3 (Sep-Nov) and 1,335 million yen in Q4 (Dec-Feb). Consolidated same-store sales for the full year were 101.8% YoY.
At fiscal year-end, total assets were 139,669 million yen (+2,501 million yen), reflecting equipment for new stores and the start of consolidation of two M&A companies, while bonds and borrowings declined to 21,045 million yen (-5,171 million yen) on loan repayments. The equity ratio (equity attributable to owners of parent ratio) improved to 31.3% from 29.3%, and the adjusted equity ratio excluding the impact of IFRS No. 16 rose to 46.2% from 42.9%. ROE was 11.1% and adjusted ROIC was 24.3%, with the ROIC spread widening to 15.8% as pre-tax WACC declined to 8.5%. Operating cash flow was 23,002 million yen.
Segment Results (by Category)
The company manages its business in four categories and evaluates them by revenue and Category CF (operating profit under JGAAP plus depreciation and amortization, sponsorship income and non-recurring expense items). The CR category maintained strong sales, mainly at stores in urban commercial facilities, and beat its targets for both sales and CF. The SFP category fell short of target on fewer customers at existing ISOMARU SUISAN stores and a higher cost of sales ratio, leaving CF significantly below forecast. The Specialty Brand category exceeded forecast as bakery and noodle brands and Icchou Inc. continued to perform well. The Overseas category missed forecast as Il Fornaio struggled with inflationary fatigue in North America, worsening in Q4, which the strong performance of Wildflower could not make up for.
| Category | Revenue FY2026 | Revenue FY2025 | Category CF FY2026 | Category CF FY2025 | CF ratio to revenue FY2026 |
|---|---|---|---|---|---|
| CR | 58,466 | 53,973 | 6,035 | 5,850 | 10.3% |
| SFP | 31,119 | 30,256 | 2,454 | 3,026 | 7.9% |
| Specialty Brand | 50,214 | 48,908 | 5,641 | 5,458 | 11.2% |
| Overseas | 26,039 | 23,262 | 2,380 | 2,212 | 9.1% |
| Adjustments, etc. | -390 | -45 | 9,759 | 9,577 | – |
| Total | 165,449 | 156,354 | 26,271 | 26,124 | 15.9% |
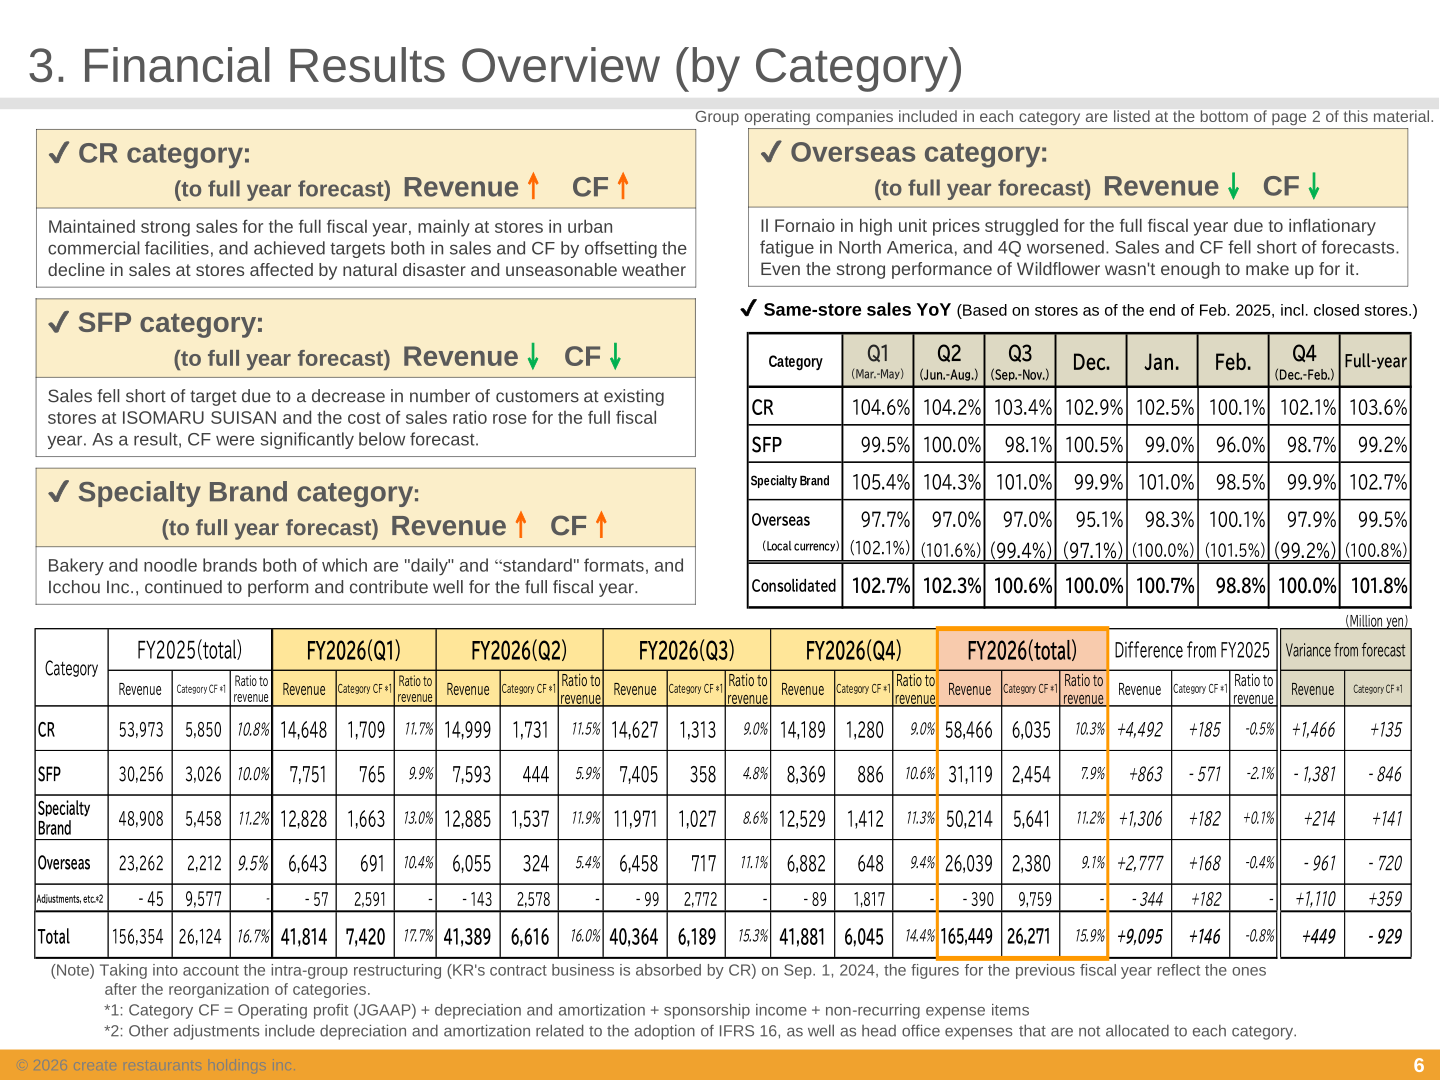
Same-store sales for the full year were 103.6% YoY in CR, 99.2% in SFP, 102.7% in Specialty Brand and 99.5% in Overseas (100.8% in local currency). The group had 1,125 stores at the end of February 2026, after 56 new store openings, 54 closures and 7 stores added through M&A during the year.
FY 2027 Forecast
For FY 2027 the company forecasts higher sales and profits YoY, with record highs for both revenue and operating profit. Key assumptions are existing-store sales of 103.0% YoY through efforts to increase customer numbers and continued price optimization, 34 planned new store openings, a cost of sales ratio unchanged from the previous year, and a continued 5.0% increase in the employee salary increase fund (for 3 consecutive years). The forecast reflects full-year contributions from two group-in companies (Tecona Bagel and RON) and the impact of group reorganization.
| Item (million yen) | FY2027 Forecast | FY2026 Result | Change | Pct. change |
|---|---|---|---|---|
| Revenue | 171,000 | 165,449 | +5,550 | 103.4% |
| Operating profit | 9,000 | 7,944 | +1,055 | 113.3% |
| Profit before taxes | 8,000 | 7,861 | +138 | 101.8% |
| Profit for the year | 6,000 | 5,218 | +781 | 115.0% |
| Profit attributable to owners of parent | 5,700 | 4,677 | +1,022 | 121.9% |
| Adjusted EBITDA | 27,100 | 26,271 | +828 | 103.2% |
| Actual operating profit | 11,000 | 9,287 | +1,712 | 118.4% |
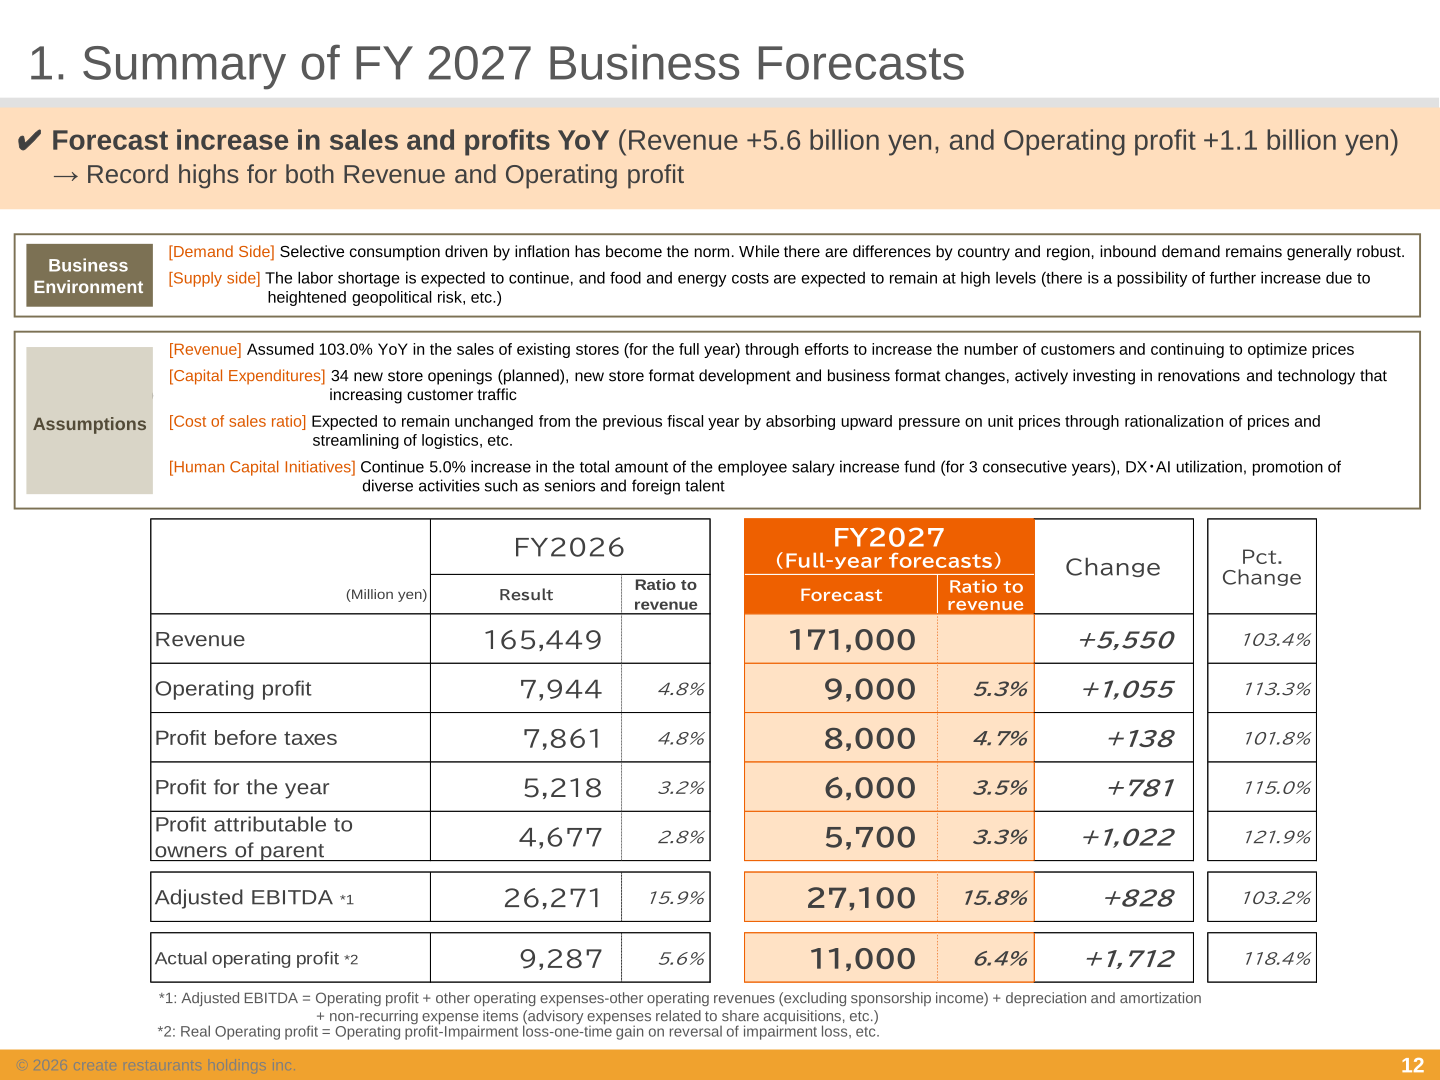
Profit is expected to increase in all categories. From FY 2027 the SFP category is renamed the Izakaya category. By category, the FY 2027 forecasts are revenue of 59,700 million yen and Category CF of 6,290 million yen for CR, 52,500 million yen and 5,750 million yen for Specialty Brand, 33,400 million yen and 2,840 million yen for Izakaya, and 25,600 million yen and 2,660 million yen for Overseas, where revenue is expected to decrease due to the closure of unprofitable stores while profit increases following the CEO change at Il Fornaio (America). The store count is forecast at 1,155 at the end of FY 2027.
Shareholder Returns
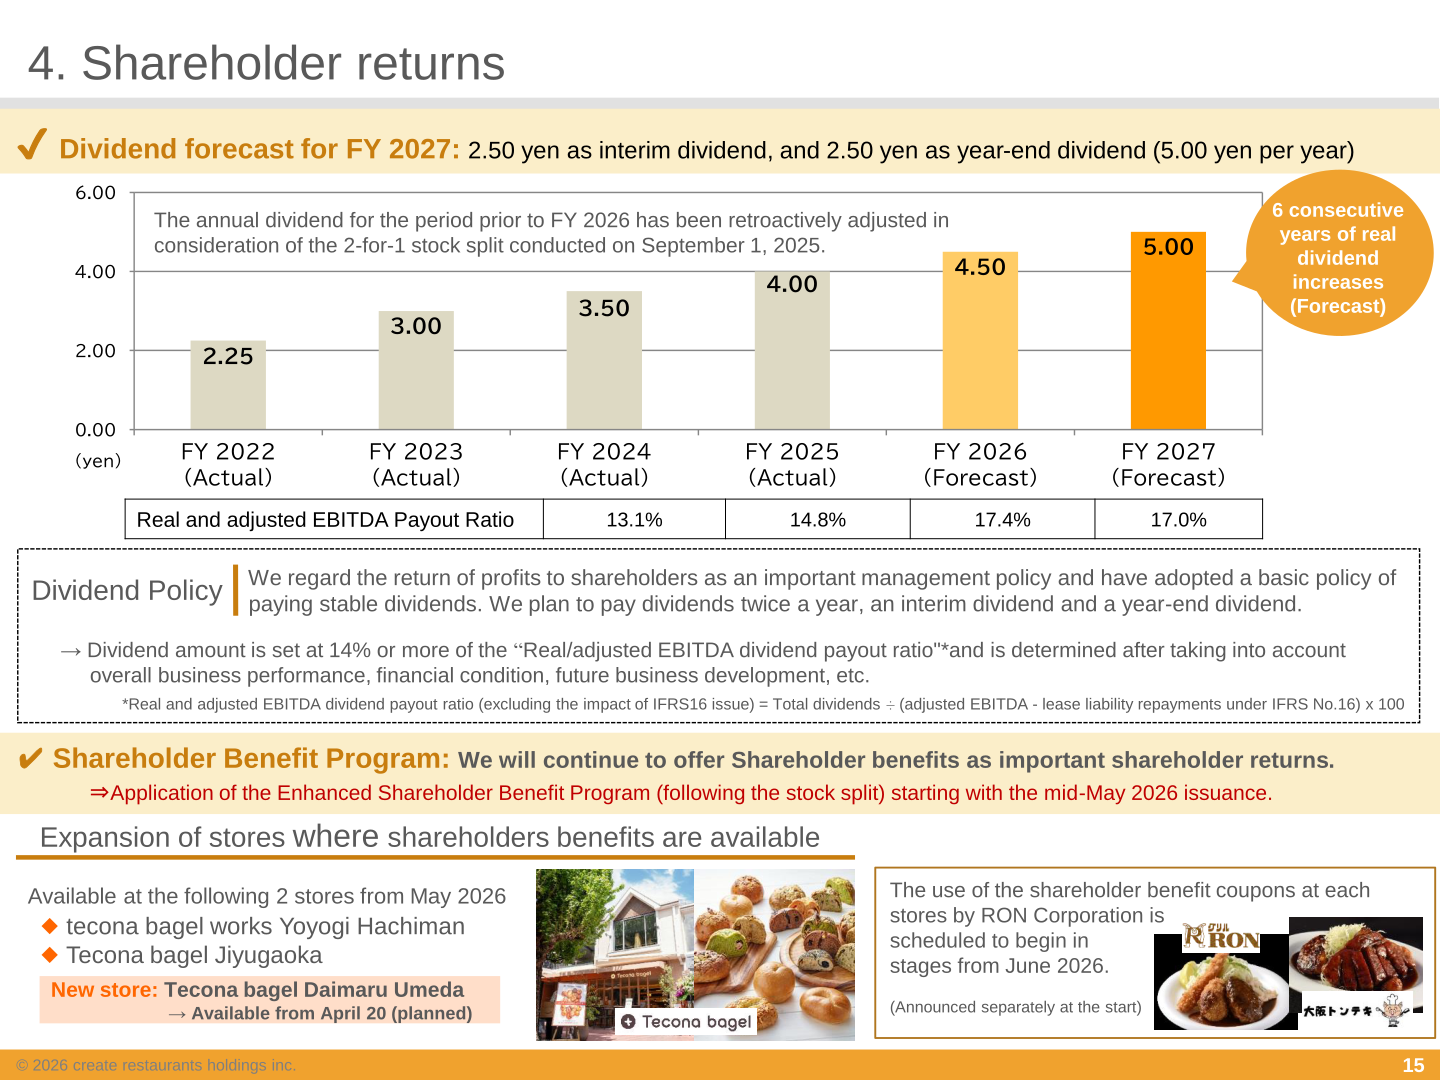
The company’s basic policy is to pay stable dividends twice a year (interim and year-end), with the dividend amount set at 14% or more of the “Real/adjusted EBITDA dividend payout ratio” (total dividends divided by adjusted EBITDA less lease liability repayments under IFRS No. 16). The annual dividend for FY 2026 was 4.50 yen per share (after taking into account the 2-for-1 stock split conducted on September 1, 2025), and the FY 2027 forecast is 5.00 yen per year (2.50 yen interim and 2.50 yen year-end), which the company describes as 6 consecutive years of real dividend increases. The Enhanced Shareholder Benefit Program (following the stock split) applies from the mid-May 2026 issuance.
| Item | FY 2027 (Forecast) | FY 2026 | FY 2025 (Actual) |
|---|---|---|---|
| Annual dividend per share | 5.00 yen | 4.50 yen | 4.00 yen |
| Real and adjusted EBITDA payout ratio | 17.0% | 17.4% | 14.8% |
Merger with SFP Holdings and Medium-Term Management Plan
On April 14, 2026, create restaurants holdings and SFP Holdings Co., Ltd. (TSE Prime, 3198) announced a merger to resolve the parent-subsidiary dual listing. CRH is the surviving company in an absorption merger, allotting 3.2 shares of its common stock for each SFPHD share, with a scheduled effective date of July 1, 2026. The company cites consolidation of redundant holding-company and infrastructure functions, reduction of listing maintenance costs, and strategic use of group resources, including fundamental improvement of the Izakaya business, as purposes of the merger. There are no changes to the dividend policy or the CRH shareholder benefit program due to the merger.
Under the Medium-Term Management Plan, the FY 2030 target, which includes M&A, is unchanged: revenue of 230,000 million yen, operating profit of 16,000 million yen, profit attributable to owners of parent of 9,500 million yen and adjusted EBITDA of 38,000 million yen, with adjusted ROIC of 25% and an equity ratio of 30% or more. The plan figures for FY 2028 and FY 2029 exclude pending M&A transactions.
| Item (million yen) | FY2026 (Result) | FY2027 (Forecasts) | FY2028 (Plan) | FY2029 (Plan) | FY2030 (Target) |
|---|---|---|---|---|---|
| Revenue | 165,449 | 171,000 | 178,000 | 185,000 | 230,000 |
| Operating profit | 7,944 | 9,000 | 10,000 | 12,000 | 16,000 |
| Profit attributable to owners of parent | 4,677 | 5,700 | 6,700 | 8,100 | 9,500 |
| Adjusted EBITDA | 26,271 | 27,100 | 28,100 | 29,900 | 38,000 |
| Actual operating profit | 9,287 | 11,000 | 12,000 | 14,000 | 18,000 |
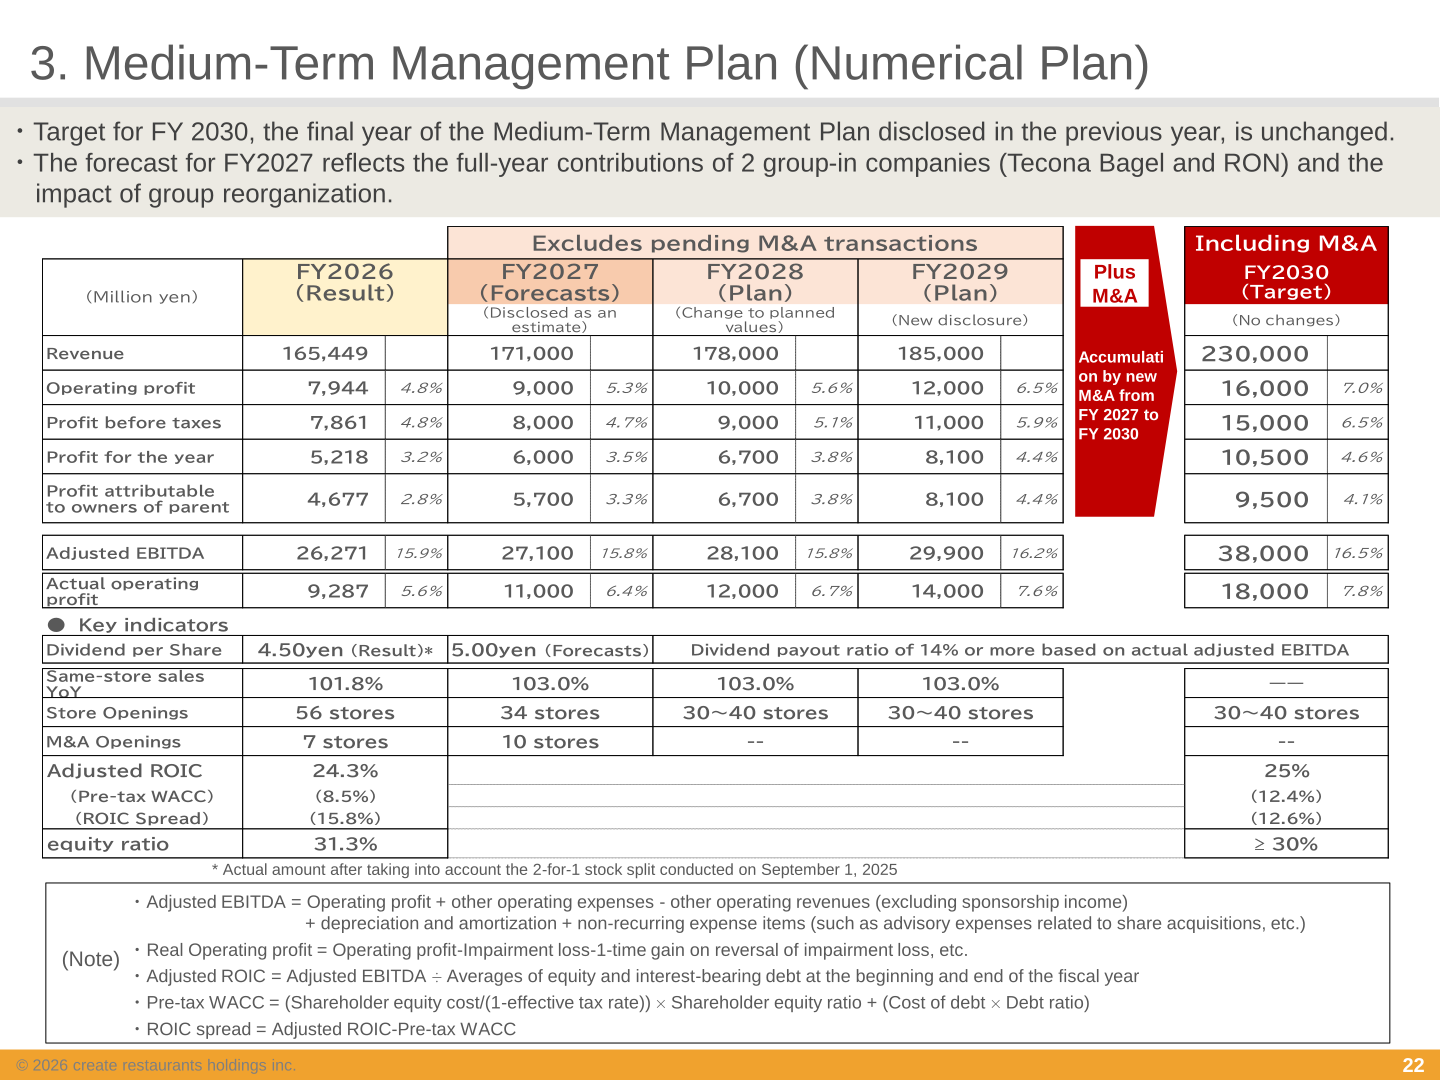
Priority initiatives for FY 2027, the second year of the plan, include initiatives to increase customer numbers at existing stores, fundamental improvement of the Izakaya business, aggressive development of next core brands, accelerating domestic and overseas M&A (aiming for at least 2 M&A deals per year, mainly in Japan and North America), and expansion into Asia FC and Europe. A new management structure is planned after the Annual General Meeting of Shareholders on May 27, 2026, with Jun Kawai as Representative Director & President CEO and Hitoshi Gotoh as Representative Director & Chairman.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















