
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
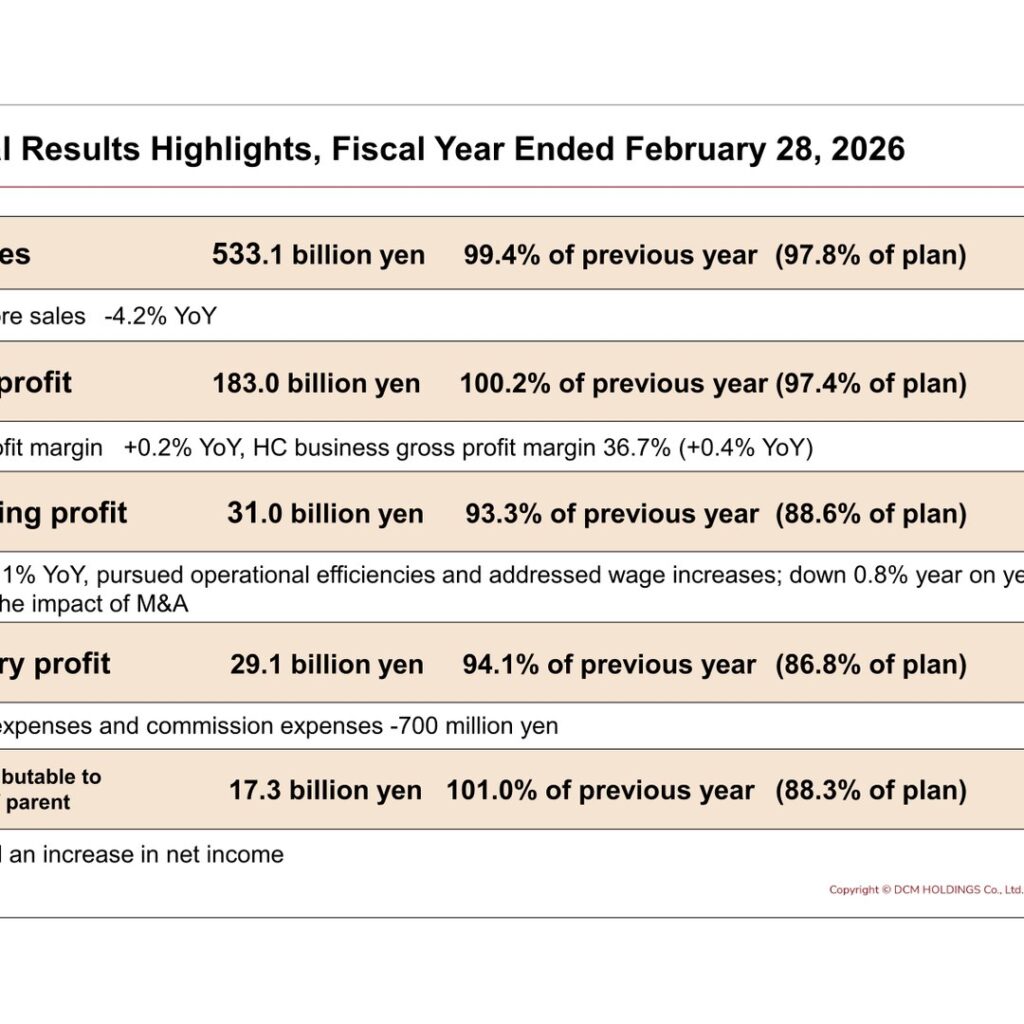
DCM Holdings, Japan’s largest home-center group, reported results for the fiscal year ended February 28, 2026. Net sales edged down to 533,107 million yen (99.4% of the previous year) as same-store sales declined, but an improved gross profit margin and systematic SG&A control lifted profit attributable to owners of parent to 17,310 million yen (101.0% of the previous year), securing a year-on-year increase in net income. Operating profit fell to 31,014 million yen (93.3%) and ordinary profit to 29,158 million yen (94.1%).
Note: DCM Holdings uses a February fiscal year-end. The “FY2025” in this article’s title refers to the fiscal year ended February 28, 2026 (March 1, 2025 to February 28, 2026), the company’s most recent completed full year. Figures and period labels in the body and tables follow the company’s own materials (e.g., “FYE February 2026”).
Consolidated Results (Full-Year Actual)
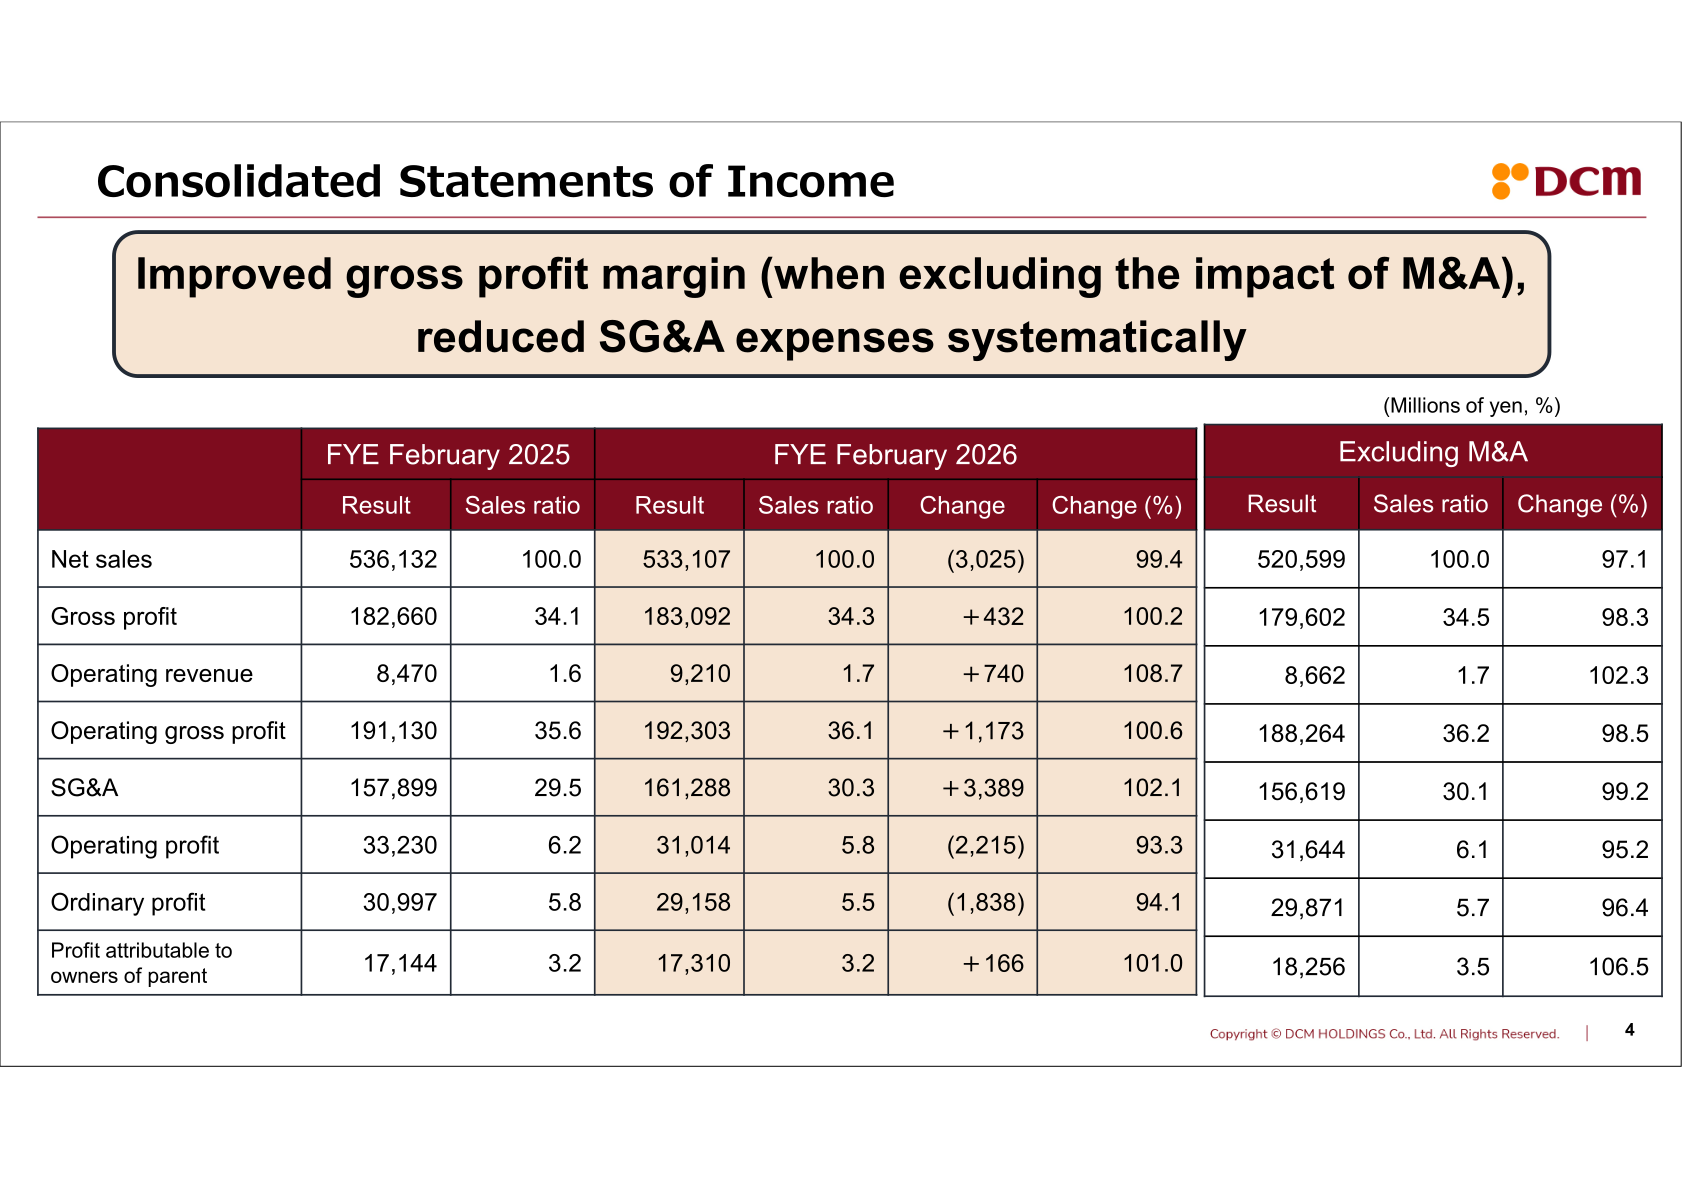
On the full-year consolidated income statement, gross profit rose slightly to 183,092 million yen (+432 million yen, 100.2%) even as net sales declined, reflecting a +0.2 point improvement in the gross profit margin (with the home-center business gross profit margin at 36.7%, +0.4 point). SG&A expenses increased 2.1% to 161,288 million yen, partly due to M&A; excluding the M&A impact, SG&A was down 0.8% year on year. As a result, operating profit and ordinary profit declined, while net income rose.
| Item | FYE Feb 2026 | FYE Feb 2025 | Change | YoY (%) |
|---|---|---|---|---|
| Net sales | 533,107 | 536,132 | (3,025) | 99.4 |
| Gross profit | 183,092 | 182,660 | +432 | 100.2 |
| Operating gross profit | 192,303 | 191,130 | +1,173 | 100.6 |
| SG&A expenses | 161,288 | 157,899 | +3,389 | 102.1 |
| Operating profit | 31,014 | 33,230 | (2,215) | 93.3 |
| Ordinary profit | 29,158 | 30,997 | (1,838) | 94.1 |
| Profit attributable to owners of parent | 17,310 | 17,144 | +166 | 101.0 |
Sales by Product Category and Business
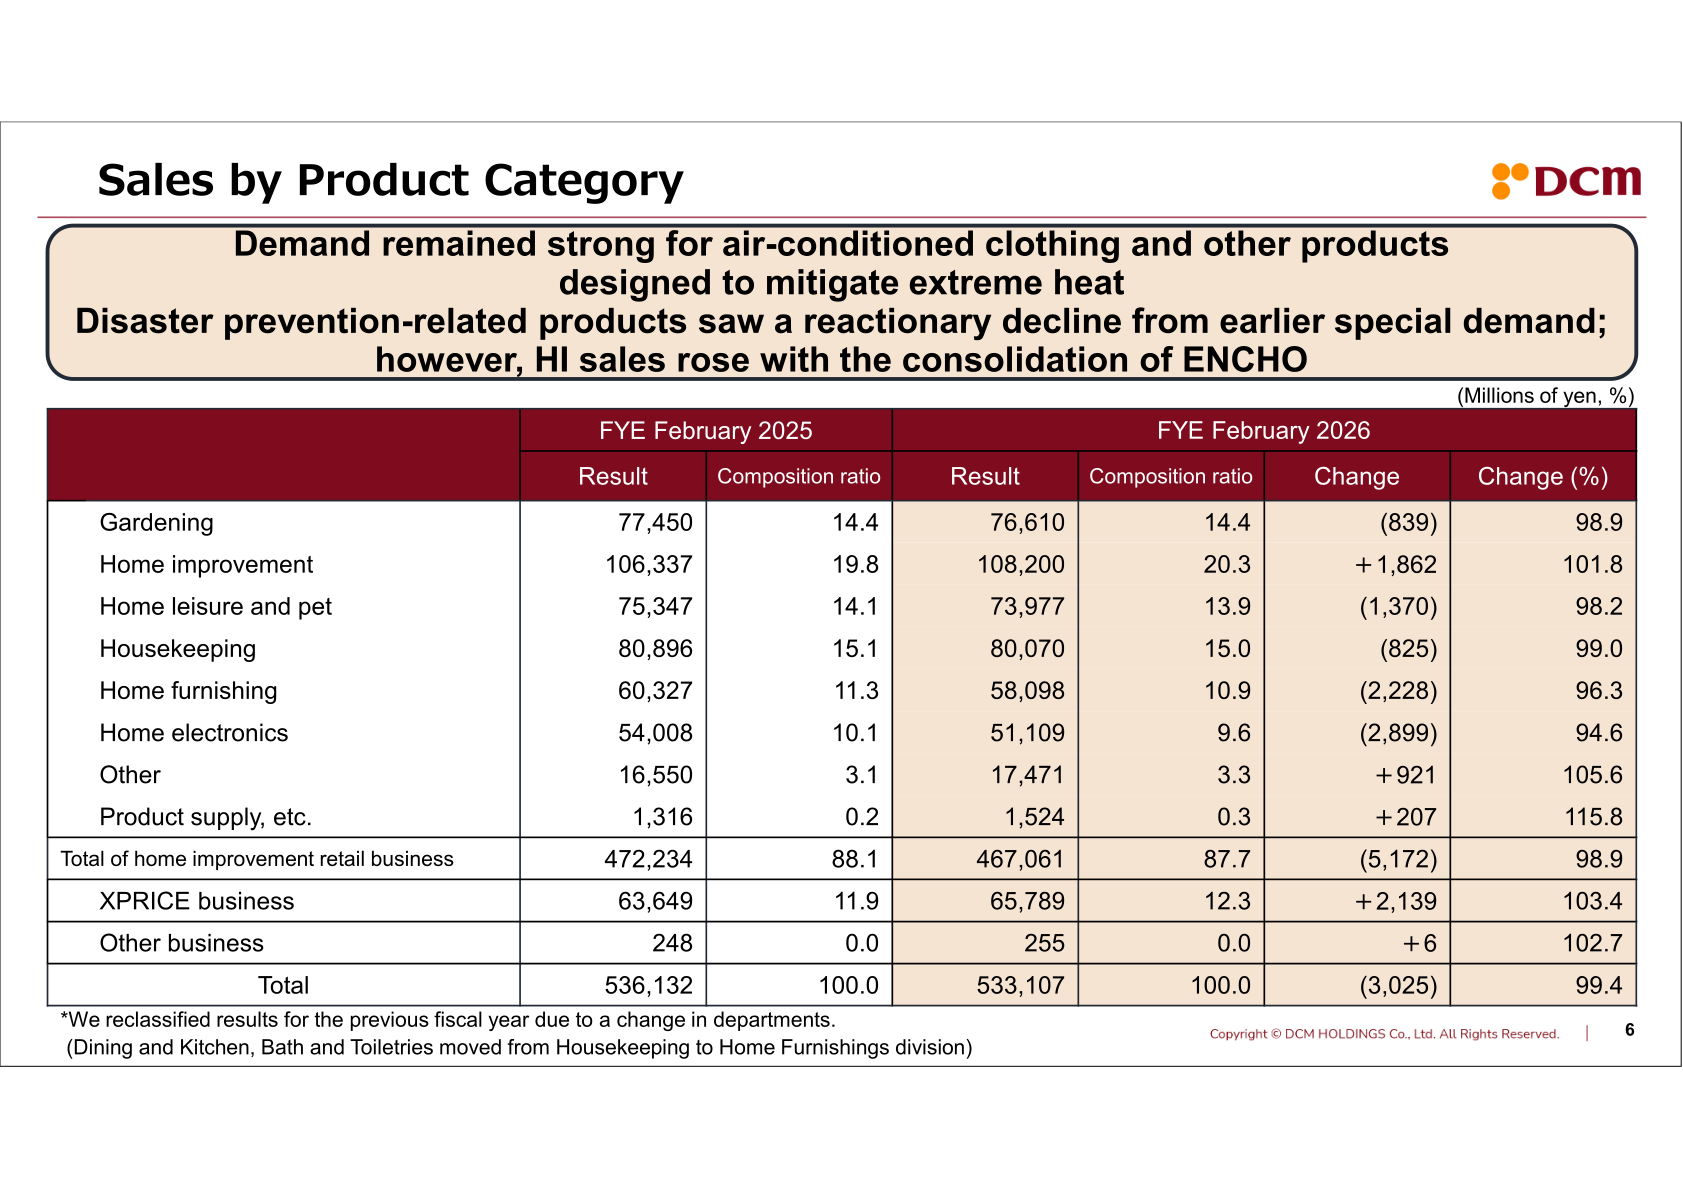
By product category, Home improvement grew to 108,200 million yen (101.8%) and Other categories rose, while Home electronics (94.6%), Home furnishing (96.3%) and Home leisure and pet (98.2%) declined. Total home-improvement retail business sales were 467,061 million yen (98.9%), while the XPRICE business grew to 65,789 million yen (103.4%). (The company reclassified prior-year figures due to a departmental change, moving Dining and Kitchen and Bath and Toiletries from Housekeeping to Home Furnishings.)
| Category / Business | FYE Feb 2026 | FYE Feb 2025 | Change | YoY (%) |
|---|---|---|---|---|
| Gardening | 76,610 | 77,450 | (839) | 98.9 |
| Home improvement | 108,200 | 106,337 | +1,862 | 101.8 |
| Home leisure and pet | 73,977 | 75,347 | (1,370) | 98.2 |
| Housekeeping | 80,070 | 80,896 | (825) | 99.0 |
| Home furnishing | 58,098 | 60,327 | (2,228) | 96.3 |
| Home electronics | 51,109 | 54,008 | (2,899) | 94.6 |
| Other | 17,471 | 16,550 | +921 | 105.6 |
| Product supply, etc. | 1,524 | 1,316 | +207 | 115.8 |
| Total of home improvement retail business | 467,061 | 472,234 | (5,172) | 98.9 |
| XPRICE business | 65,789 | 63,649 | +2,139 | 103.4 |
| Other business | 255 | 248 | +6 | 102.7 |
| Total | 533,107 | 536,132 | (3,025) | 99.4 |
Same-Store Sales and Margins
Full-year same-store sales fell 4.2% year on year, with the number of customers down 5.7% and average customer spend up 1.6%. The company cited a reactionary decline in demand for emergency and disaster-prevention supplies following earlier special demand, partly offset by strong demand for heat-mitigation products such as air-conditioned clothing. The gross profit margin improved to 36.7% (36.9%, up 0.6 point, when excluding ENCHO), supported by stronger private-brand sales; the private-brand net sales composition rose to 27.0% (+1.0 point).
Forecast for Fiscal Year Ending February 28, 2027
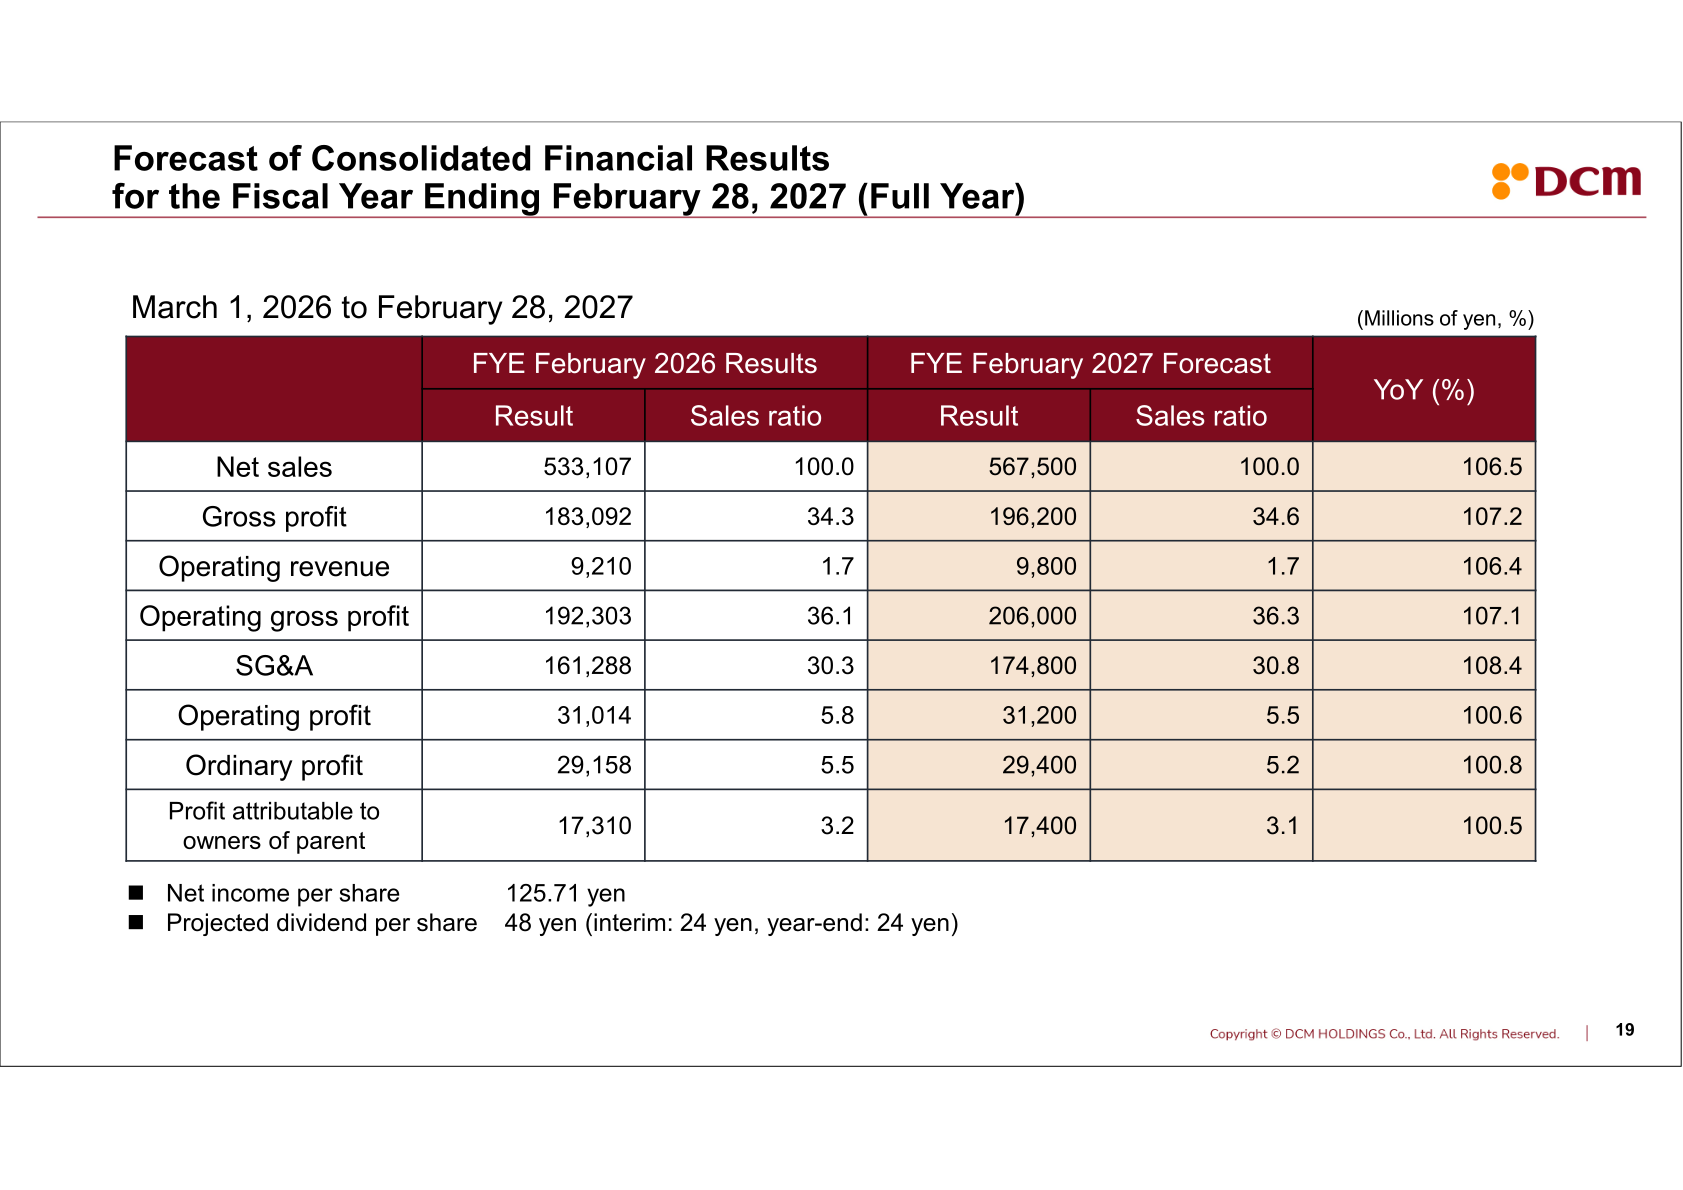
For the next fiscal year (March 1, 2026 to February 28, 2027), DCM forecasts net sales of 567,500 million yen (106.5%), gross profit of 196,200 million yen (107.2%), operating profit of 31,200 million yen (100.6%), ordinary profit of 29,400 million yen (100.8%) and profit attributable to owners of parent of 17,400 million yen (100.5%). Net income per share is projected at 125.71 yen, with a planned annual dividend of 48 yen (interim 24 yen, year-end 24 yen). Full-year same-store sales are assumed to rise 0.4%.
| Item | FYE Feb 2027 Forecast | FYE Feb 2026 Result | YoY (%) |
|---|---|---|---|
| Net sales | 567,500 | 533,107 | 106.5 |
| Gross profit | 196,200 | 183,092 | 107.2 |
| Operating profit | 31,200 | 31,014 | 100.6 |
| Ordinary profit | 29,400 | 29,158 | 100.8 |
| Profit attributable to owners of parent | 17,400 | 17,310 | 100.5 |
Shareholder Returns
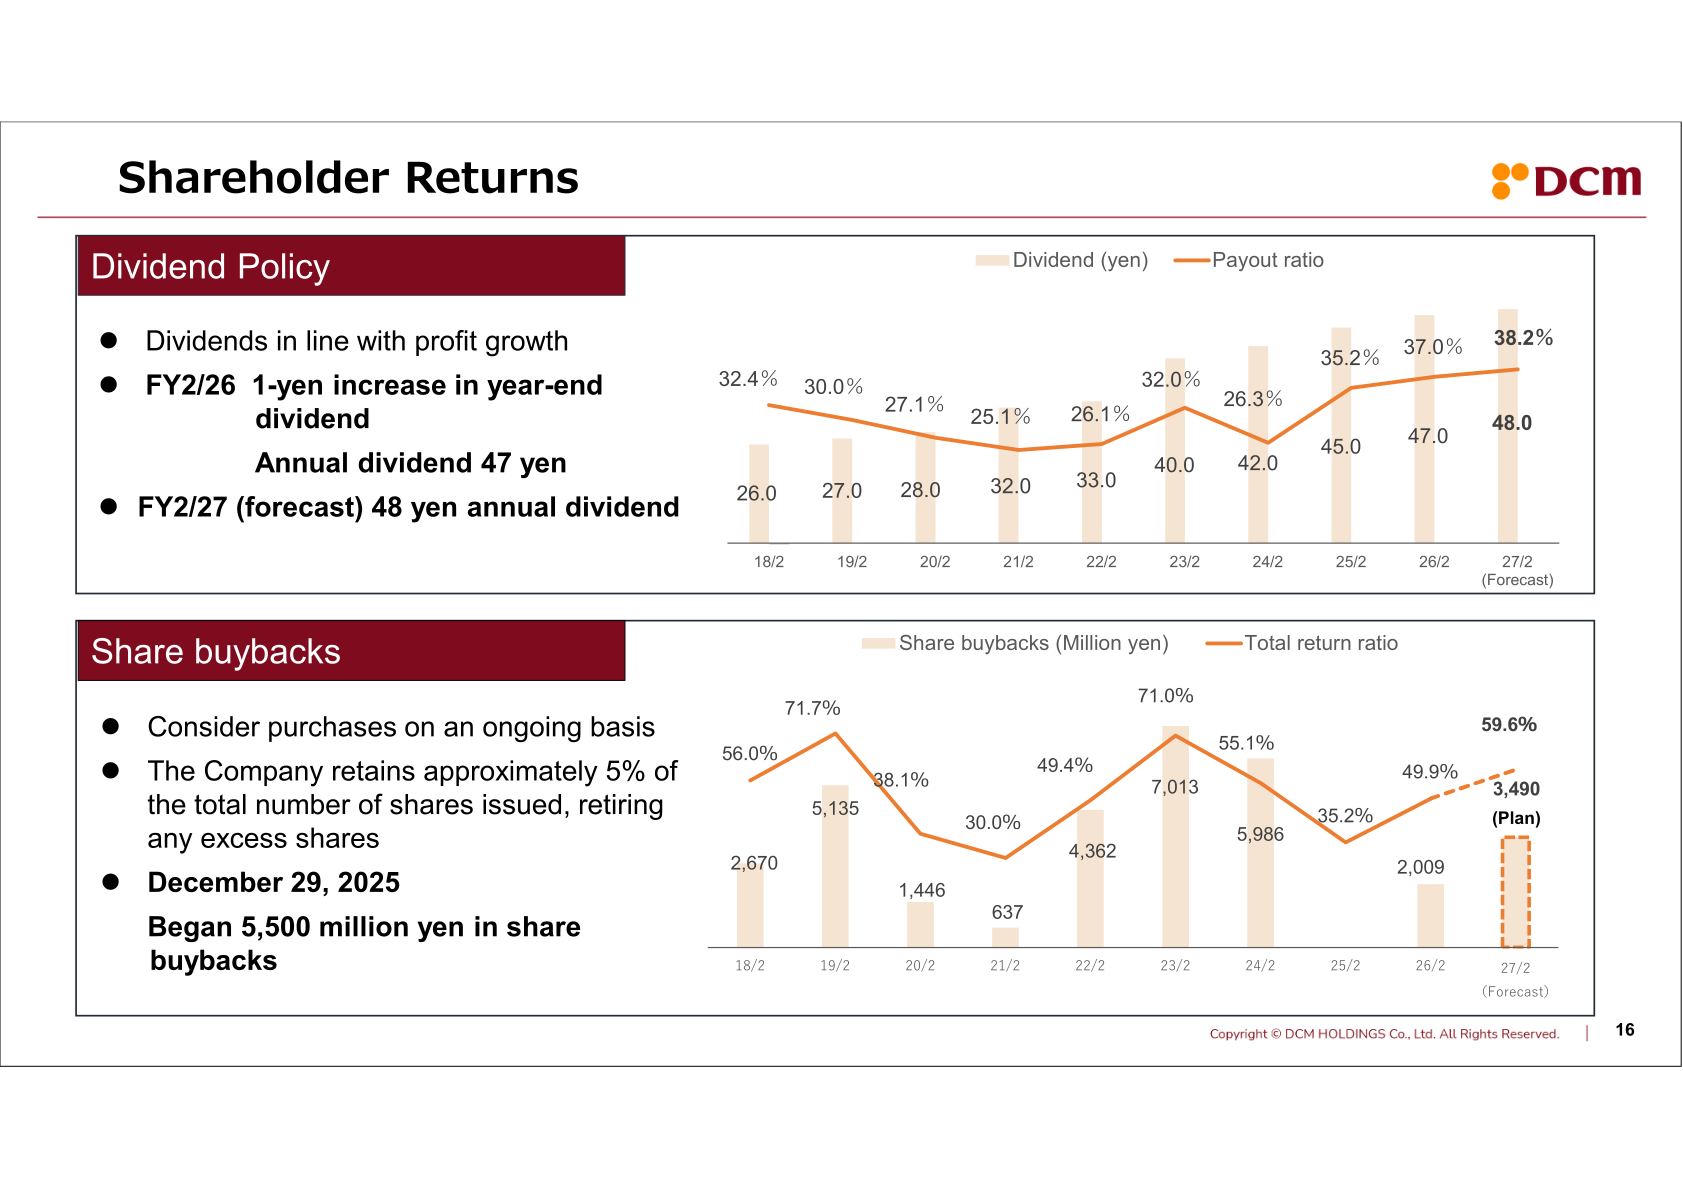
DCM’s dividend policy targets dividends in line with profit growth. For the fiscal year ended February 28, 2026 it raised the year-end dividend by 1 yen, bringing the annual dividend to 47 yen (payout ratio 37.0%, against EPS of 127.02 yen), and it plans a 48-yen annual dividend for the year ending February 28, 2027 (payout ratio 38.2%). On December 29, 2025 the company began a share buyback of 5,500 million yen. It states that it will continue to consider buybacks on an ongoing basis and retains approximately 5% of the total number of shares issued, retiring any excess shares.
| Item | FYE Feb 2026 | FYE Feb 2027 (Forecast) |
|---|---|---|
| Annual dividend per share (yen) | 47.0 | 48.0 |
| Dividend payout ratio | 37.0% | 38.2% |
| Earnings per share (yen) | 127.02 | 125.71 |
Topics: M&A and Store Network
During the fiscal year, DCM consolidated ENCHO Co., Ltd. (from the third quarter) and HOME TECH Inc., recording goodwill of 3,319 million yen for ENCHO and 7,221 million yen for HOME TECH. Including these additions, the group operated 918 stores nationwide as of February 2026, up from 843 a year earlier. The company also continued to expand specialty formats, with Hodaka professional-tool stores reaching 73 (net sales 27,007 million yen, +7.4% year on year) and DCM Nicot small community stores reaching 116 (net sales 19,095 million yen, +3.0% year on year).
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















