
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
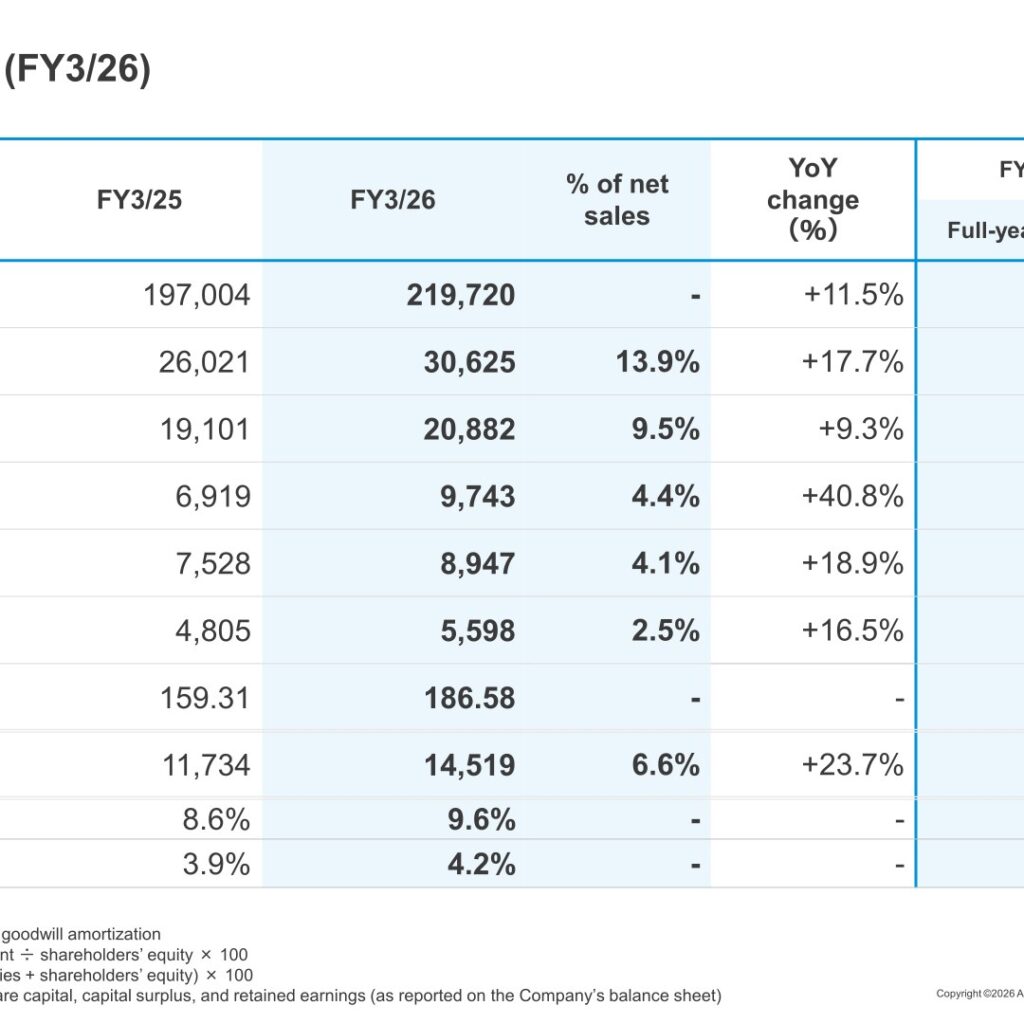
ALCONIX CORPORATION reported record-level results for the fiscal year ended March 31, 2026 (FY3/26). Net sales rose 11.5% year on year to ¥219,720 million, operating profit increased 40.8% to ¥9,743 million, and profit attributable to owners of parent grew 16.5% to ¥5,598 million. Growth was led by minor metals and battery-related transactions in the Electronic and Advanced Materials business and by chip-mounter parts, battery-related stamped parts, and aviation-, space-, and defense-related metal processed products in the Metal Processing business.
Note: ALCONIX labels its most recent completed fiscal year as “FY3/26” (year ended March 31, 2026); under this site’s convention it is classified as FY2025. All figures, tables, headings, and labels below follow the company’s own FY3/26 (actual) and FY3/27 (forecast) notation as shown in the source material.
Consolidated Results (FY3/26 Actual)
According to the Executive Summary, the operating environment featured expanding data-center-related businesses, firm smartphone-related demand, and semiconductor-related businesses trending toward recovery from the second half onward. Aluminum and copper market conditions and the non-ferrous metal scrap market also recovered from the second half, while minor metal prices such as tungsten surged. Operating profit margin improved 0.9pt to 4.4% and ordinary profit margin rose 0.2pt to 4.1%.
| Item (Millions of yen) | FY3/25 | FY3/26 | YoY change (%) |
|---|---|---|---|
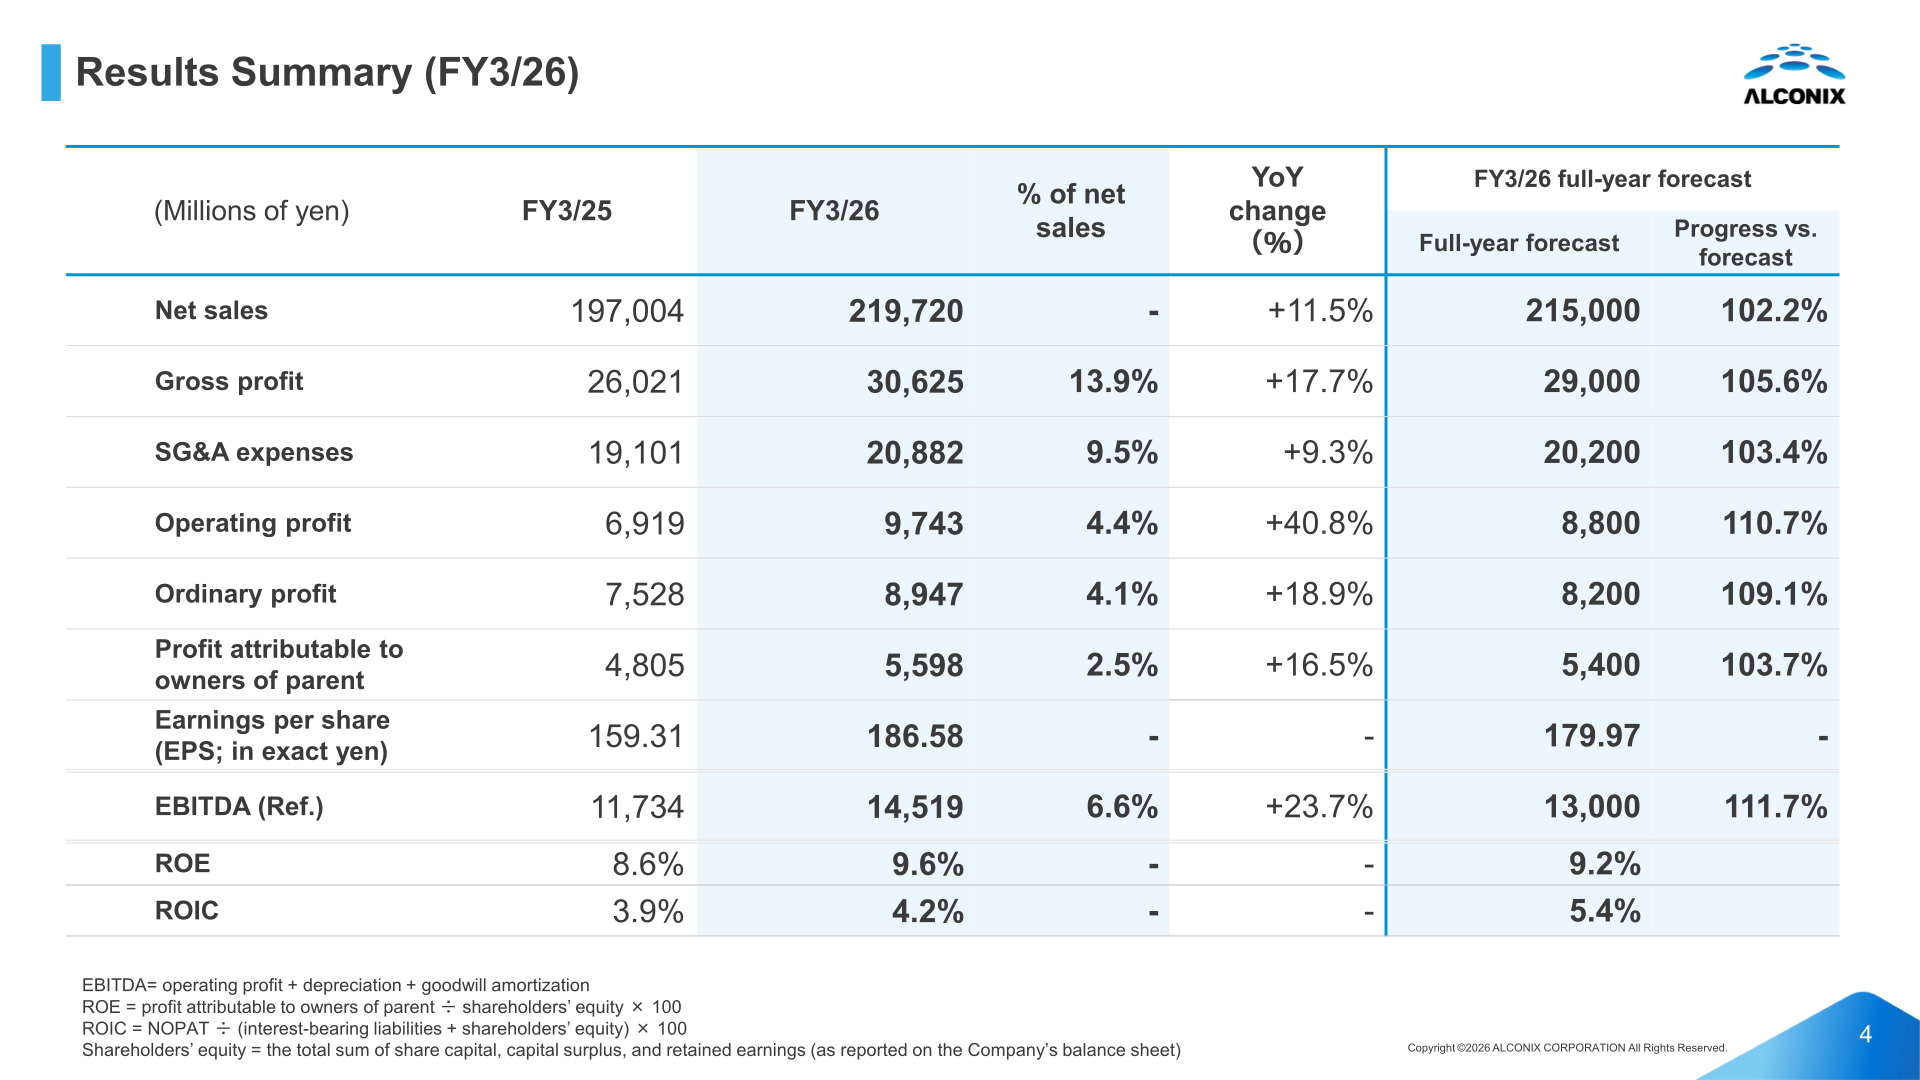
| Net sales | 197,004 | 219,720 | +11.5% |
| Gross profit | 26,021 | 30,625 | +17.7% |
| SG&A expenses | 19,101 | 20,882 | +9.3% |
| Operating profit | 6,919 | 9,743 | +40.8% |
| Ordinary profit | 7,528 | 8,947 | +18.9% |
| Profit attributable to owners of parent | 4,805 | 5,598 | +16.5% |
| EPS (exact yen) | 159.31 | 186.58 | – |
| EBITDA (Ref.) | 11,734 | 14,519 | +23.7% |
| ROE | 8.6% | 9.6% | – |
| ROIC | 3.9% | 4.2% | – |
Segment Results (FY3/26)
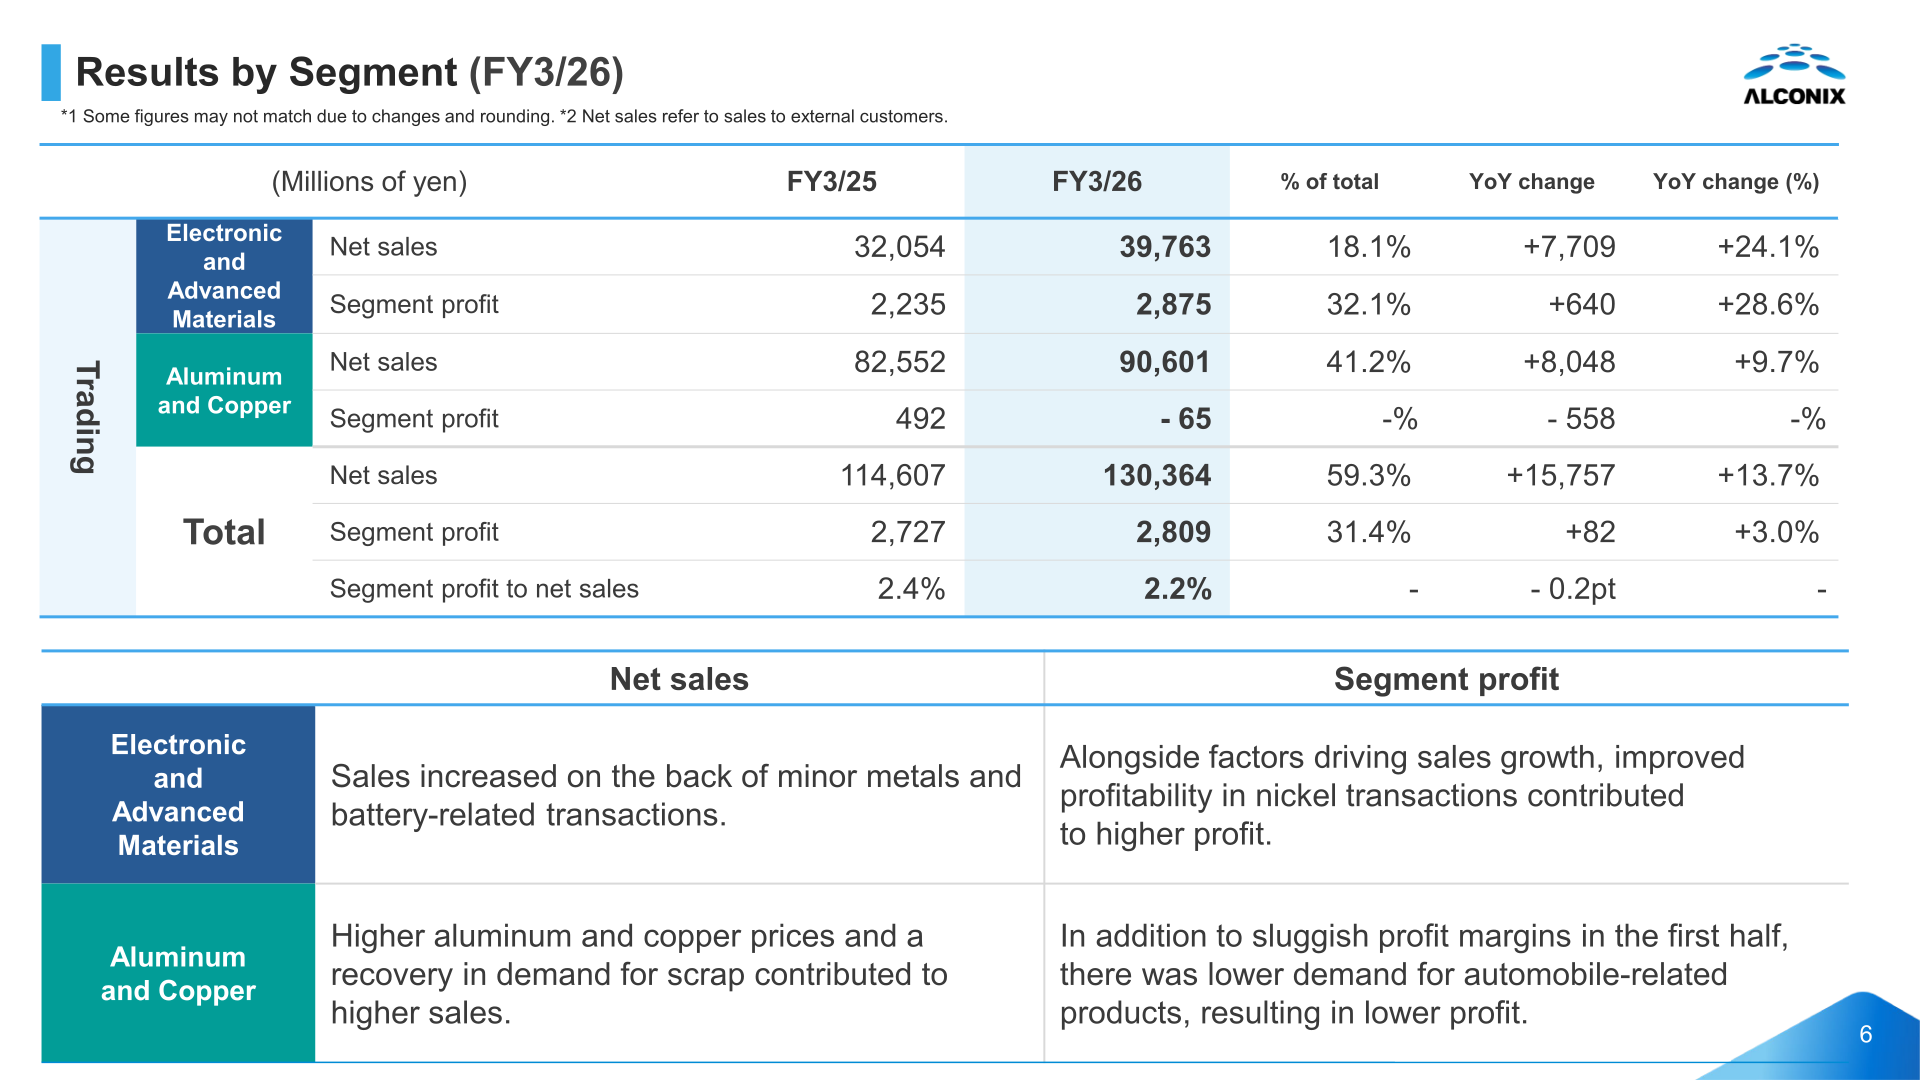
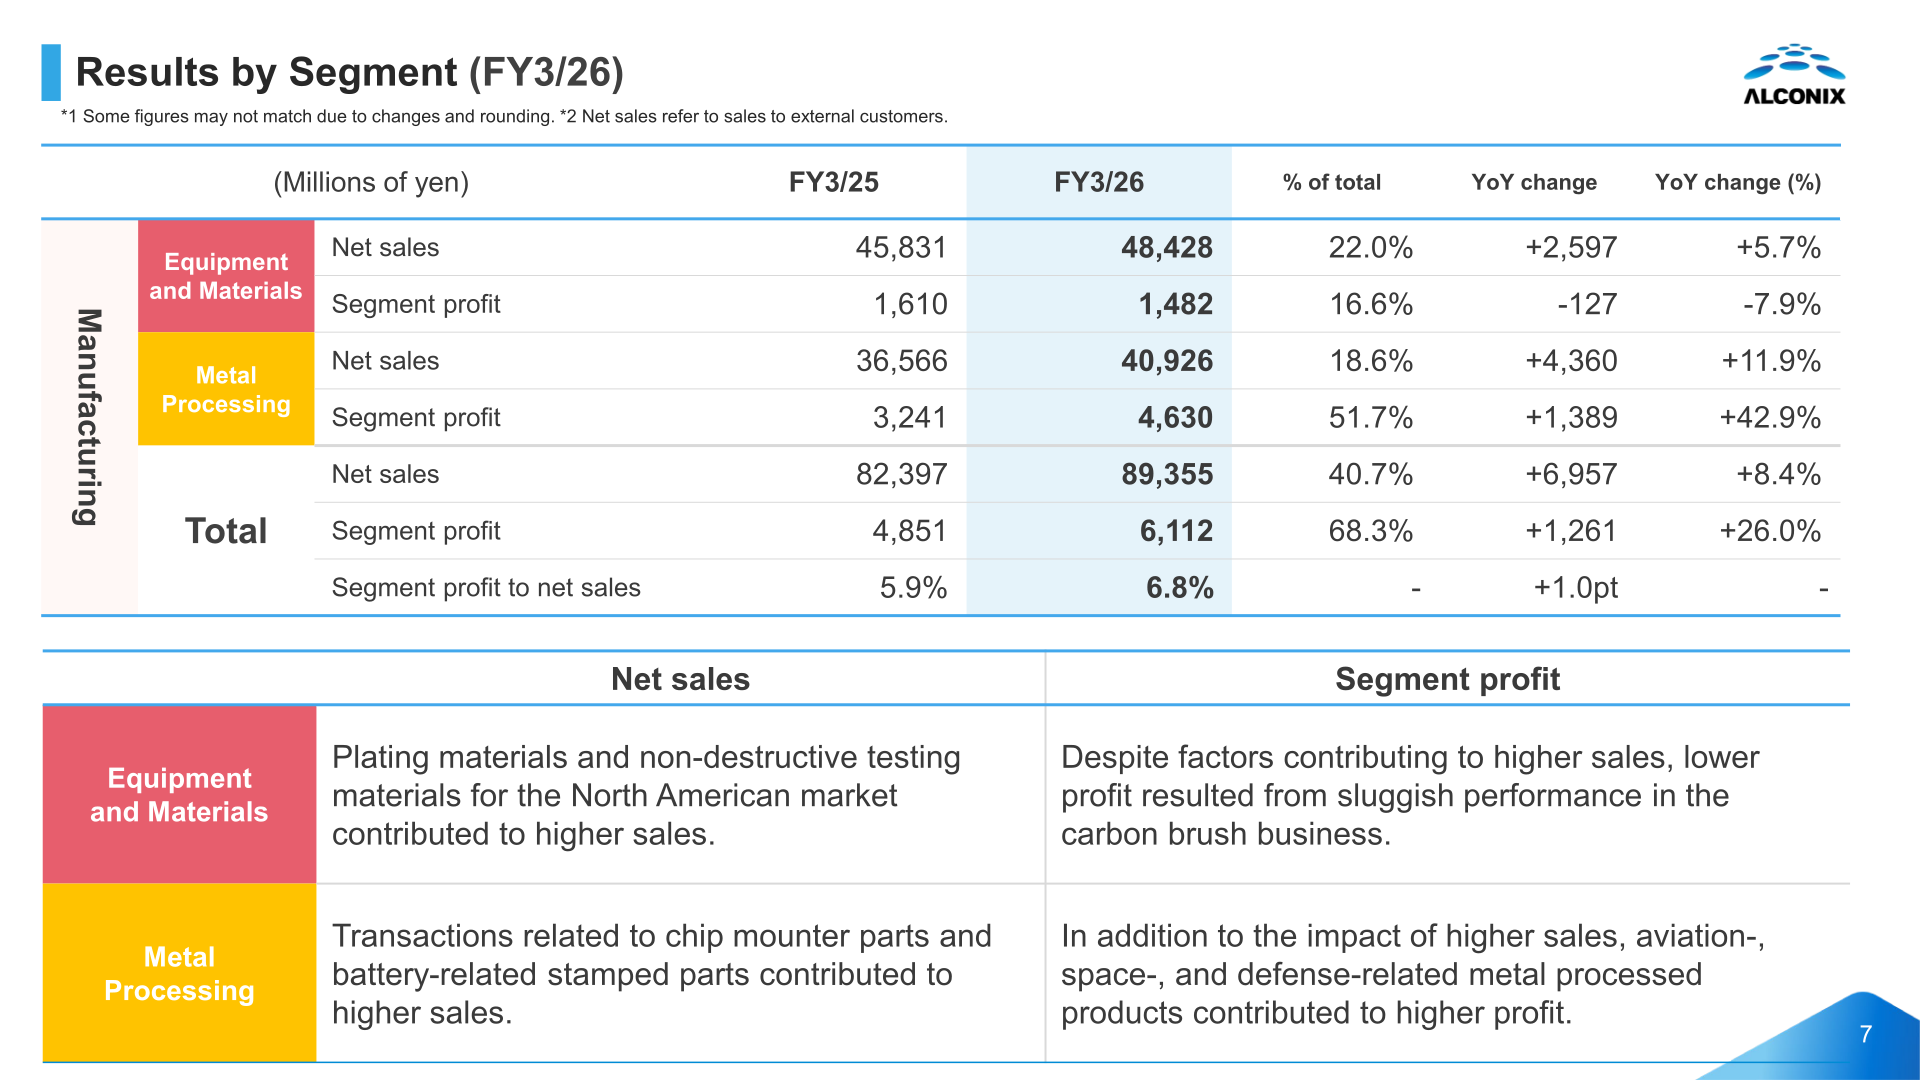
In the Trading business, Electronic and Advanced Materials grew sales on minor metals and battery-related transactions, with improved profitability in nickel transactions lifting profit; Aluminum and Copper posted higher sales on higher aluminum and copper prices and a recovery in scrap demand, but recorded a segment loss due to sluggish first-half margins and weaker automobile-related demand. In the Manufacturing business, Equipment and Materials grew sales on plating and non-destructive testing materials for the North American market but saw lower profit on a sluggish carbon brush business, while Metal Processing raised both sales and profit on chip-mounter parts, battery-related stamped parts, and aviation-, space-, and defense-related metal processed products.
| Segment | Metric (Millions of yen) | FY3/25 | FY3/26 |
|---|---|---|---|
| Electronic and Advanced Materials (Trading) | Net sales | 32,054 | 39,763 |
| Electronic and Advanced Materials (Trading) | Segment profit | 2,235 | 2,875 |
| Aluminum and Copper (Trading) | Net sales | 82,552 | 90,601 |
| Aluminum and Copper (Trading) | Segment profit | 492 | -65 |
| Trading total | Net sales | 114,607 | 130,364 |
| Trading total | Segment profit | 2,727 | 2,809 |
| Equipment and Materials (Manufacturing) | Net sales | 45,831 | 48,428 |
| Equipment and Materials (Manufacturing) | Segment profit | 1,610 | 1,482 |
| Metal Processing (Manufacturing) | Net sales | 36,566 | 40,926 |
| Metal Processing (Manufacturing) | Segment profit | 3,241 | 4,630 |
| Manufacturing total | Net sales | 82,397 | 89,355 |
| Manufacturing total | Segment profit | 4,851 | 6,112 |
FY3/27 Full-Year Forecast
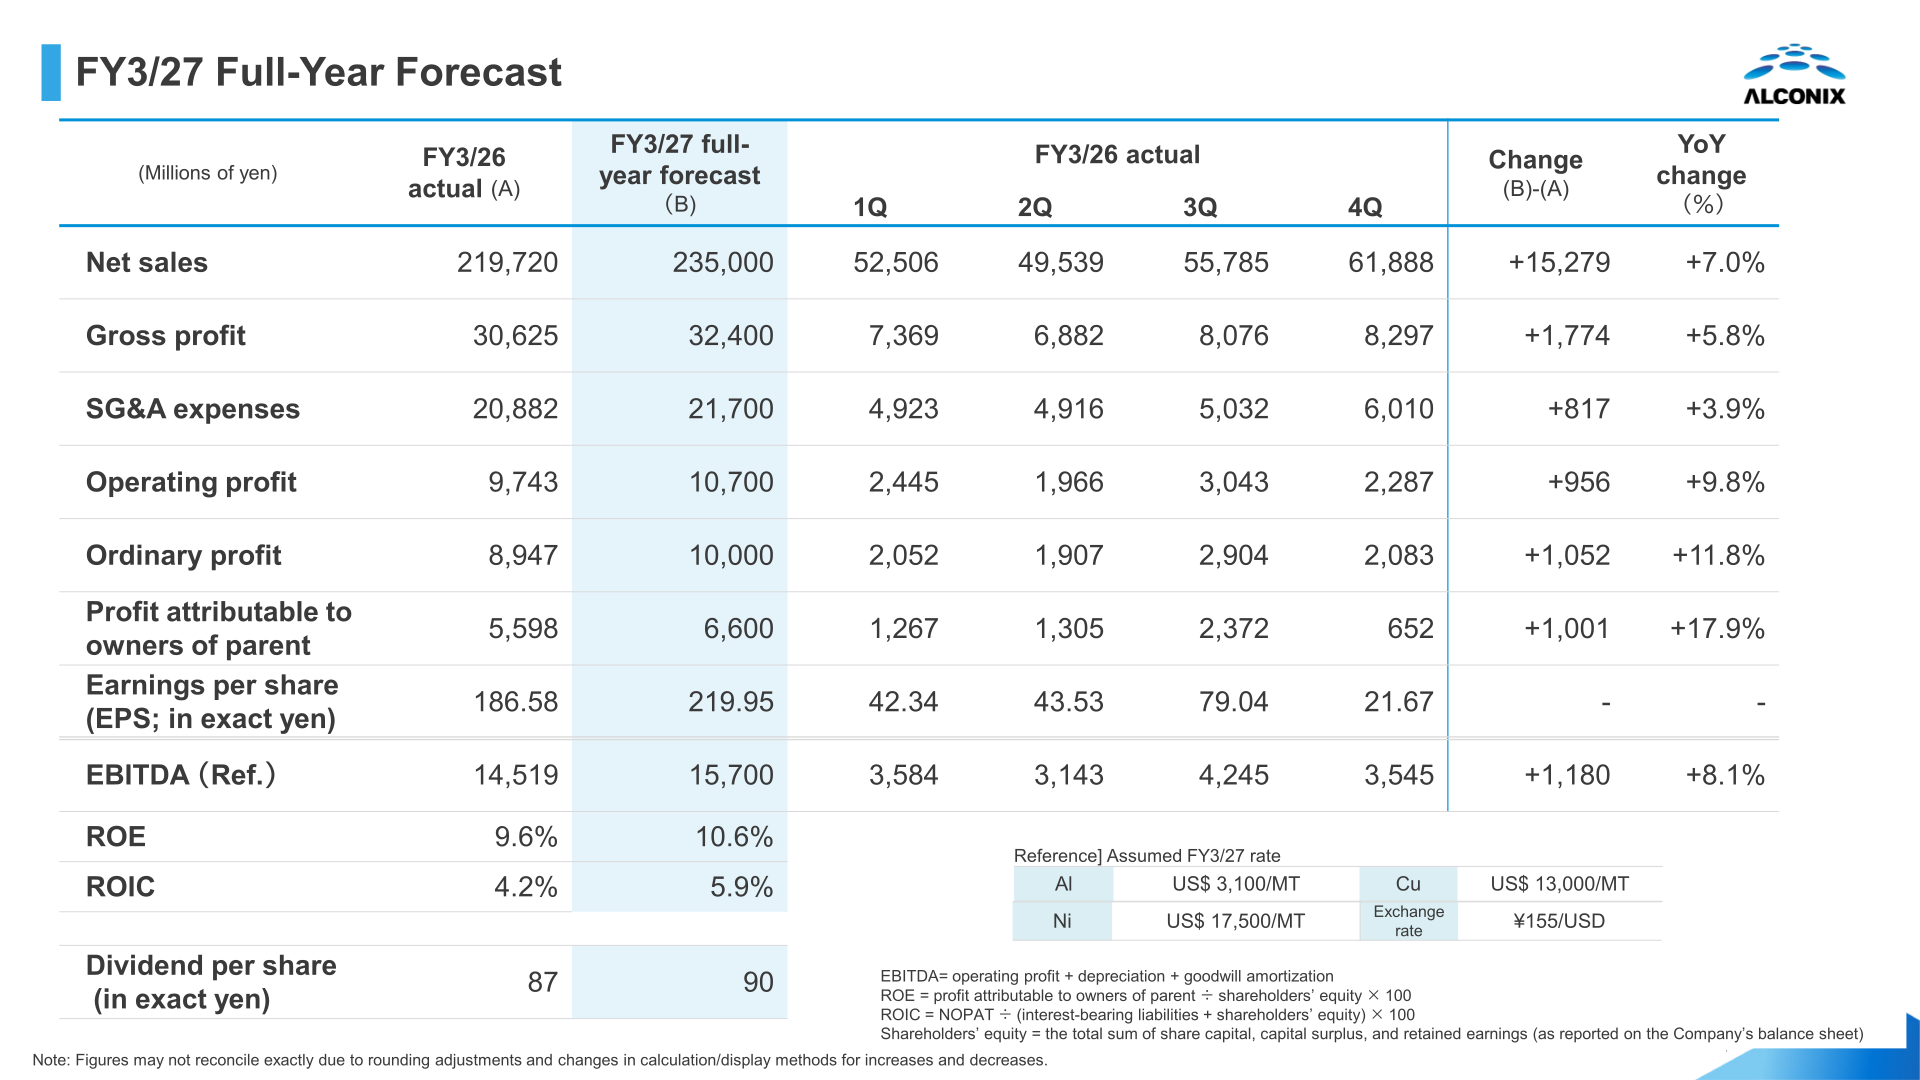
For FY3/27, ALCONIX forecasts net sales of ¥235,000 million (+7.0% YoY), operating profit of ¥10,700 million (+9.8%), ordinary profit of ¥10,000 million (+11.8%), and profit attributable to owners of parent of ¥6,600 million (+17.9%). The forecast assumes market prices of US$3,100/MT for aluminum, US$13,000/MT for copper, and US$17,500/MT for nickel, and an exchange rate of ¥155/USD.
| Item (Millions of yen) | FY3/27 Forecast | FY3/26 Actual | YoY change (%) |
|---|---|---|---|
| Net sales | 235,000 | 219,720 | +7.0% |
| Operating profit | 10,700 | 9,743 | +9.8% |
| Ordinary profit | 10,000 | 8,947 | +11.8% |
| Profit attributable to owners of parent | 6,600 | 5,598 | +17.9% |
| EPS (exact yen) | 219.95 | 186.58 | – |
| EBITDA (Ref.) | 15,700 | 14,519 | +8.1% |
| ROE | 10.6% | 9.6% | – |
| ROIC | 5.9% | 4.2% | – |
| Dividend per share (yen) | 90 | 87 | – |
Shareholder Returns
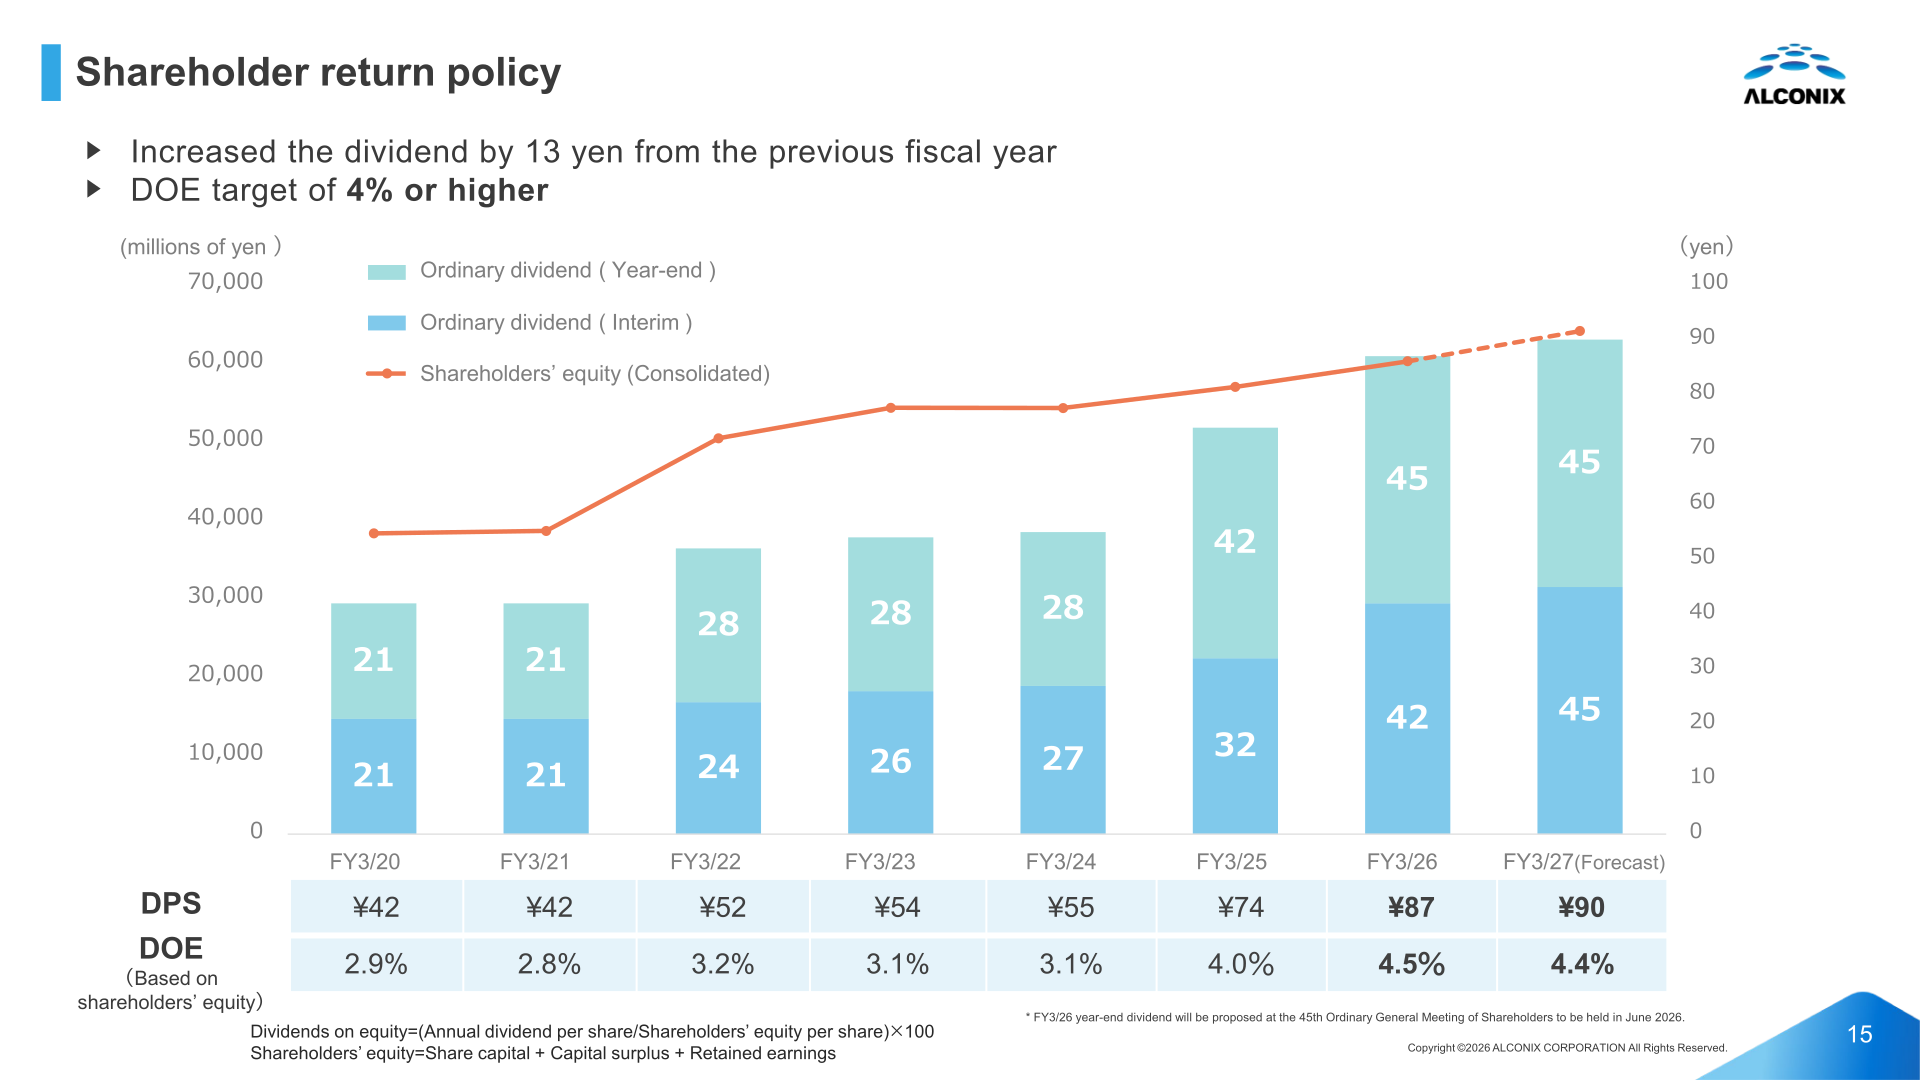
For FY3/26, ALCONIX raised the annual dividend by ¥13 from the previous fiscal year to ¥87 per share (interim ¥42 + year-end ¥45), equivalent to a dividend on equity (DOE) of 4.5%. The FY3/26 year-end dividend will be proposed at the 45th Ordinary General Meeting of Shareholders to be held in June 2026. For FY3/27 the company plans an annual dividend of ¥90 per share (DOE 4.4%). Under Long-Term Management Plan 2030, ALCONIX targets a DOE of 4% or higher.
| Item | FY3/25 | FY3/26 | FY3/27 (Forecast) |
|---|---|---|---|
| Annual dividend per share (yen) | 74 | 87 | 90 |
| DOE (based on shareholders’ equity) | 4.0% | 4.5% | 4.4% |
Progress on Long-Term Management Plan 2030
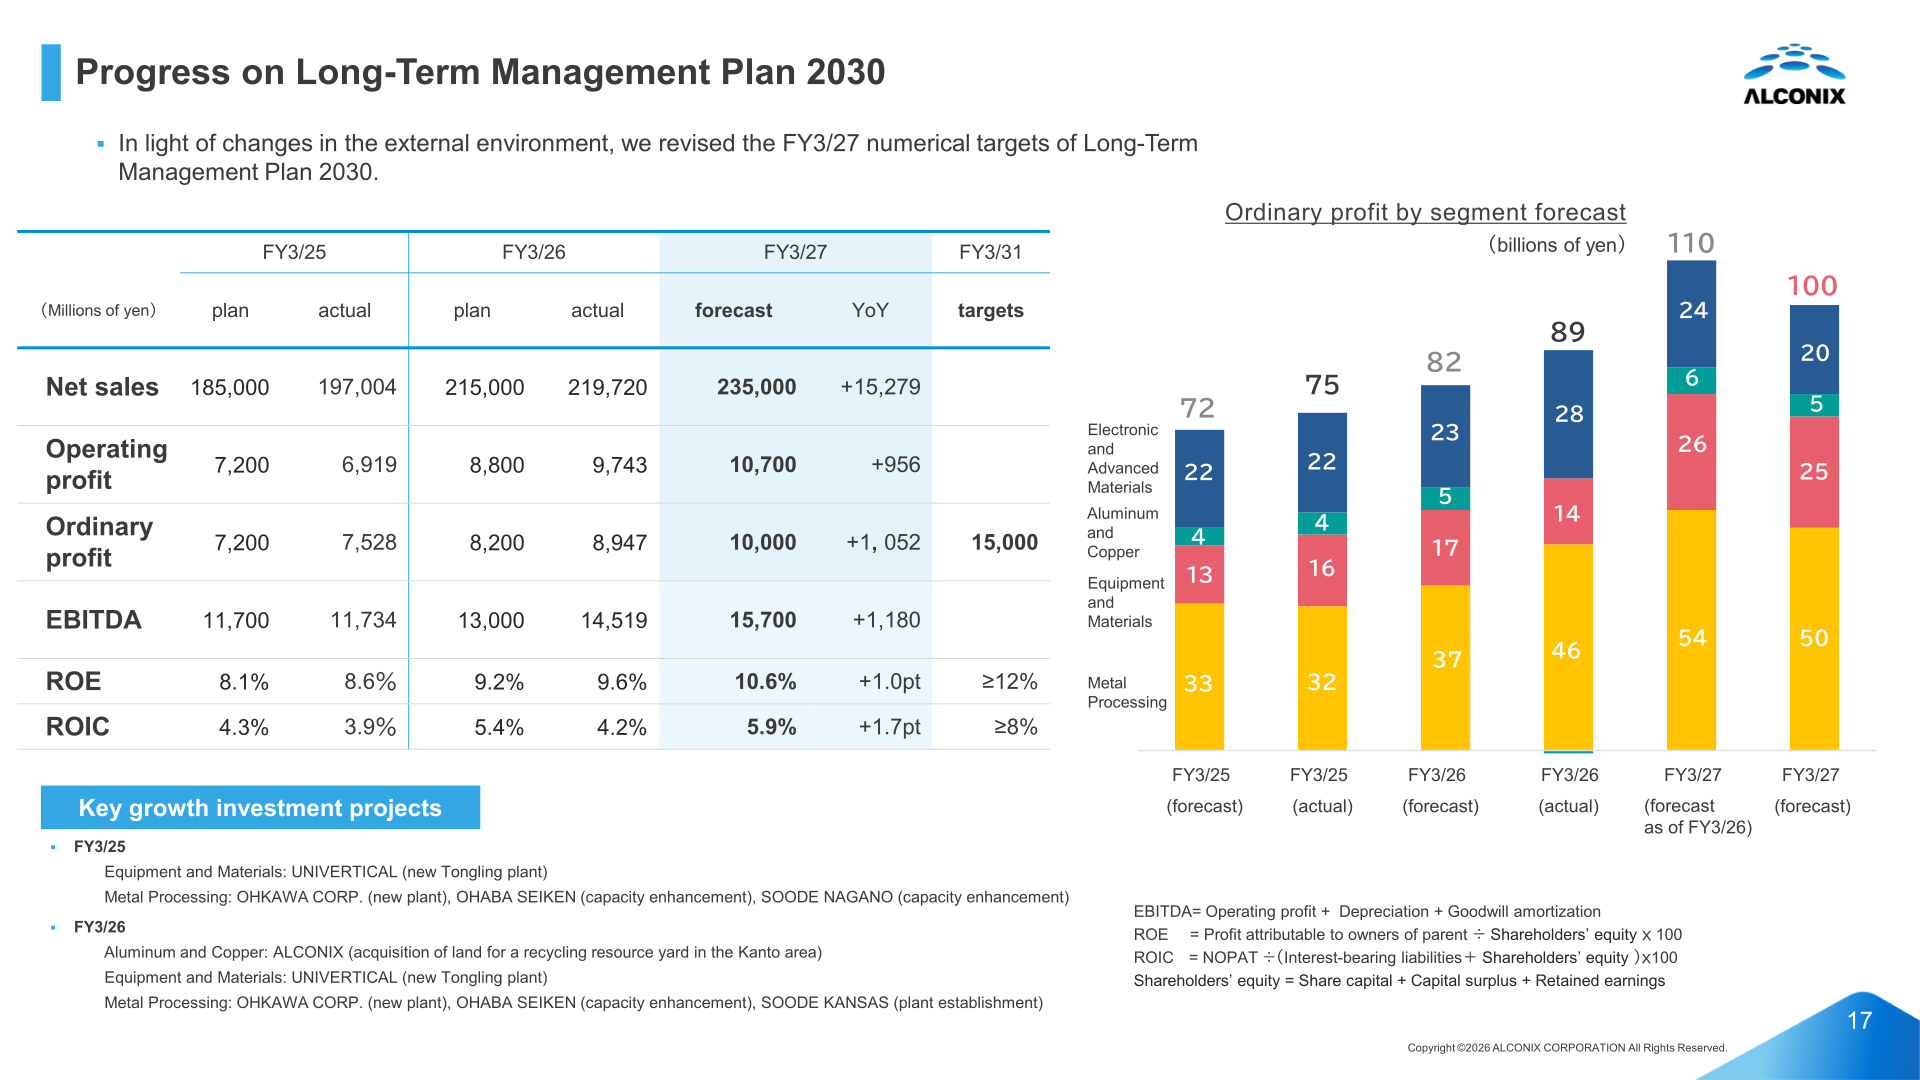
ALCONIX revised the FY3/27 numerical targets of Long-Term Management Plan 2030 in light of changes in the external environment. In FY3/26, operating profit (¥9,743 million), ordinary profit (¥8,947 million), EBITDA (¥14,519 million), and ROE (9.6%) all exceeded plan, while ROIC (4.2%) fell short of the 5.4% plan. FY3/31 targets include ordinary profit of ¥15,000 million, ROE of 12% or higher, and ROIC of 8% or higher. Strategic initiatives include a decided policy to integrate four companies in the Aluminum and Copper business, structural reforms of low-profit businesses, continued M&A, and expansion of the non-ferrous metal recycling business.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















