
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
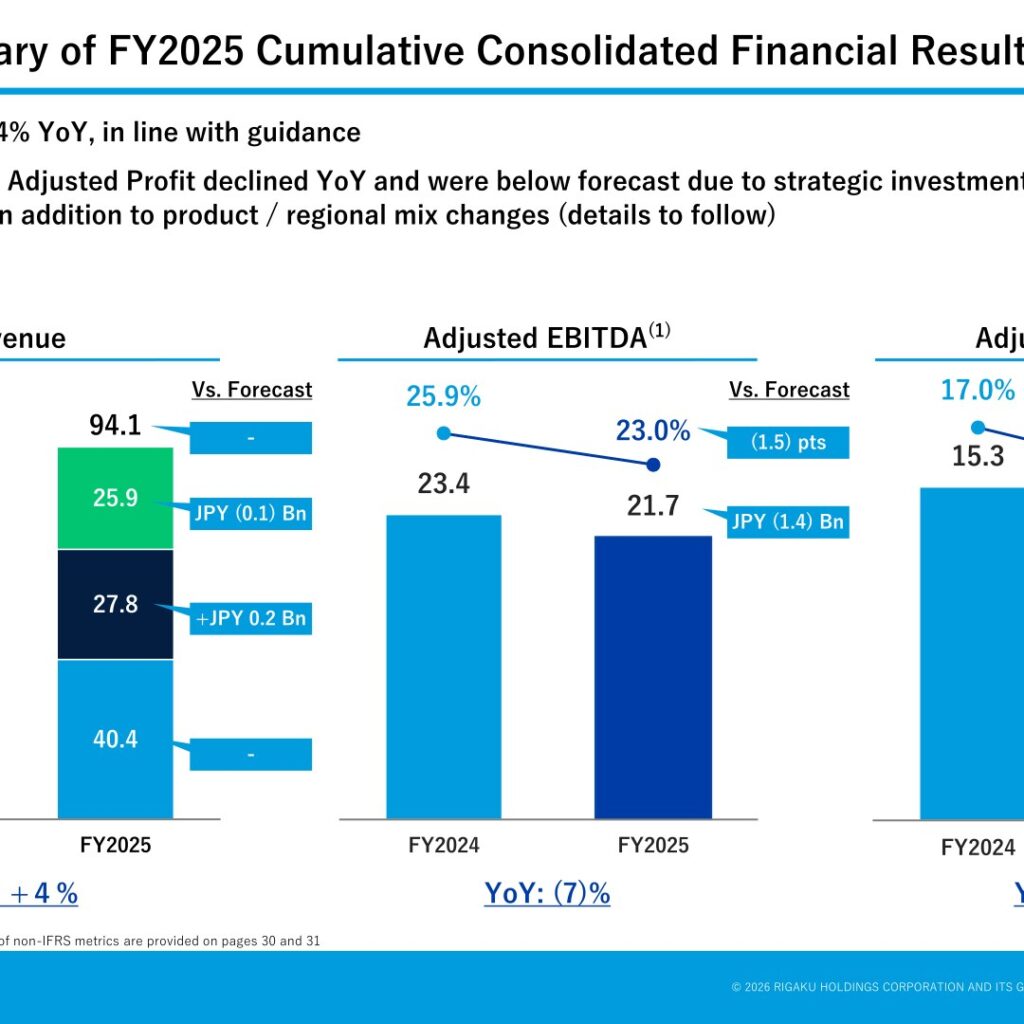
Rigaku Holdings Corporation (268A), an X-ray analytical instrument maker whose fiscal year ends on December 31, reported FY2025 (the fiscal year ended December 31, 2025) revenue of JPY 94.1 Bn, up +4% YoY and in line with guidance. Adjusted EBITDA fell to JPY 21.7 Bn (YoY (7)%) and Adjusted Profit to JPY 12.7 Bn (YoY (17)%), both below the company’s forecast, as strategic investments in manufacturing capacity expansion and R&D, together with product and regional mix changes, weighed on margins. Q4 revenue of JPY 34.6 Bn marked the highest quarterly revenue level on record, driven by Semiconductor Process Control Instruments. For FY2026 the company forecasts revenue of JPY 101.0 Bn and Adjusted EBITDA of JPY 25.3 Bn.
Consolidated Results (Full-Year Actual)
Revenue rose +4% YoY (3.9% as stated in the forecast table), in line with guidance. Against the company’s own forecast, revenue was on plan in total, with Semiconductor Process Control Instruments +JPY 0.2 Bn and Components and Services JPY (0.1) Bn. Adjusted EBITDA came in (1.5) pts / JPY (1.4) Bn below forecast, and Adjusted Profit (1.0) pts / JPY (0.9) Bn below forecast. Rigaku reports under IFRS and also presents non-IFRS measures including Adjusted EBITDA, Adjusted Operating Profit and Adjusted Profit; reconciliations are provided in the appendix of the materials.
| Item (JPY Bn unless noted) | FY2025 | FY2024 | YoY (as disclosed) |
|---|---|---|---|
| Revenue | 94.1 | 90.6 | +4% |
| Gross Profit | 52.8 | 52.3 | — |
| Operating Profit | 16.7 | 18.3 | — |
| Profit Before Taxes | 15.9 | 17.9 | — |
| Profit | 11.4 | 13.6 | — |
| EPS (JPY) | 50.19 | 60.44 | — |
| Adjusted Operating Profit | 18.6 | 20.9 | — |
| Adjusted Profit | 12.7 | 15.3 | (17)% |
| Adjusted EPS (JPY) | 55.19 | 66.61 | — |
| EBITDA | 21.8 | 23.2 | — |
| Adjusted EBITDA | 21.7 | 23.4 | (7)% |
| Adjusted EBITDA Margin | 23.0% | 25.9% | — |
| Adjusted ROE | 14.9% | 20.9% | — |
| R&D Expenses | 7.3 | 6.8 | — |
| CAPEX | 6.6 | 6.3 | — |
| JPY/USD | 149.8 | 152.2 | — |
| JPY/EURO | 169.5 | 164.4 | — |
From Q1 FY2025 the company reclassified field service-related expenses (such as repairs and delivery at customer sites) from selling, general and administrative expenses to cost of sales, and applied the change retrospectively to the prior year by reclassifying JPY 2,120MM from SG&A to cost of sales.
On the balance sheet, total assets stood at JPY 185.2 Bn at FY2025 year-end versus JPY 177.5 Bn a year earlier, with total equity of JPY 88.3 Bn (FY2024 year-end: JPY 81.7 Bn) and an equity ratio of 47.7% (46.1%). Interest-bearing debt was JPY 62.1 Bn (JPY 61.6 Bn) and Net Debt / Adjusted EBITDA was 1.7x (1.4x). Operating cash flow was JPY 9.3 Bn versus JPY 14.6 Bn in FY2024, and free cash flow was JPY 2.7 Bn versus JPY 8.5 Bn.
Segment Results
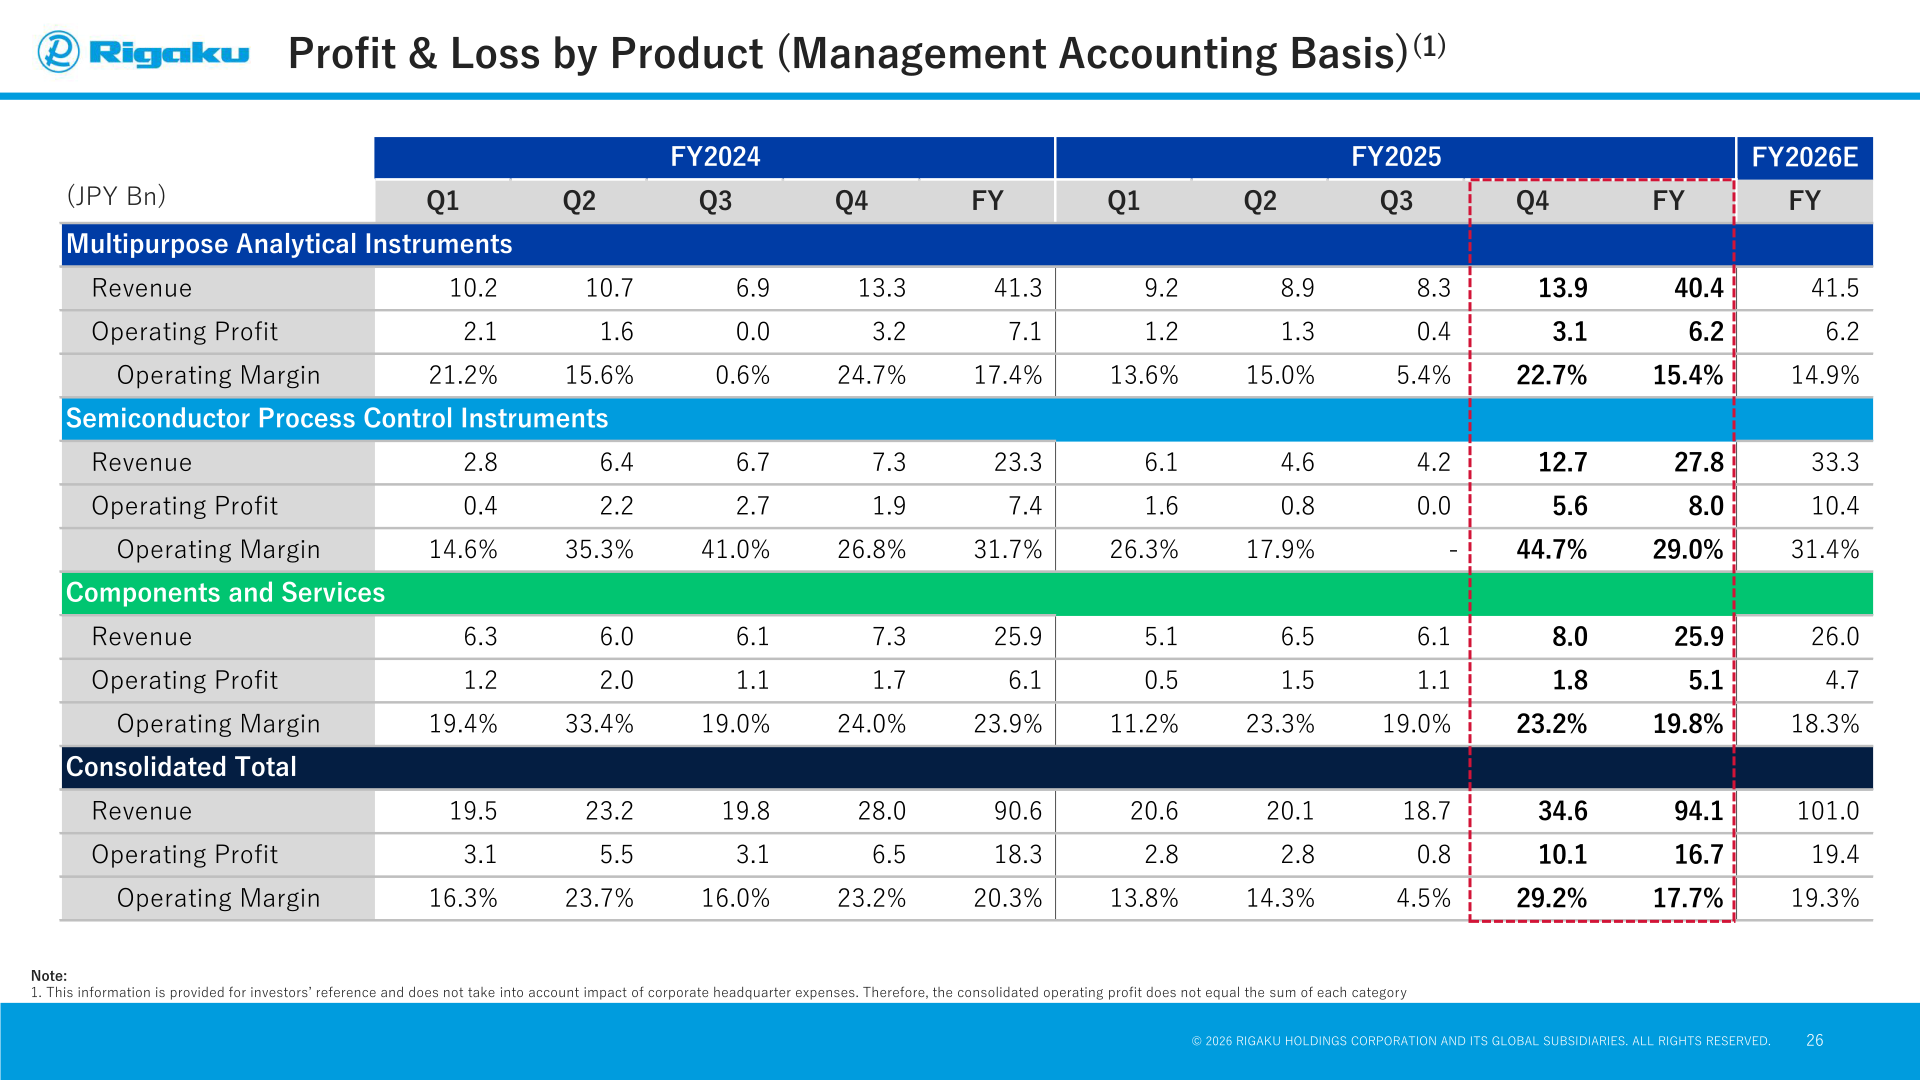
Rigaku presents profit and loss by product on a management accounting basis. Semiconductor Process Control Instruments grew revenue +19% YoY to JPY 27.8 Bn by capturing the demand shift from mass production to advanced technology development, and maintained a 29.0% operating margin despite product and regional mix effects. Multipurpose Analytical Instruments revenue was (2)% YoY at JPY 40.4 Bn, with growth in Europe (+27% YoY) and Japan (+3% YoY for the full year, +41% YoY in Q4 October–December) offsetting declines in the Americas ((13)% YoY, on academia budget cuts) and China ((23)% YoY, on the absence of China supplementary budget projects). Components and Services revenue was flat YoY at JPY 25.9 Bn, or +4% excluding EUV multilayer mirrors, with service revenue up +8% YoY.
| Segment (Management Accounting Basis, JPY Bn) | Metric | FY2025 | FY2024 |
|---|---|---|---|
| Multipurpose Analytical Instruments | Revenue | 40.4 | 41.3 |
| Multipurpose Analytical Instruments | Operating Profit | 6.2 | 7.1 |
| Multipurpose Analytical Instruments | Operating Margin | 15.4% | 17.4% |
| Semiconductor Process Control Instruments | Revenue | 27.8 | 23.3 |
| Semiconductor Process Control Instruments | Operating Profit | 8.0 | 7.4 |
| Semiconductor Process Control Instruments | Operating Margin | 29.0% | 31.7% |
| Components and Services | Revenue | 25.9 | 25.9 |
| Components and Services | Operating Profit | 5.1 | 6.1 |
| Components and Services | Operating Margin | 19.8% | 23.9% |
| Consolidated Total | Revenue | 94.1 | 90.6 |
| Consolidated Total | Operating Profit | 16.7 | 18.3 |
| Consolidated Total | Operating Margin | 17.7% | 20.3% |
The materials note that this product-level information is provided for investors’ reference and does not take into account the impact of corporate headquarter expenses, so consolidated operating profit does not equal the sum of each category.
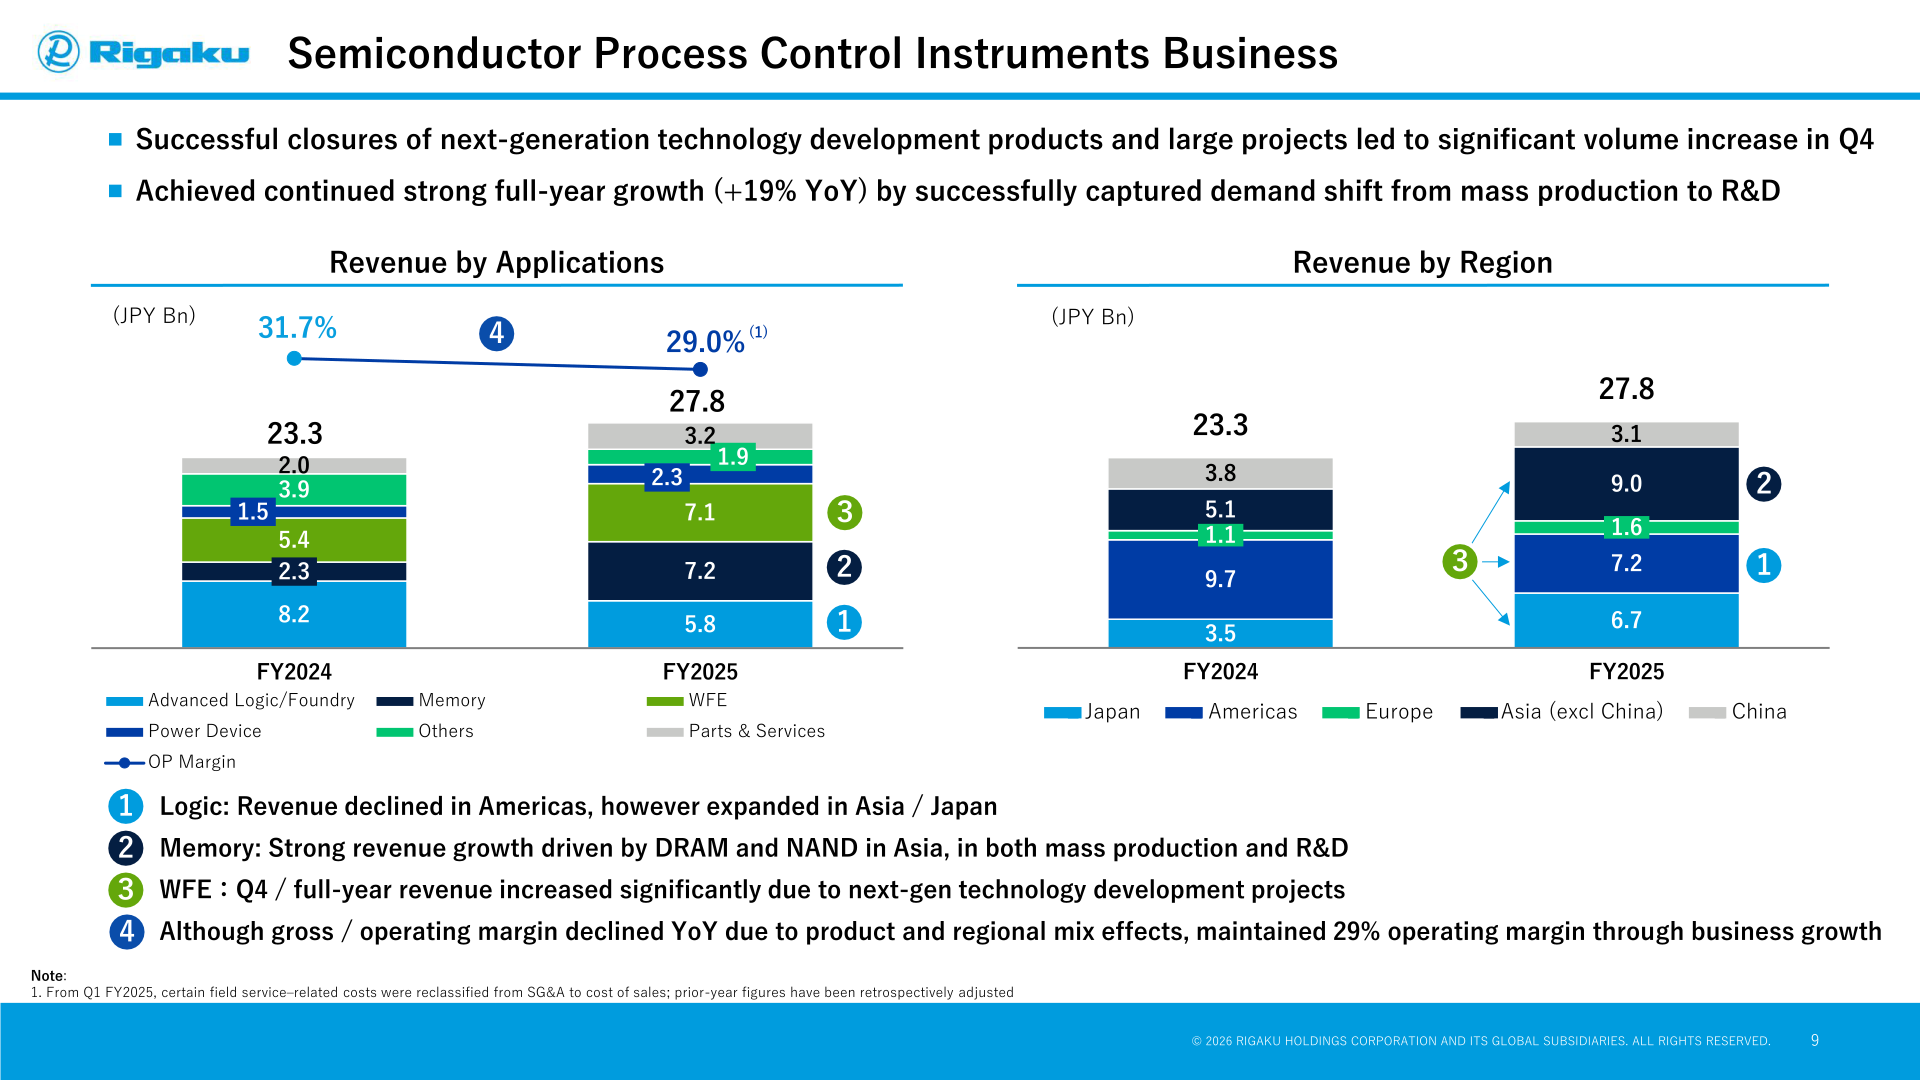
Within Semiconductor Process Control Instruments, memory delivered strong revenue growth driven by DRAM and NAND in Asia in both mass production and R&D, while logic revenue declined in the Americas but expanded in Asia and Japan. WFE-related revenue increased significantly in Q4 and for the full year on next-generation technology development projects. By region, this business grew to JPY 6.7 Bn in Japan (FY2024: JPY 3.5 Bn), JPY 9.0 Bn in Asia excluding China (JPY 5.1 Bn) and JPY 1.6 Bn in Europe (JPY 1.1 Bn), while the Americas declined to JPY 7.2 Bn (JPY 9.7 Bn) and China to JPY 3.1 Bn (JPY 3.8 Bn).
In Components and Services, revenue from EUV multilayer mirrors declined by JPY (1) Bn on weak demand; excluding EUV, revenue increased by JPY 0.3 Bn as higher sales of other analytical instruments (thermal analysis, PCI and portable Raman spectroscopy) offset a decline in component sales resulting from a strategic shift. Services continued to grow on price increases, expanded global maintenance contracts and a growing installed base, while the segment margin declined on unfavorable product mix from lower EUV sales and a reduced service margin affected by U.S. policy changes.
On a consolidated basis, FY2025 revenue by region was Japan JPY 27.4 Bn (FY2024: JPY 24.3 Bn), Americas JPY 23.4 Bn (JPY 27.7 Bn), EMEA JPY 13.8 Bn (JPY 11.0 Bn), Asia excluding China JPY 16.8 Bn (JPY 12.4 Bn) and China JPY 12.5 Bn (JPY 15.0 Bn). By end market, Semiconductor / Electronic Components was JPY 33.3 Bn (JPY 32.4 Bn), Academia / Governments JPY 24.8 Bn (JPY 23.9 Bn), Other Industries JPY 15.7 Bn (JPY 16.4 Bn), Services JPY 15.1 Bn (JPY 13.5 Bn) and Life Science JPY 5.0 Bn (JPY 4.3 Bn).
Adjusted EBITDA Bridge
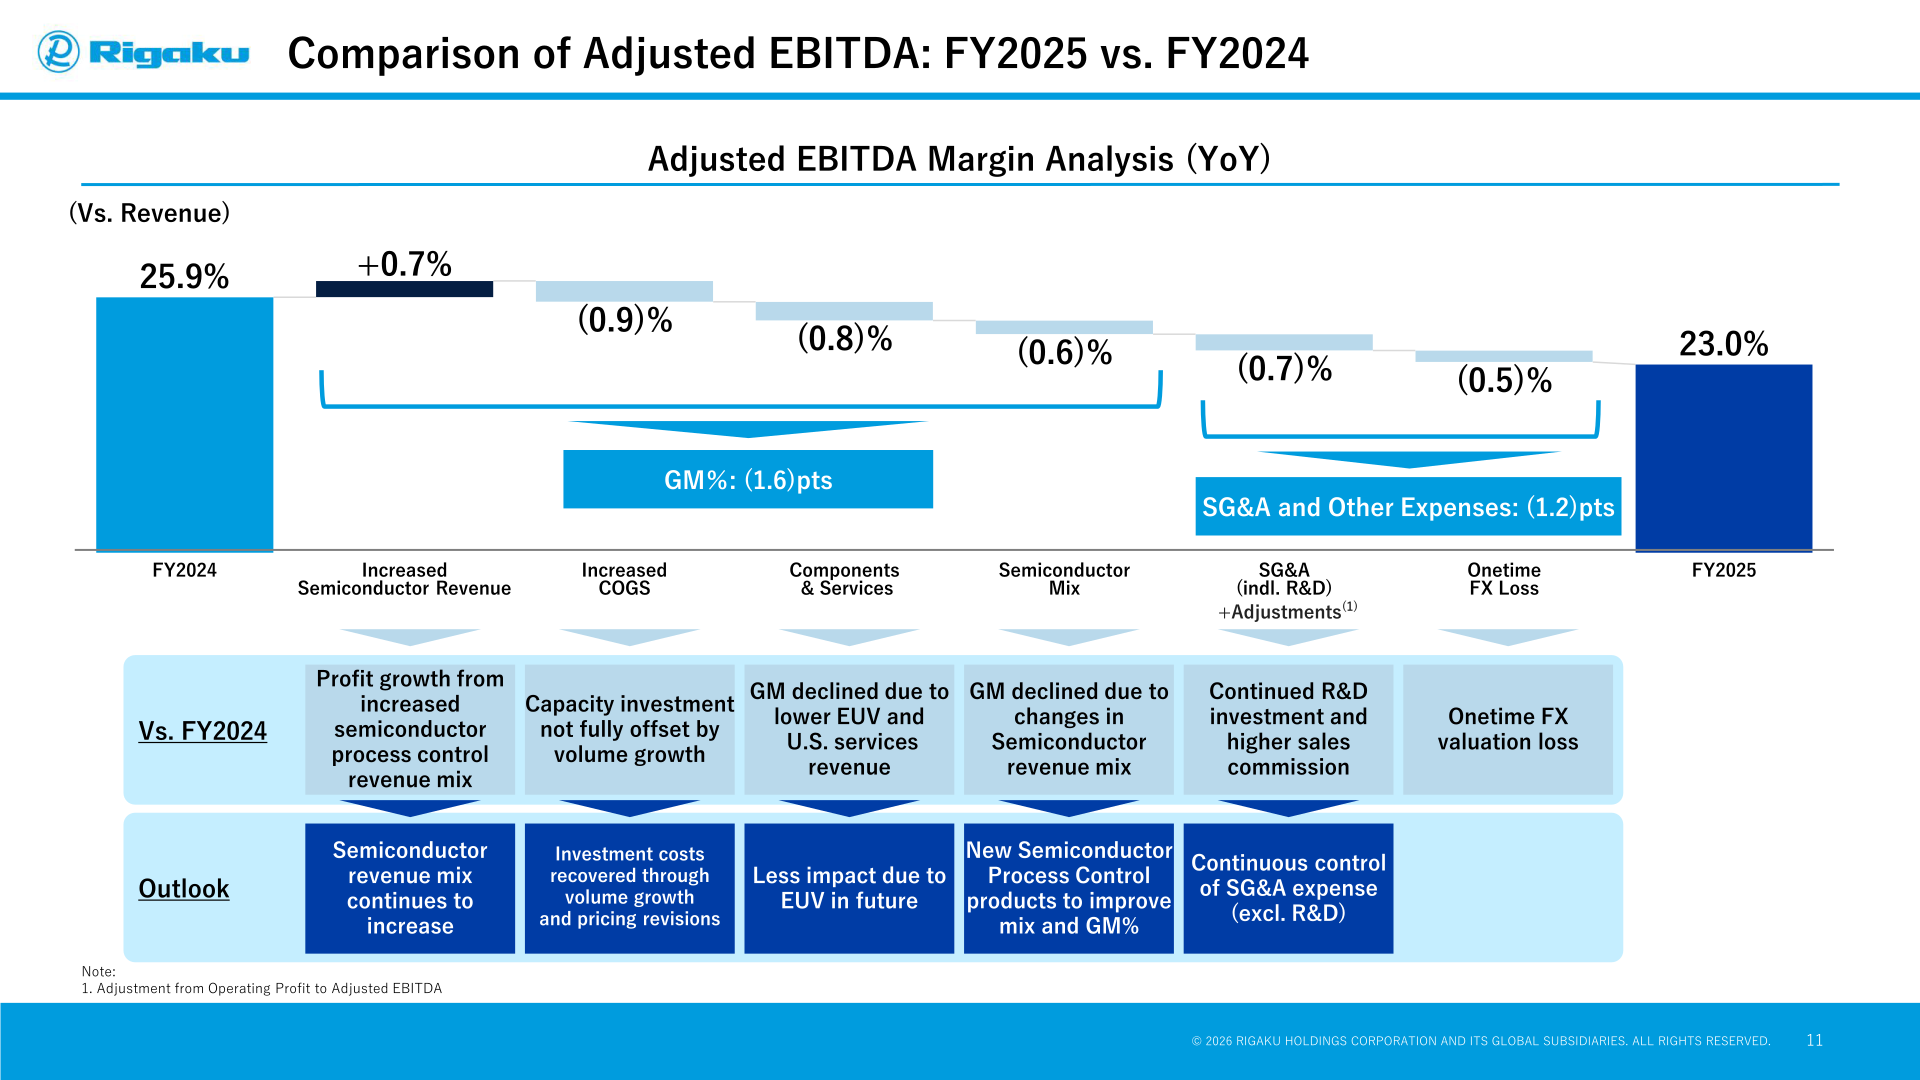
The company’s Adjusted EBITDA margin analysis versus revenue shows the FY2024 margin of 25.9% moving to 23.0% in FY2025 through the following steps: Increased Semiconductor Revenue +0.7%, Increased COGS (0.9)%, Components & Services (0.8)%, Semiconductor Mix (0.6)%, SG&A (incl. R&D) plus adjustments (0.7)% and Onetime FX Loss (0.5)%. Grouped, gross margin accounted for (1.6) pts and SG&A and other expenses for (1.2) pts. Against the FY2025 forecast margin of 24.5%, the actual 23.0% reflected Increased Semiconductor Revenue +0.1%, Increased COGS (1.2)%, Pricing / Product Mix (0.9)%, SG&A (incl. R&D) plus adjustments +1.0% and Onetime FX Losses (0.4)%.
FY2026 Forecast
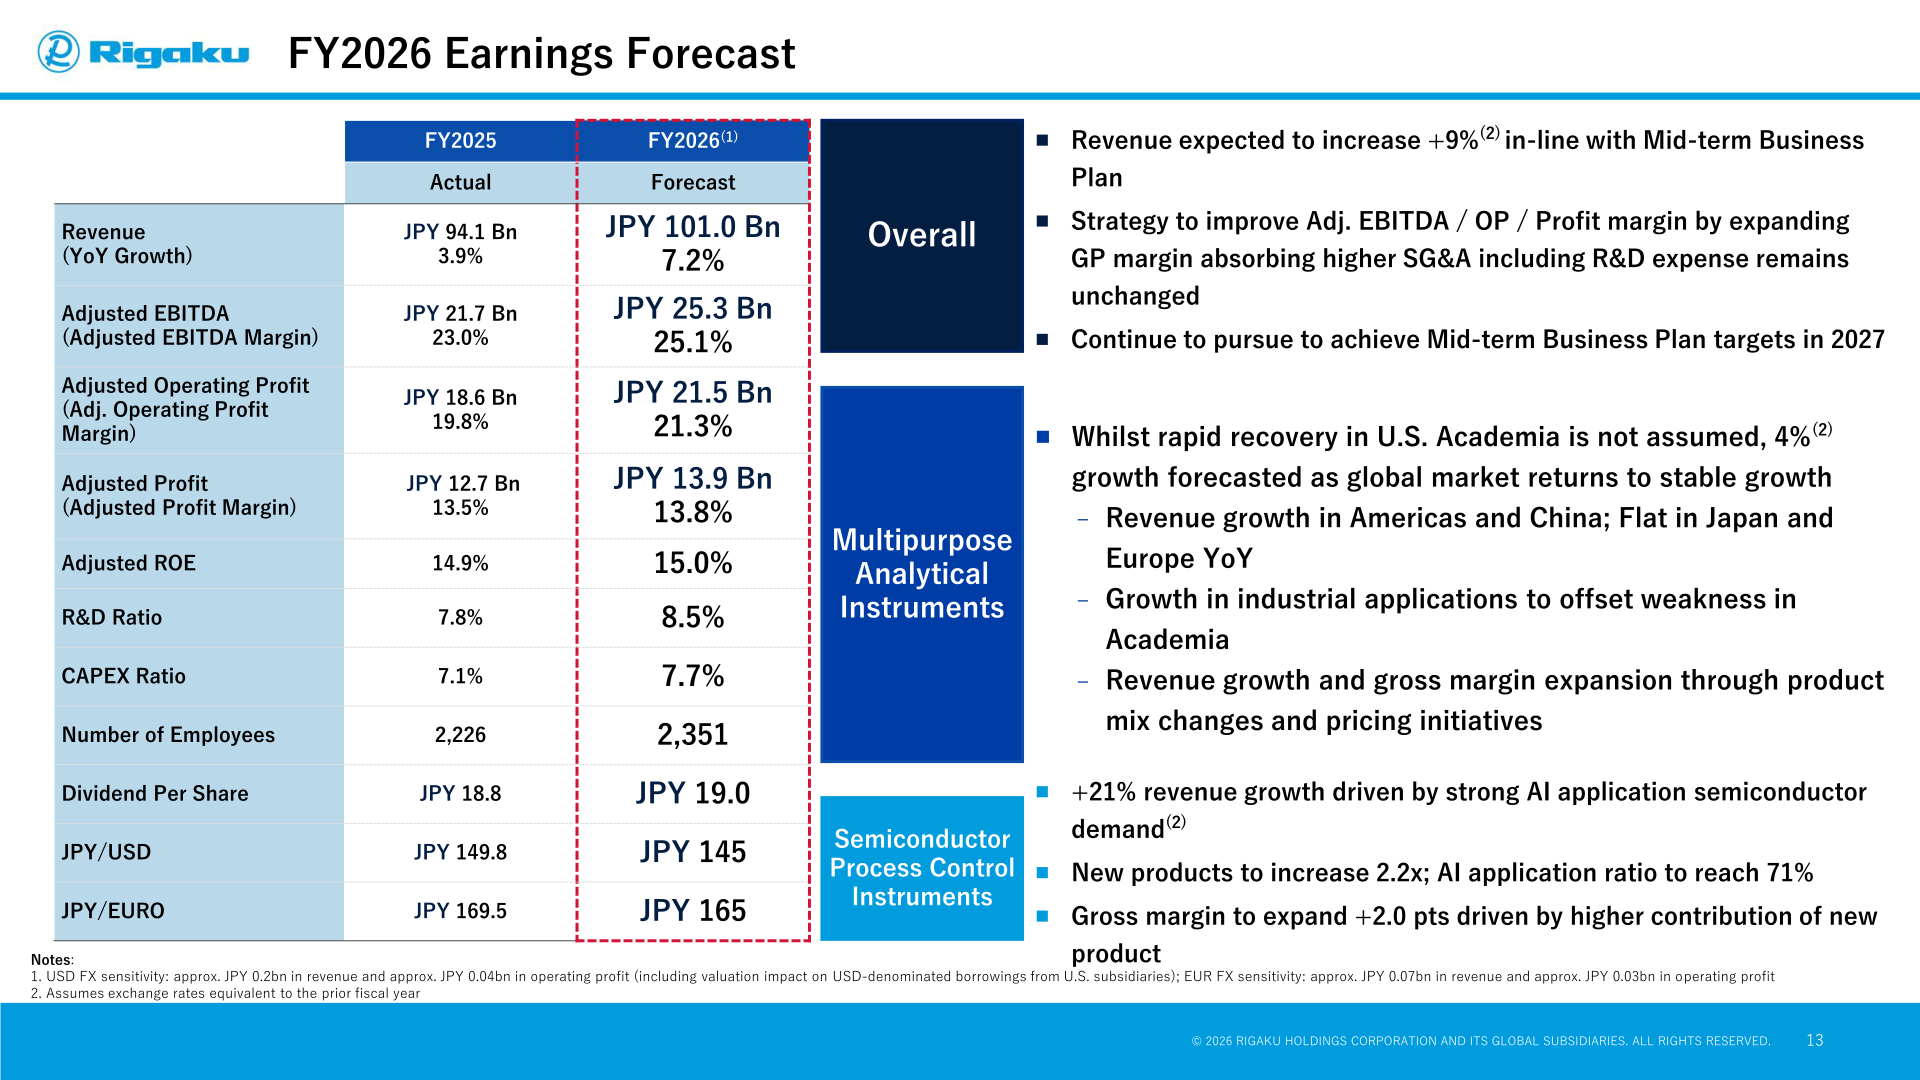
For FY2026 the company forecasts revenue of JPY 101.0 Bn (+7.2%) with Adjusted EBITDA of JPY 25.3 Bn (margin 25.1%), Adjusted Operating Profit of JPY 21.5 Bn (margin 21.3%) and Adjusted Profit of JPY 13.9 Bn (margin 13.8%). On a prior-year exchange rate basis the company describes revenue as expected to increase +9%, in line with its Mid-term Business Plan, and states that it will continue to pursue the plan’s 2027 targets. Semiconductor Process Control Instruments is guided to +21% revenue growth on strong AI application semiconductor demand, with new product revenue increasing 2.2x and the AI application ratio reaching 71%; Multipurpose Analytical Instruments is guided to +4% growth, with the company noting that a rapid recovery in U.S. academia is not assumed.
| Item | FY2026 Forecast | FY2025 (Actual) |
|---|---|---|
| Revenue | JPY 101.0 Bn | JPY 94.1 Bn |
| (YoY Growth) | 7.2% | 3.9% |
| Adjusted EBITDA | JPY 25.3 Bn | JPY 21.7 Bn |
| (Adjusted EBITDA Margin) | 25.1% | 23.0% |
| Adjusted Operating Profit | JPY 21.5 Bn | JPY 18.6 Bn |
| (Adj. Operating Profit Margin) | 21.3% | 19.8% |
| Adjusted Profit | JPY 13.9 Bn | JPY 12.7 Bn |
| (Adjusted Profit Margin) | 13.8% | 13.5% |
| Adjusted ROE | 15.0% | 14.9% |
| R&D Ratio | 8.5% | 7.8% |
| CAPEX Ratio | 7.7% | 7.1% |
| Number of Employees | 2,351 | 2,226 |
| Dividend Per Share | JPY 19.0 | JPY 18.8 |
| JPY/USD | JPY 145 | JPY 149.8 |
| JPY/EURO | JPY 165 | JPY 169.5 |
By product, the FY2026 forecast on a management accounting basis is revenue of JPY 33.3 Bn and operating profit of JPY 10.4 Bn (margin 31.4%) for Semiconductor Process Control Instruments, JPY 41.5 Bn and JPY 6.2 Bn (14.9%) for Multipurpose Analytical Instruments, and JPY 26.0 Bn and JPY 4.7 Bn (18.3%) for Components and Services, with a consolidated total of JPY 101.0 Bn revenue and JPY 19.4 Bn operating profit (19.3%). On the IFRS basis the company forecasts gross profit of JPY 58.9 Bn, profit before taxes of JPY 18.4 Bn, profit of JPY 12.5 Bn and EPS of JPY 55.27. The Adjusted EBITDA margin is expected to improve from 23.0% to 25.1% via Increased Semiconductor Revenue +0.6%, Increased COGS (0.6)%, Pricing / Product Mix +2.3%, SG&A (incl. R&D) plus adjustments (0.9)% and Onetime FX Losses +0.7%, with gross margin contributing +2.2 pts.
Shareholder Returns
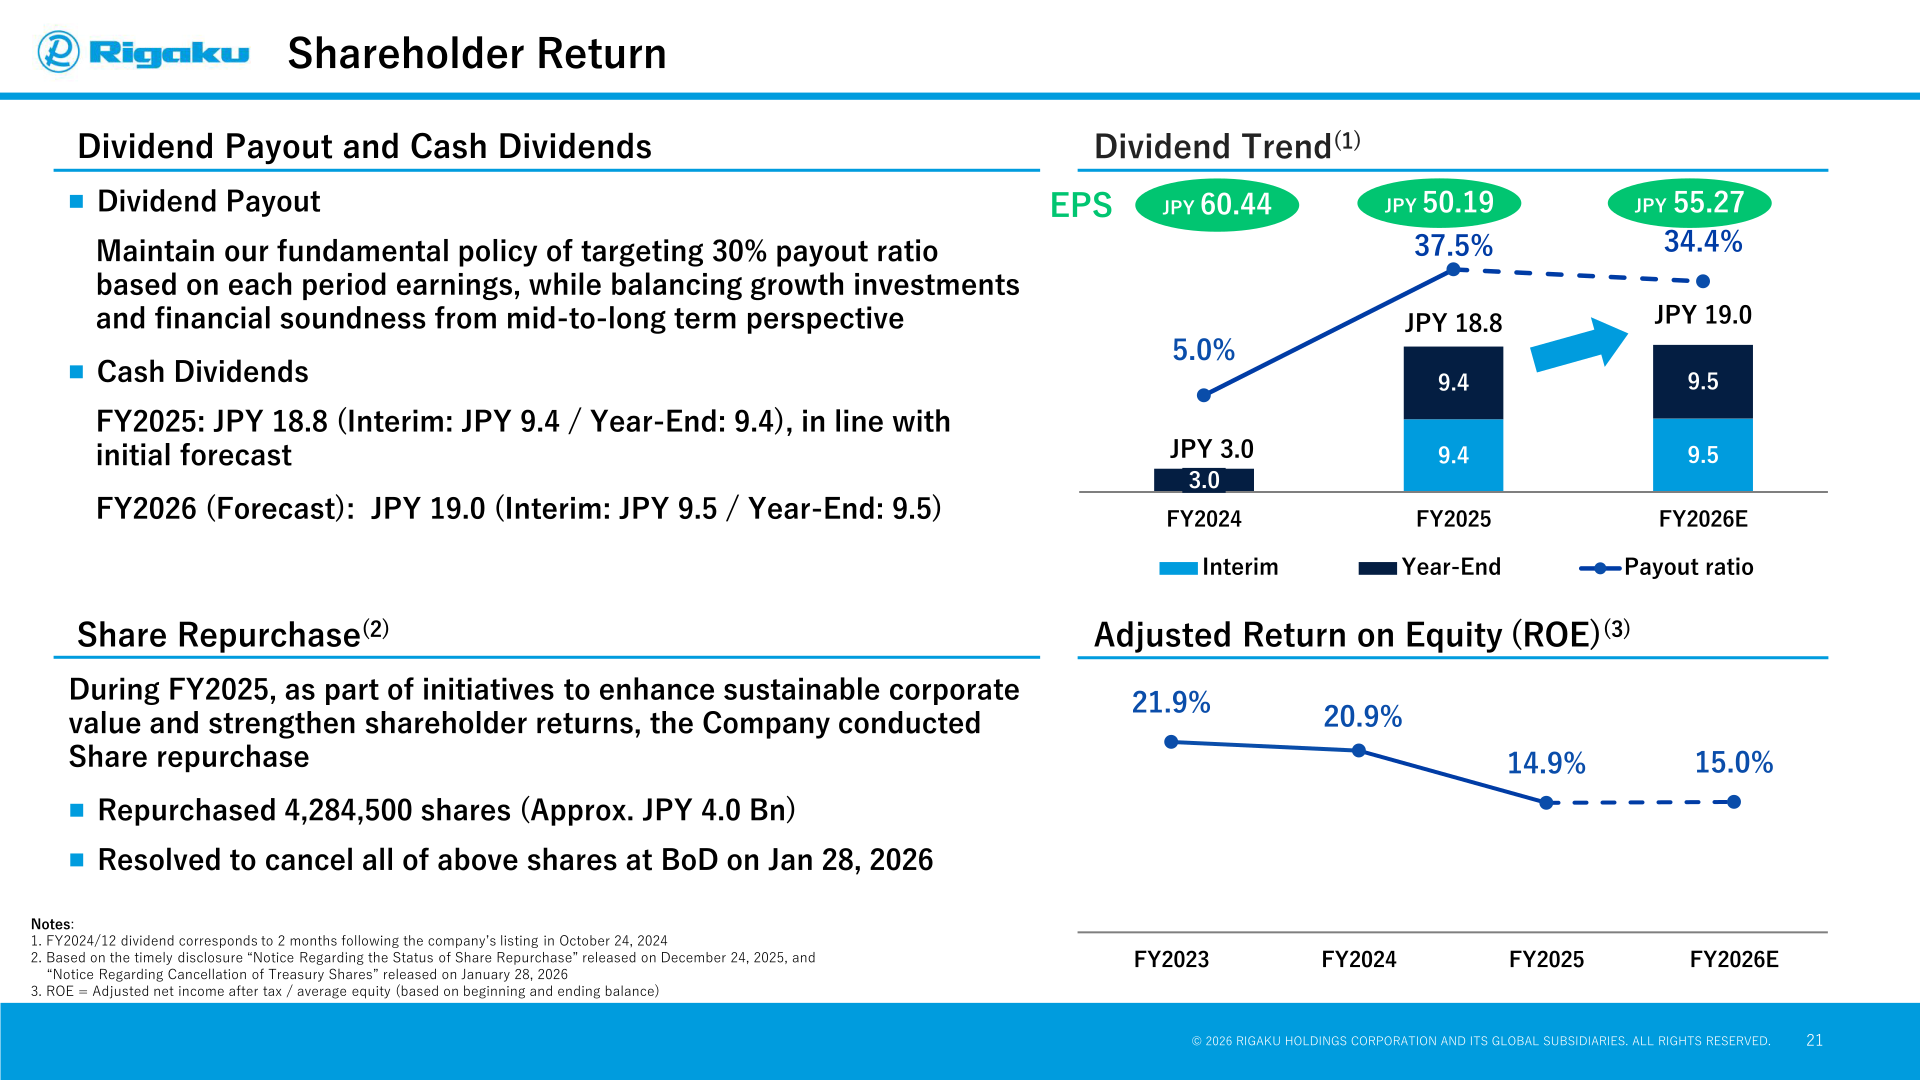
The company maintains its fundamental policy of targeting a 30% payout ratio based on each period’s earnings, while balancing growth investments and financial soundness from a mid-to-long term perspective. The FY2025 dividend was JPY 18.8 per share (interim JPY 9.4, year-end JPY 9.4), in line with the initial forecast, and the FY2026 forecast dividend is JPY 19.0 per share (interim JPY 9.5, year-end JPY 9.5). During FY2025 the company repurchased 4,284,500 shares for approximately JPY 4.0 Bn as part of initiatives to enhance sustainable corporate value and strengthen shareholder returns, and resolved at the Board of Directors meeting on January 28, 2026 to cancel all of those shares.
| Item | FY2024 | FY2025 | FY2026 (Forecast) |
|---|---|---|---|
| Interim Dividend Per Share | — | JPY 9.4 | JPY 9.5 |
| Year-End Dividend Per Share | — | JPY 9.4 | JPY 9.5 |
| Annual Dividend Per Share | JPY 3.0 | JPY 18.8 | JPY 19.0 |
| Payout Ratio | 5.0% | 37.5% | 34.4% |
| EPS | JPY 60.44 | JPY 50.19 | JPY 55.27 |
| Adjusted ROE | 20.9% | 14.9% | 15.0% |
The materials note that the FY2024 dividend corresponds to the two months following the company’s listing on October 24, 2024. Adjusted ROE is defined as adjusted net income after tax divided by average equity based on beginning and ending balances, and was 21.9% in FY2023.
Business Strategy and Topics
In Semiconductor Process Control Instruments the company is targeting AI-driven capacity expansion investment in 2nm logic and HBM / 3D NAND memory ramp-ups, as well as next-generation semiconductor R&D investment in sub-1nm logic, next-generation memory including 3D DRAM, and advanced packaging. Products announced or shipped include the ONYX 3200 (light-element capability, with the new X-ray beam module COLORS-t W Mα shipped to two advanced logic customers in 2026), XTRAIA CD-3200T (adopted by major memory and WFE customers), XTRAIA MF-3400 (XRF/XRD multifunction GEN4) and XTRAIA XD-3300, while XTRAIA CD-3300T (T-SAXS) for 3D DRAM and XTRAIA CD-3200G (low-energy GI-SAXS) are under development. The company reports 14 Joint Evaluation Program projects with 12 currently running, and 5 projects completed during FY2025. It estimates a total SAM of approximately $1.0 Bn for these advanced metrology needs at 2030, with a target share of over 50%, and a JPY 100 Bn revenue target at 2030 including existing products.
For Multipurpose Analytical Instruments in FY2026, the company expects to continue gaining overseas market share driven by the demand shift toward industrial applications and strong material informatics demand, with overseas revenue up +6% on a prior-year exchange rate basis. It expects the Americas to return to the FY2024 level and China to return to a growth phase, a resource shift toward industrial applications such as Semiconductor and Electronic Components to offset weaker academia demand, and gross margin to improve by 1.8 pts from FY2025 on pricing actions and improved product mix, while operating profit declines slightly on continued investment in overseas commercial infrastructure and R&D. Quarterly revenue is expected to start moderately in Q1, reach the prior-year level in H1 and accelerate to +14% YoY growth in H2, with Q4 again the peak quarter.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















