
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: This site classifies the most recent completed fiscal year as FY2025; the company labels the same period the fiscal year ended March 31, 2026 (FY3/2026), and the labels used in the text and tables below follow the source materials. Note: TOBISHIMA HOLDINGS does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported.
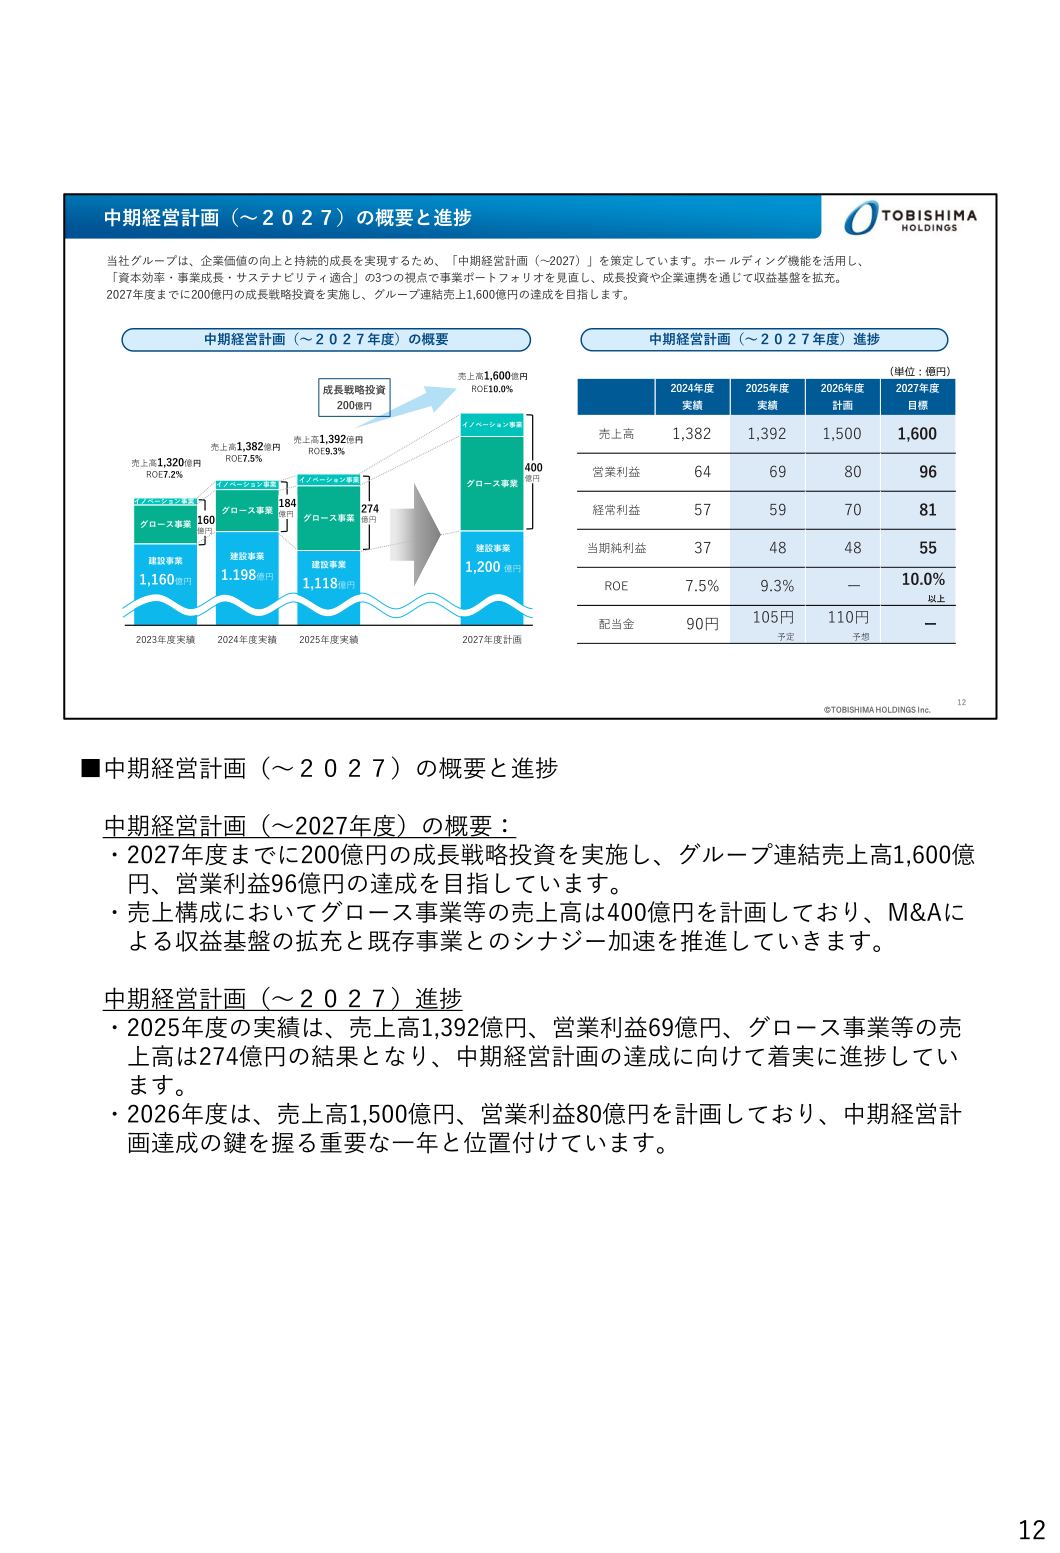
In the fiscal year ended March 2026, TOBISHIMA HOLDINGS posted higher sales and higher profit year on year, as the building construction business and the growth businesses performed solidly. Net sales declined in the civil engineering business due to delays in starting some projects, but rose overall year on year on the expansion of the growth businesses. In addition to profit improvement from profitability-focused order taking and cost management, the expansion of the earnings base through an increase in group companies via M&A and improved capital efficiency from a review of assets held lifted both operating profit and net income year on year. For the fiscal year ending March 2027, the company plans net sales of 150.0 billion yen, operating profit of 8.0 billion yen and net income of 4.8 billion yen.
Consolidated Results (Full-Year Actual)
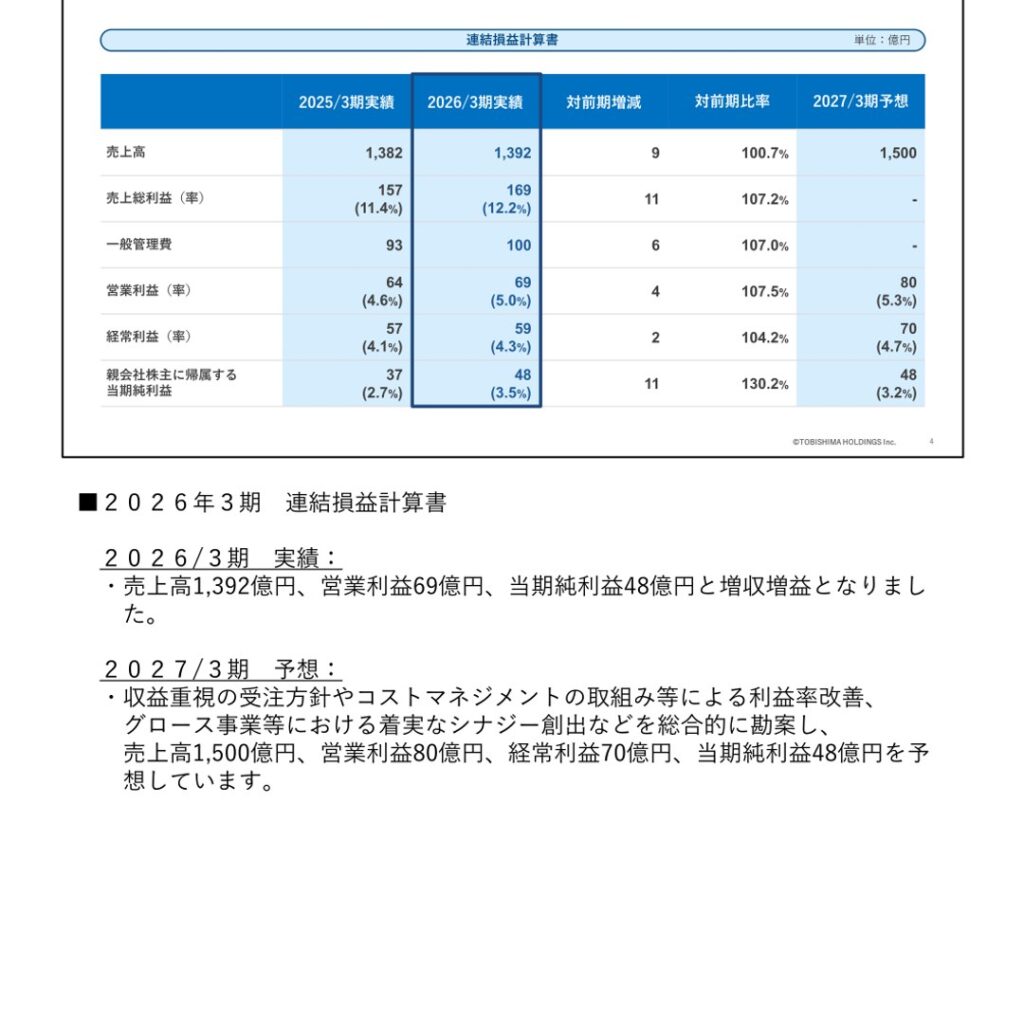
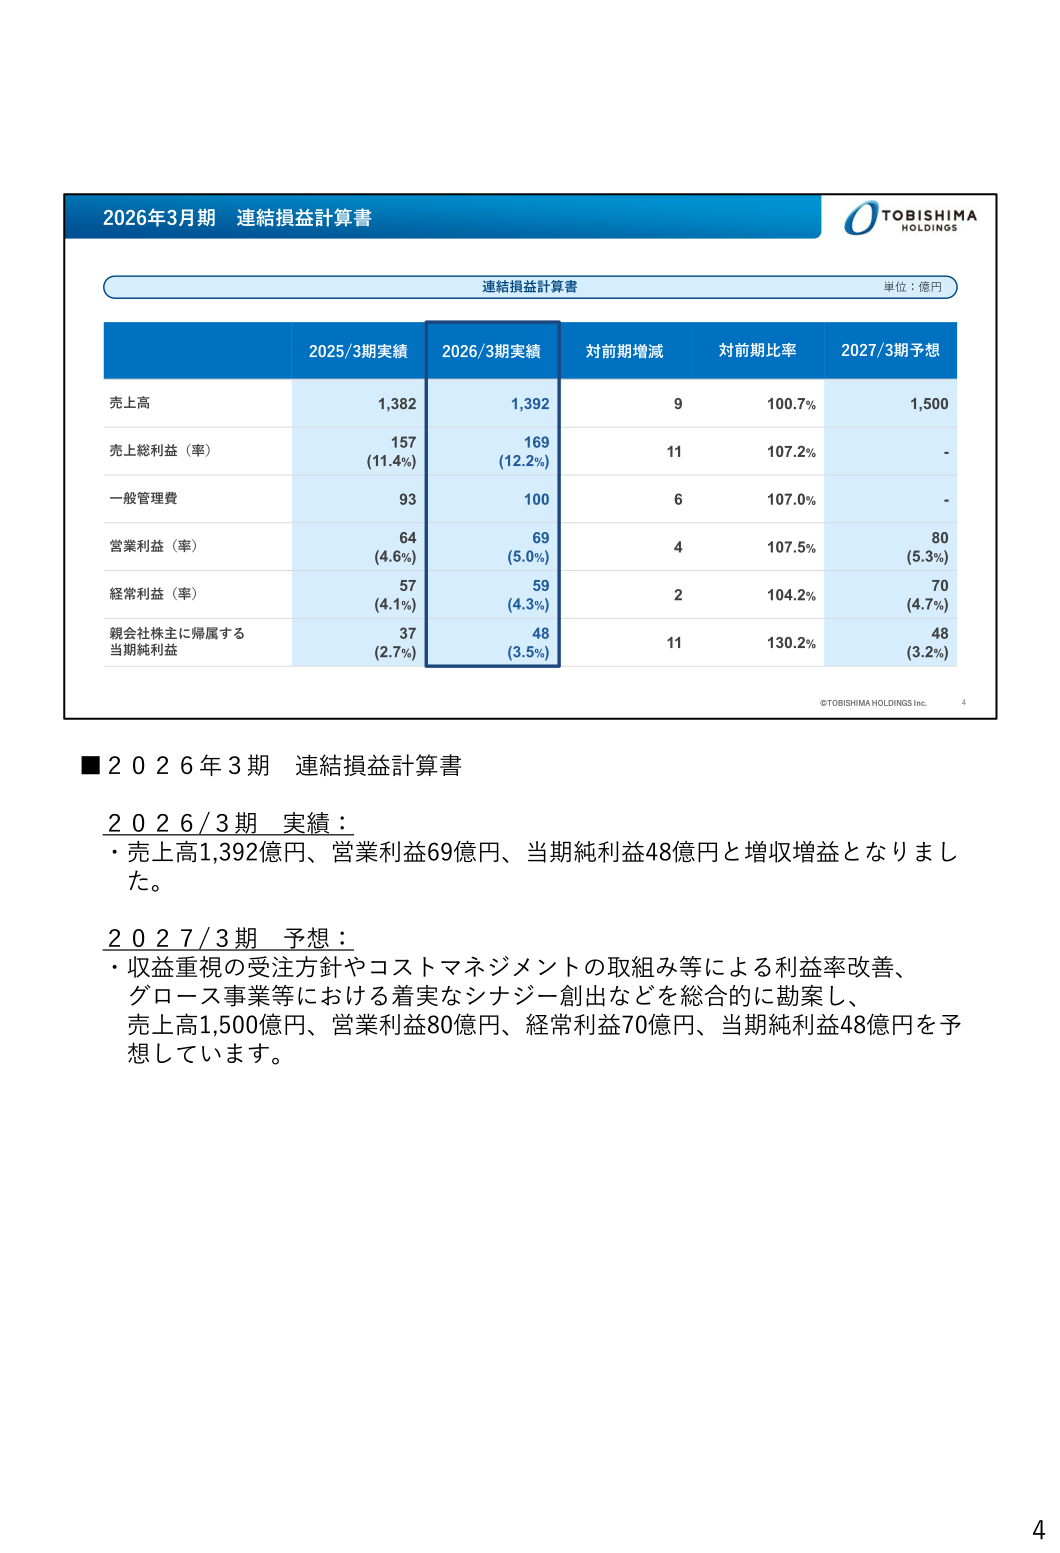
According to the consolidated statement of income, for the fiscal year ended March 2026 net sales were 139.2 billion yen (up 0.9 billion yen, or 0.7%, year on year), gross profit was 16.9 billion yen (up 1.1 billion yen, or 7.2%, with a gross profit margin of 12.2%), general and administrative expenses were 10.0 billion yen (up 0.6 billion yen, or 7.0%), operating profit was 6.9 billion yen (up 0.4 billion yen, or 7.5%, with an operating margin of 5.0%), ordinary profit was 5.9 billion yen (up 0.2 billion yen, or 4.2%, with an ordinary profit margin of 4.3%), and profit attributable to owners of parent was 4.8 billion yen (up 1.1 billion yen, or 30.2%, with a net profit margin of 3.5%).
| Item | Previous FY (FY3/2025) Actual | Current FY (FY3/2026) Actual | Change |
|---|---|---|---|
| Net sales | 138.2 billion yen | 139.2 billion yen | +0.9 billion yen |
| Gross profit (margin) | 15.7 billion yen (11.4%) | 16.9 billion yen (12.2%) | +1.1 billion yen |
| General and administrative expenses | 9.3 billion yen | 10.0 billion yen | +0.6 billion yen |
| Operating profit (margin) | 6.4 billion yen (4.6%) | 6.9 billion yen (5.0%) | +0.4 billion yen |
| Ordinary profit (margin) | 5.7 billion yen (4.1%) | 5.9 billion yen (4.3%) | +0.2 billion yen |
| Profit attributable to owners of parent (margin) | 3.7 billion yen (2.7%) | 4.8 billion yen (3.5%) | +1.1 billion yen |
Segment Results
Looking at the drivers of the change in consolidated net sales (P.5), sales rose 1.0 billion yen from 138.2 billion yen in the previous fiscal year to 139.2 billion yen. The construction business (civil engineering) decreased by 8.4 billion yen due to delays in discussions with clients and other factors, the construction business (building construction) increased by 0.4 billion yen on solid construction progress, and the growth businesses increased by 9.0 billion yen on an increase in group companies through M&A and higher real estate sales. In the drivers of the change in operating profit (P.6), profit rose 0.5 billion yen from 6.4 billion yen in the previous fiscal year to 6.9 billion yen. The civil engineering business decreased by 1.4 billion yen due to the impact of delays in discussions (down 1.0 billion yen) and delayed progress on high-margin new projects (down 0.4 billion yen); the building construction business increased by 1.3 billion yen on selective order taking and cost management; and the growth businesses increased by 1.2 billion yen on an increase in group companies through M&A and solid business progress at each company, while selling, general and administrative expenses increased by 0.6 billion yen, mainly on higher expenses associated with M&A.
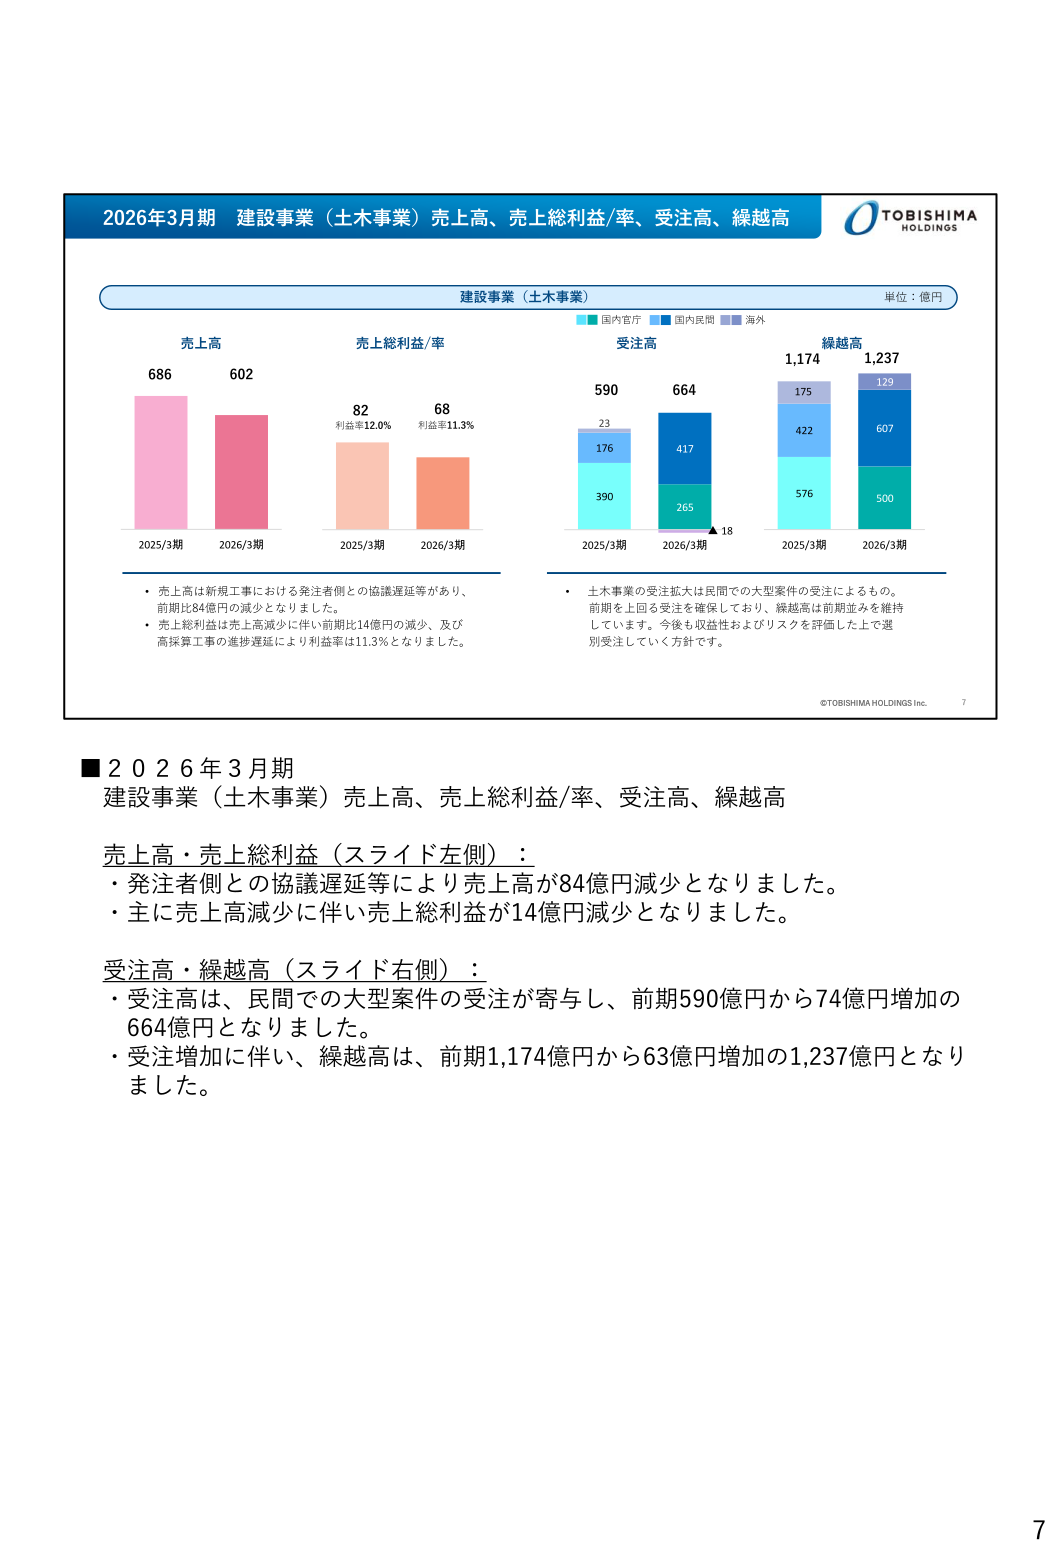
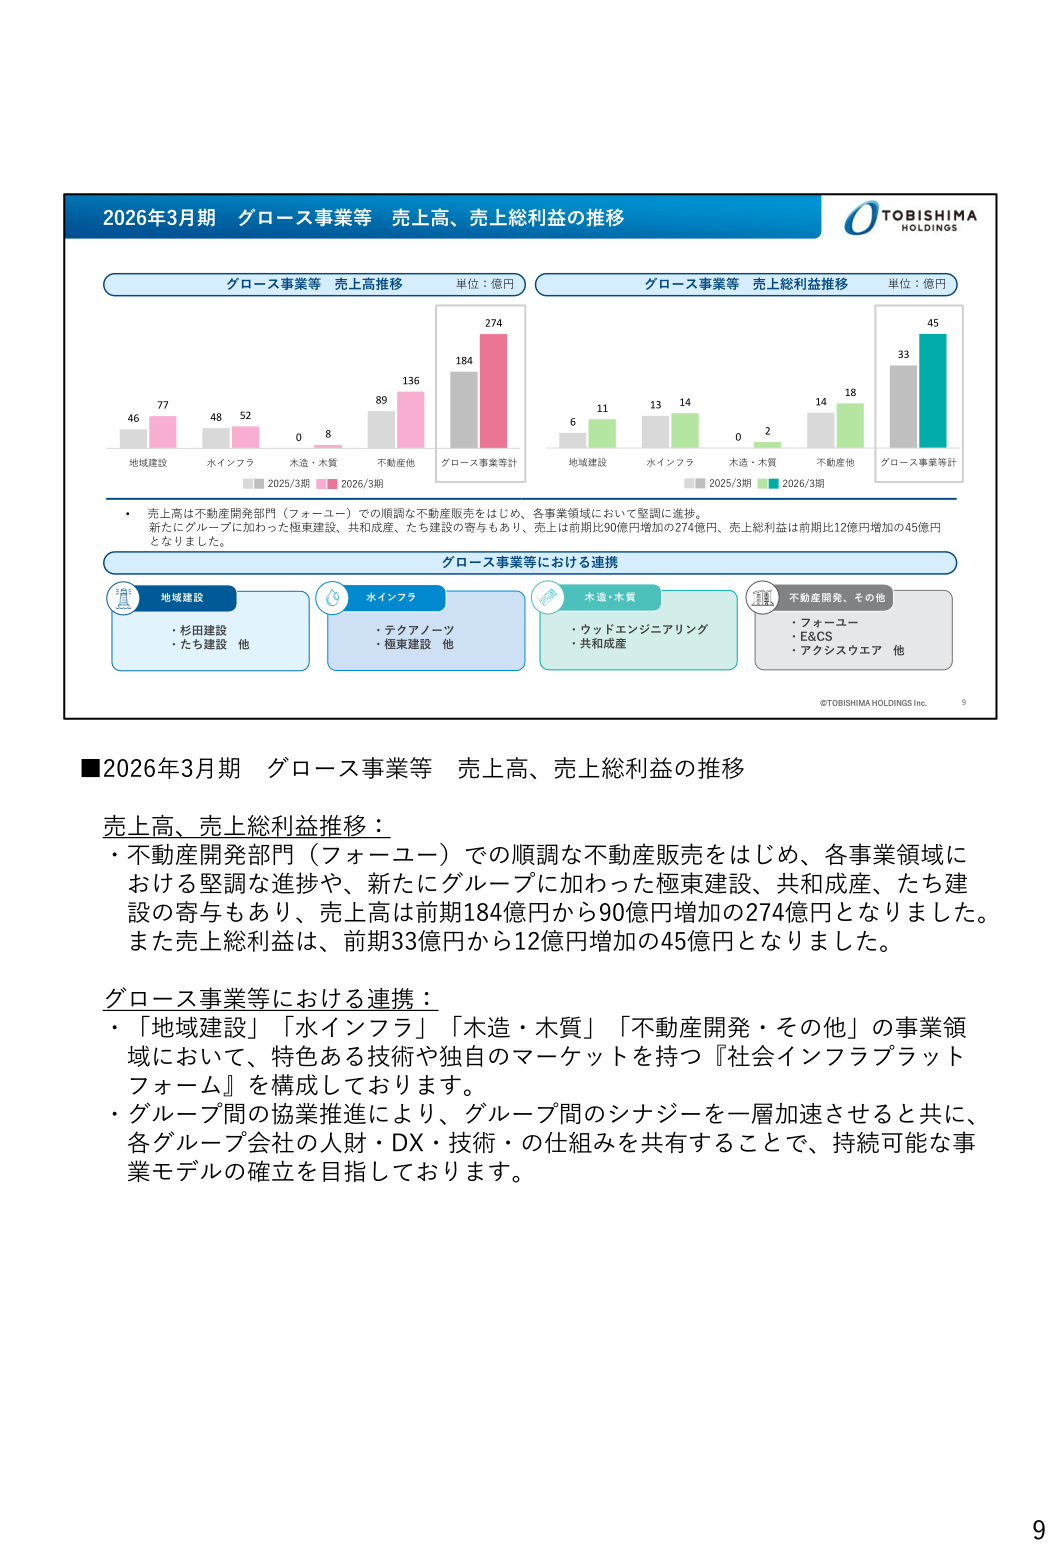
In the construction business (civil engineering), net sales were 60.2 billion yen (68.6 billion yen in the previous fiscal year) and gross profit was 6.8 billion yen (8.2 billion yen, a margin of 11.3%), reflecting delays in discussions with clients. Orders received rose from 59.0 billion yen in the previous fiscal year to 66.4 billion yen on the receipt of large private-sector projects, and the order backlog also rose from 117.4 billion yen to 123.7 billion yen. In the construction business (building construction), net sales were 51.5 billion yen (51.1 billion yen in the previous fiscal year) and gross profit was 5.5 billion yen (4.2 billion yen, a margin of 10.8%), for higher sales and profit. Orders received fell from 54.8 billion yen in the previous fiscal year to 46.0 billion yen on selective order taking emphasizing profitability, and the order backlog also declined from 74.3 billion yen to 69.1 billion yen, although the company describes it as a sufficient level in light of its construction capacity. In the growth businesses, supported by steady real estate sales at the real estate development unit (For You) and contributions from newly added group companies Kyokuto Construction, KYOWA SEISAN and Tachi Construction, net sales rose 9.0 billion yen from 18.4 billion yen in the previous fiscal year to 27.4 billion yen, and gross profit rose 1.2 billion yen from 3.3 billion yen to 4.5 billion yen.
| Business | Metric | Previous FY (FY3/2025) | Current FY (FY3/2026) |
|---|---|---|---|
| Construction business (civil engineering) | Net sales | 68.6 billion yen | 60.2 billion yen |
| Construction business (civil engineering) | Gross profit (margin) | 8.2 billion yen (12.0%) | 6.8 billion yen (11.3%) |
| Construction business (civil engineering) | Orders received | 59.0 billion yen | 66.4 billion yen |
| Construction business (civil engineering) | Order backlog | 117.4 billion yen | 123.7 billion yen |
| Construction business (building construction) | Net sales | 51.1 billion yen | 51.5 billion yen |
| Construction business (building construction) | Gross profit (margin) | 4.2 billion yen (8.3%) | 5.5 billion yen (10.8%) |
| Construction business (building construction) | Orders received | 54.8 billion yen | 46.0 billion yen |
| Construction business (building construction) | Order backlog | 74.3 billion yen | 69.1 billion yen |
| Growth businesses | Net sales | 18.4 billion yen | 27.4 billion yen |
| Growth businesses | Gross profit | 3.3 billion yen | 4.5 billion yen |
Full-Year Forecast
For the fiscal year ending March 2027, taking into account margin improvement from the profitability-focused order policy and cost management initiatives as well as the steady creation of synergies in the growth businesses, the company forecasts net sales of 150.0 billion yen, operating profit of 8.0 billion yen, ordinary profit of 7.0 billion yen and net income of 4.8 billion yen.
| Item | FY3/2027 Forecast | FY3/2026 (Actual) |
|---|---|---|
| Net sales | 150.0 billion yen | 139.2 billion yen |
| Operating profit | 8.0 billion yen | 6.9 billion yen |
| Ordinary profit | 7.0 billion yen | 5.9 billion yen |
| Net income | 4.8 billion yen | 4.8 billion yen |
Shareholder Returns
The dividend is planned at 105 yen for the fiscal year ended March 2026 against 90 yen for the fiscal year ended March 2025, and is forecast at 110 yen for the fiscal year ending March 2027. The company’s basic policy on shareholder returns is stable returns using DOE as an indicator, balanced against growth investment to raise corporate value and financial soundness. DOE was 2.9% in fiscal 2023, 3.5% in fiscal 2024 and 3.8% (planned) in fiscal 2025, and the company targets 4.0% or more in fiscal 2027.
| Item | FY3/2025 | FY3/2026 | FY3/2027 Forecast |
|---|---|---|---|
| Dividend | 90 yen | 105 yen (planned) | 110 yen (forecast) |
Medium-Term Management Plan / Topics
Under the Medium-Term Management Plan (through 2027), and guided by the medium- to long-term management vision “A Story to Innovate the Future” adopted on the occasion of the shift to a holding company structure, the group is transforming itself into a “platform company” that keeps the construction business (civil engineering and building construction) at its core while linking it with the growth businesses. The company aims to carry out 20.0 billion yen of growth strategy investment by fiscal 2027 and to achieve consolidated group net sales of 160.0 billion yen, operating profit of 9.6 billion yen and ROE of 10% or more. The fiscal 2025 result was ROE of 9.3% (7.5% in the previous fiscal year), and the company states that progress toward the targets is steady.
To expand its earnings base, the company brought the Tachi Construction group, based in Shiga Prefecture, into the group in January 2026, and also added wooden building materials maker KYOWA SEISAN. On governance, outside directors account for 62% of the board and female directors for 37%. The company has also built a group-wide personnel system, with an advance rollout starting at Tobishima Corporation in April 2026 and full operation planned from April 2027, and has established the “Tobishima Group R&D Platform,” which integrates research and development functions across the group.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















