
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
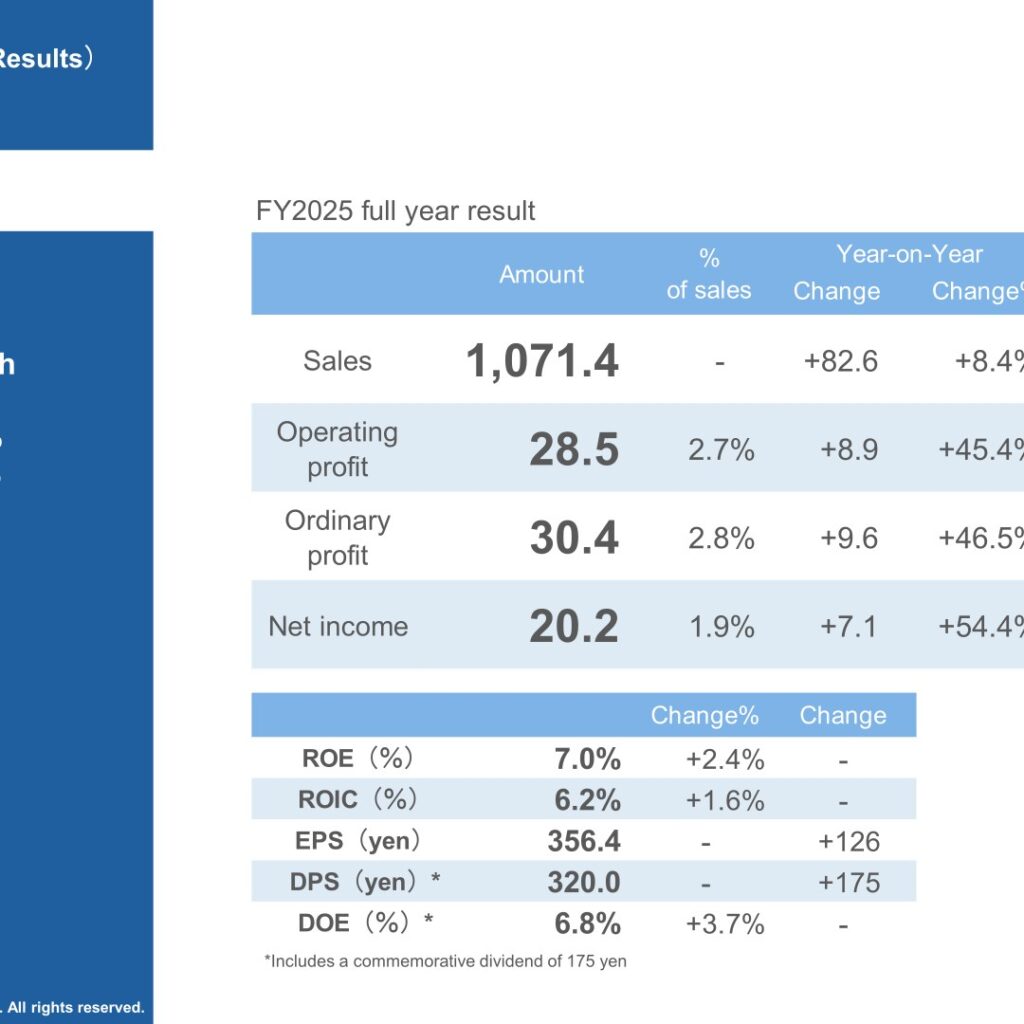
ITOHAM YONEKYU HOLDINGS INC. (TSE Prime: 2296) reported revenue and profit growth for FY2025 (Apr 1, 2025 – Mar 31, 2026), with sales of JPY1,071.4 billion (+8.4% year on year) and ordinary profit of JPY30.4 billion (+46.5%). The company states that it achieved its Mid-Term Plan targets one year early, with ordinary profit of 30.4 billion yen, ROE of 7.0% and ROIC of 6.2% against targets of ordinary profit 30.0 billion yen, ROE 6.2% and ROIC 5.9%. Growth was driven by the Meat Division, where both the domestic and overseas businesses improved, while the Processed Food Division saw revenue and profit decline. For FY2026 (Apr 1, 2026 – Mar 31, 2027) the company forecasts a decline in revenue and profit, with sales of JPY1,040.0 billion (-2.9%) and ordinary profit of JPY28.0 billion (-7.9%).
Consolidated Results (Full-Year Actual)
Sales rose JPY82.6 billion year on year to JPY1,071.4 billion, exceeding the February 5 revised forecast of JPY1,050.0 billion by JPY21.4 billion. Operating profit was JPY28.5 billion (2.7% of sales, +45.4%), ordinary profit JPY30.4 billion (2.8% of sales, +46.5%) and net income JPY20.2 billion (1.9% of sales, +54.4%). All three profit lines also came in above the February 5 revised forecasts of JPY27.5 billion, JPY28.5 billion and JPY18.5 billion respectively. Gross profit was JPY146.5 billion (13.7% of sales) against JPY133.3 billion (13.5%) a year earlier, while SG&A expenses rose JPY4.3 billion to JPY118.0 billion but fell to 11.0% of sales from 11.5%. Extraordinary losses narrowed to JPY0.8 billion from JPY1.5 billion, and income before taxes was JPY29.6 billion.
| Item (billion yen) | FY2025 | FY2024 | YoY Change | YoY Change% |
|---|---|---|---|---|
| Sales | 1,071.4 | 988.8 | +82.6 | +8.4% |
| COGS | 924.9 | 855.5 | +69.4 | – |
| Gross Profit | 146.5 | 133.3 | +13.2 | – |
| Selling, General and Administrative Expenses | 118.0 | 113.7 | +4.3 | – |
| Operating profit | 28.5 | 19.6 | +8.9 | +45.4% |
| Ordinary profit | 30.4 | 20.8 | +9.6 | +46.5% |
| Income Before Taxes | 29.6 | 19.3 | +10.3 | – |
| Net Income | 20.2 | 13.1 | +7.1 | +54.4% |
By region, domestic sales were JPY858.7 billion (+18.9) and overseas sales JPY212.6 billion (+63.8), lifting the overseas ratio to 19.8% from 15.1%. Overseas sales comprised Asia JPY42.7 billion, North America JPY76.4 billion, Oceania JPY49.0 billion, Europe JPY38.8 billion and others JPY5.8 billion. On the balance sheet, total assets stood at JPY524.7 billion (+57.7 versus the previous fiscal year-end), net interest-bearing debt at JPY74.3 billion (+32.8), the net D/E ratio at 25.2% (+10.7) and shareholders’ equity at JPY294.7 billion (+9.2), with a capital-to-asset ratio of 56.2% (-5.0). Cash flow from operations was JPY13.7 billion, cash flow from investments JPY-26.0 billion and cash flow from financing JPY8.5 billion, leaving free cash flow at JPY-12.3 billion.
Segment Results
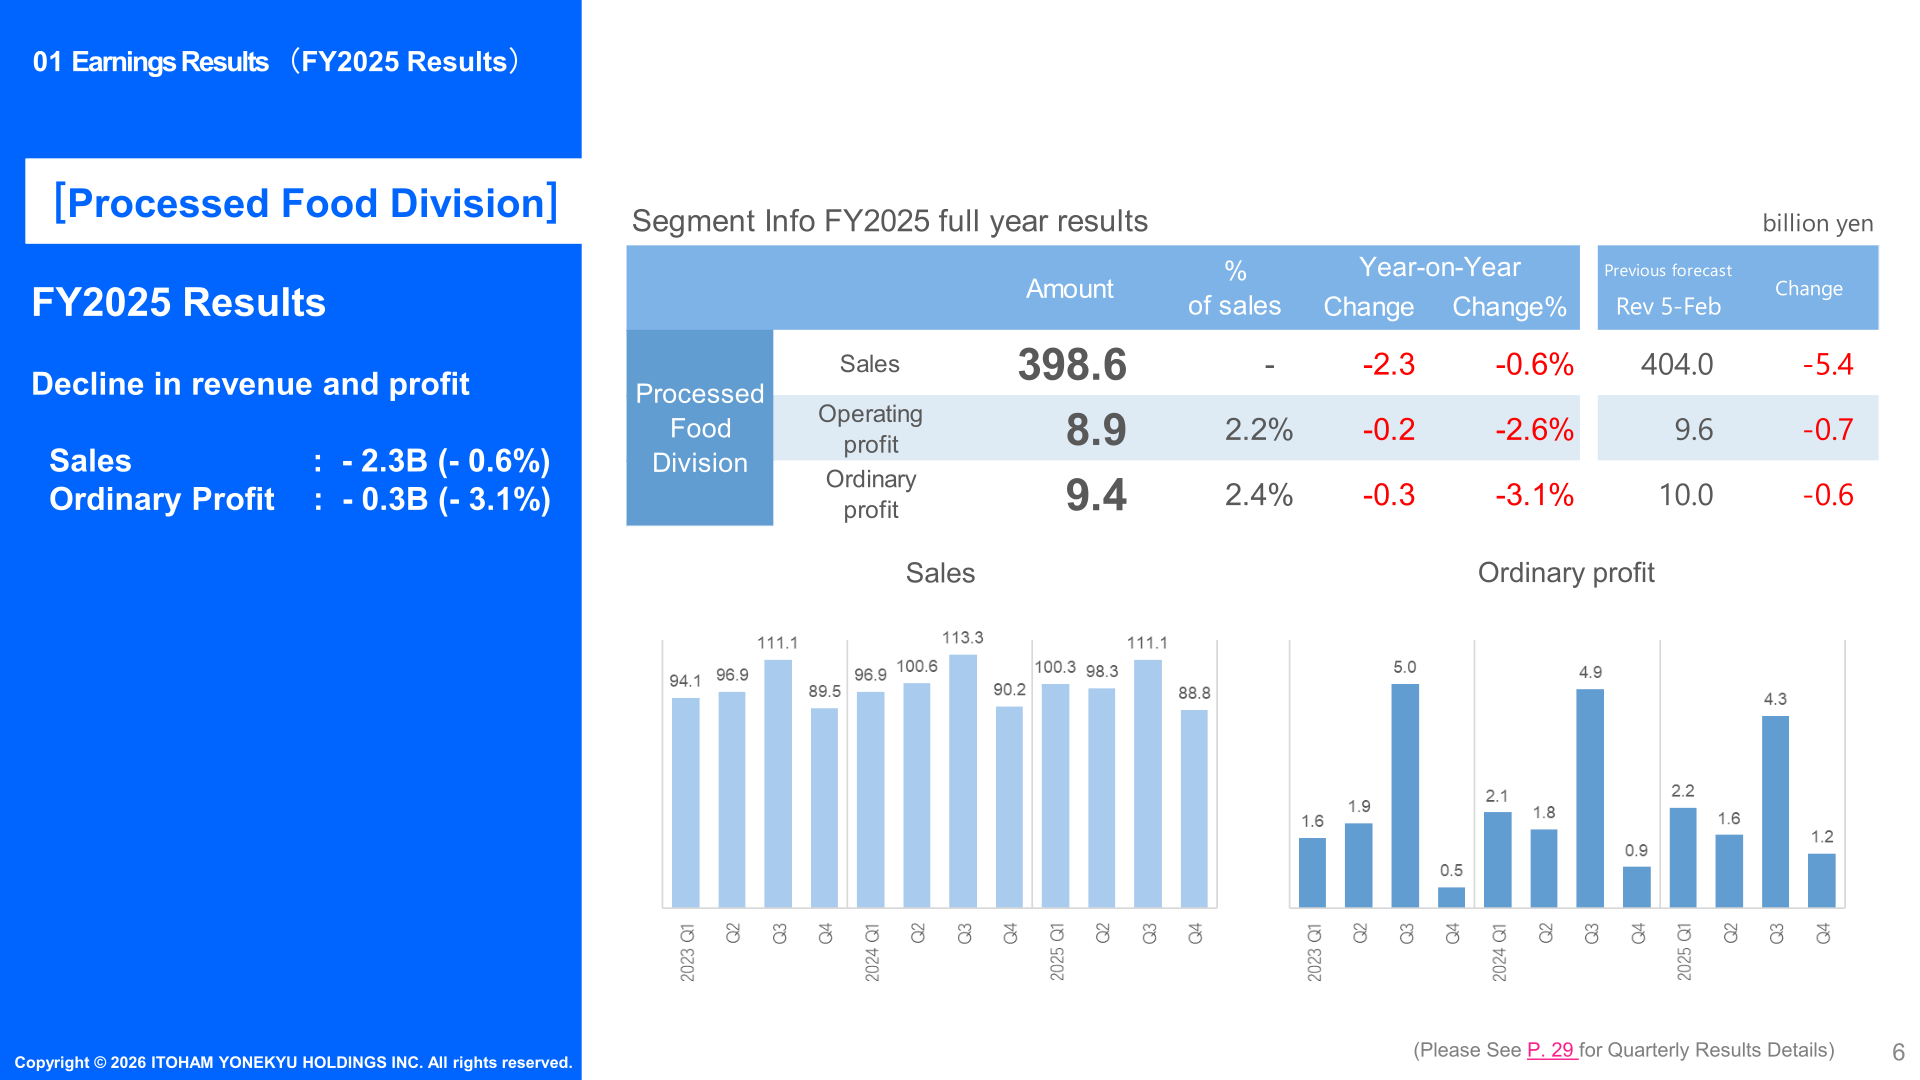
The Processed Food Division posted a decline in revenue and profit, with sales of JPY398.6 billion (-0.6%) and ordinary profit of JPY9.4 billion (-3.1%). The company attributes this to weak consumer demand and lower volumes, with higher raw material and logistics unit costs not fully offset by price revisions and product renewal. Ham and sausage sales volume fell 1.9% year on year (Q4: -1.1%) and processed food volume fell 4.0% (Q4: -3.8%), while winter gift item volume declined 6.1% by weight. Unit price improvements contributed JPY+3.8 billion in ham and sausage and JPY+2.6 billion in processed food, against raw material costs of JPY-3.1 billion and a logistics cost impact of JPY-1.9 billion for the year.
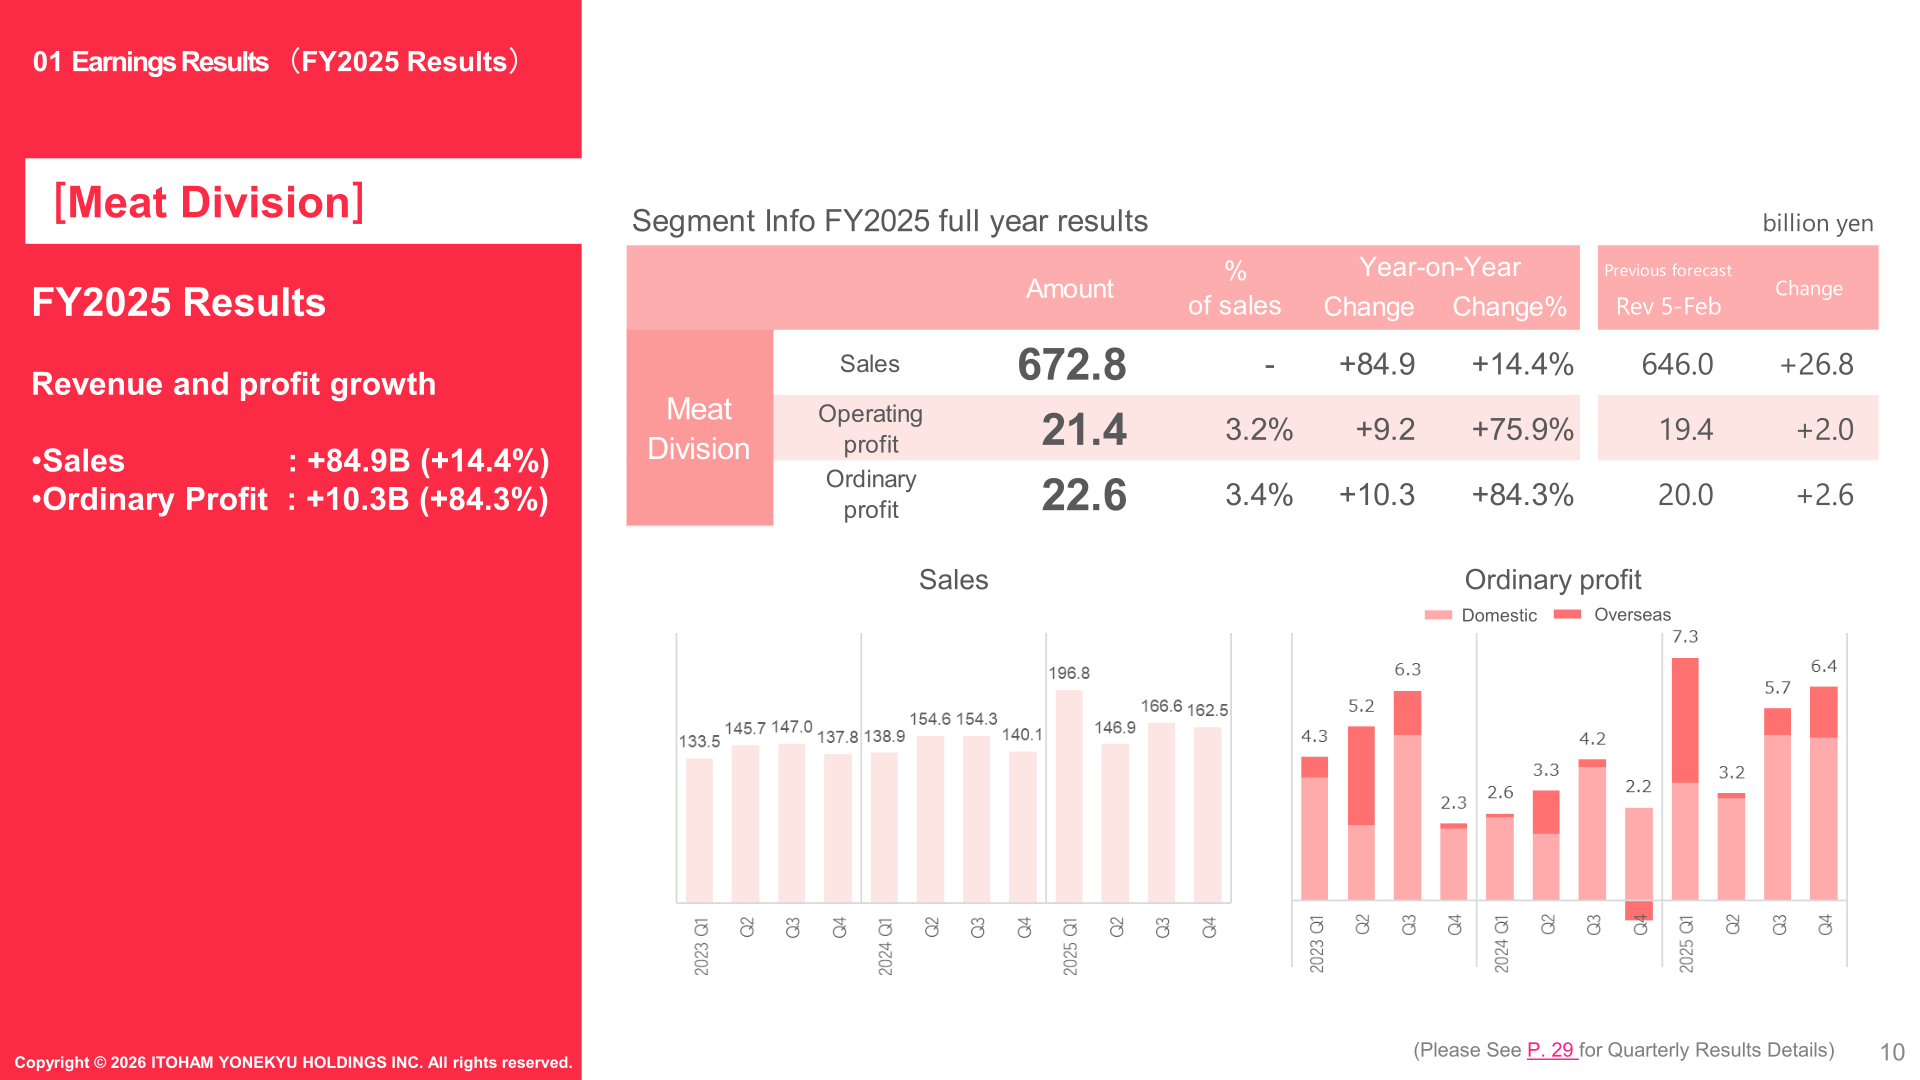
The Meat Division delivered revenue and profit growth, with sales of JPY672.8 billion (+14.4%) and ordinary profit of JPY22.6 billion (+84.3%). Profit rose in both the domestic and overseas businesses, driven by improved profitability in the domestic farming business and an earnings recovery at ANZCO. Domestic pork profitability improved through enhanced risk management, while imported chicken benefited from higher local prices and tighter domestic supply-demand; Tokyo wholesale prices rose JPY116/kg for thigh and JPY151/kg for breast on an April-March average. At ANZCO, earnings improved on higher beef export prices to North America and continued strong lamb sales to Europe and North America. A fiscal year change at ANZCO resulted in a 15-month reporting period (Jan 2025-Mar 2026), with an ordinary profit impact of JPY1.1 billion from the Jan-Mar 2025 portion. Within the full-year variance analysis, overseas operations contributed JPY+5.2 billion and market and feed prices (farm cost) JPY+2.6 billion.
| Segment | Metric (billion yen) | FY2025 | YoY Change | vs. Feb 5 Revised Forecast |
|---|---|---|---|---|
| Processed Food Division | Sales | 398.6 | -2.3 (-0.6%) | 404.0 (-5.4) |
| Processed Food Division | Operating profit | 8.9 | -0.2 (-2.6%) | 9.6 (-0.7) |
| Processed Food Division | Ordinary profit | 9.4 | -0.3 (-3.1%) | 10.0 (-0.6) |
| Meat Division | Sales | 672.8 | +84.9 (+14.4%) | 646.0 (+26.8) |
| Meat Division | Operating profit | 21.4 | +9.2 (+75.9%) | 19.4 (+2.0) |
| Meat Division | Ordinary profit | 22.6 | +10.3 (+84.3%) | 20.0 (+2.6) |
By product category, consolidated sales comprised ham and sausage JPY187.5 billion (-0.1), cooked foods JPY166.0 billion (+3.5), meat JPY682.9 billion (+74.2) and others JPY34.9 billion (+5.0). Within meat, beef was JPY313.3 billion (+31.4), pork JPY195.6 billion (+2.1), chicken JPY103.4 billion (+13.8) and lamb and others JPY70.7 billion (+27.0).
FY2026 Forecast
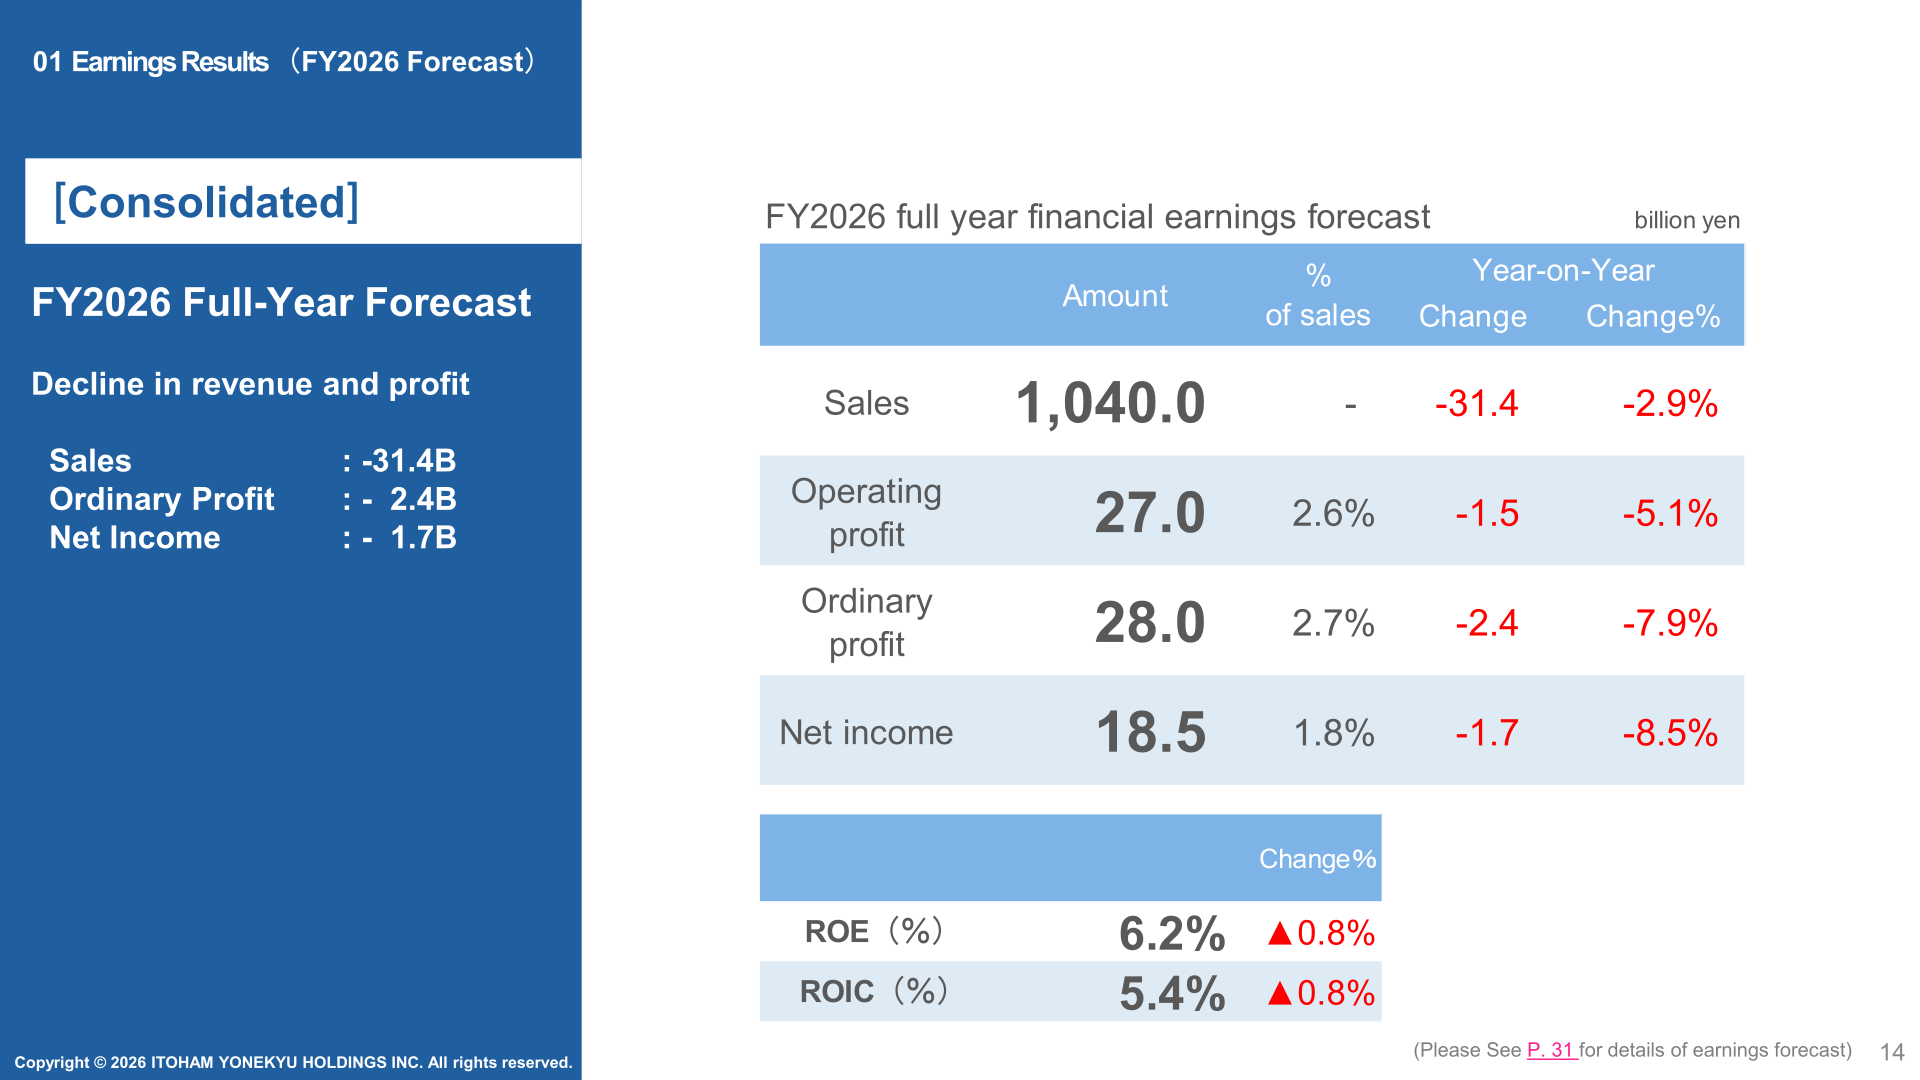
For FY2026 the company forecasts a decline in revenue and profit, guiding to sales of JPY1,040.0 billion (-31.4, -2.9%), operating profit of JPY27.0 billion (-5.1%), ordinary profit of JPY28.0 billion (-7.9%) and net income of JPY18.5 billion (-8.5%). ROE is forecast at 6.2% and ROIC at 5.4%. By segment, the Processed Food Division is expected to grow, with sales of JPY410.0 billion (+2.9%) and ordinary profit of JPY10.0 billion (+6.3%), as unit price improvements, consolidation of product specifications and accelerated product renewal are planned to cover rising raw material (JPY-4.9 billion), subsidiary material (JPY-3.5 billion), utility (JPY-0.7 billion) and charter freight costs. The Meat Division is forecast to decline, with sales of JPY630.0 billion (-6.4%) and ordinary profit of JPY19.5 billion (-13.8%), reflecting a pullback from last year’s strong imported chicken performance and a JPY-1.1 billion year-on-year impact from the prior-year ANZCO fiscal year change.
| Item (billion yen) | FY2026 Forecast | FY2025 (Actual) | YoY Change | YoY Change% |
|---|---|---|---|---|
| Sales | 1,040.0 | 1,071.4 | -31.4 | -2.9% |
| Operating profit | 27.0 | 28.5 | -1.5 | -5.1% |
| Ordinary profit | 28.0 | 30.4 | -2.4 | -7.9% |
| Net income | 18.5 | 20.2 | -1.7 | -8.5% |
| Processed Food Division: Sales | 410.0 | 398.6 | +11.4 | +2.9% |
| Processed Food Division: Ordinary profit | 10.0 | 9.4 | +0.6 | +6.3% |
| Meat Division: Sales | 630.0 | 672.8 | -42.8 | -6.4% |
| Meat Division: Ordinary profit | 19.5 | 22.6 | -3.1 | -13.8% |
| ROE | 6.2% | 7.0% | ▲0.8% | – |
| ROIC | 5.4% | 6.2% | ▲0.8% | – |
Shareholder Returns
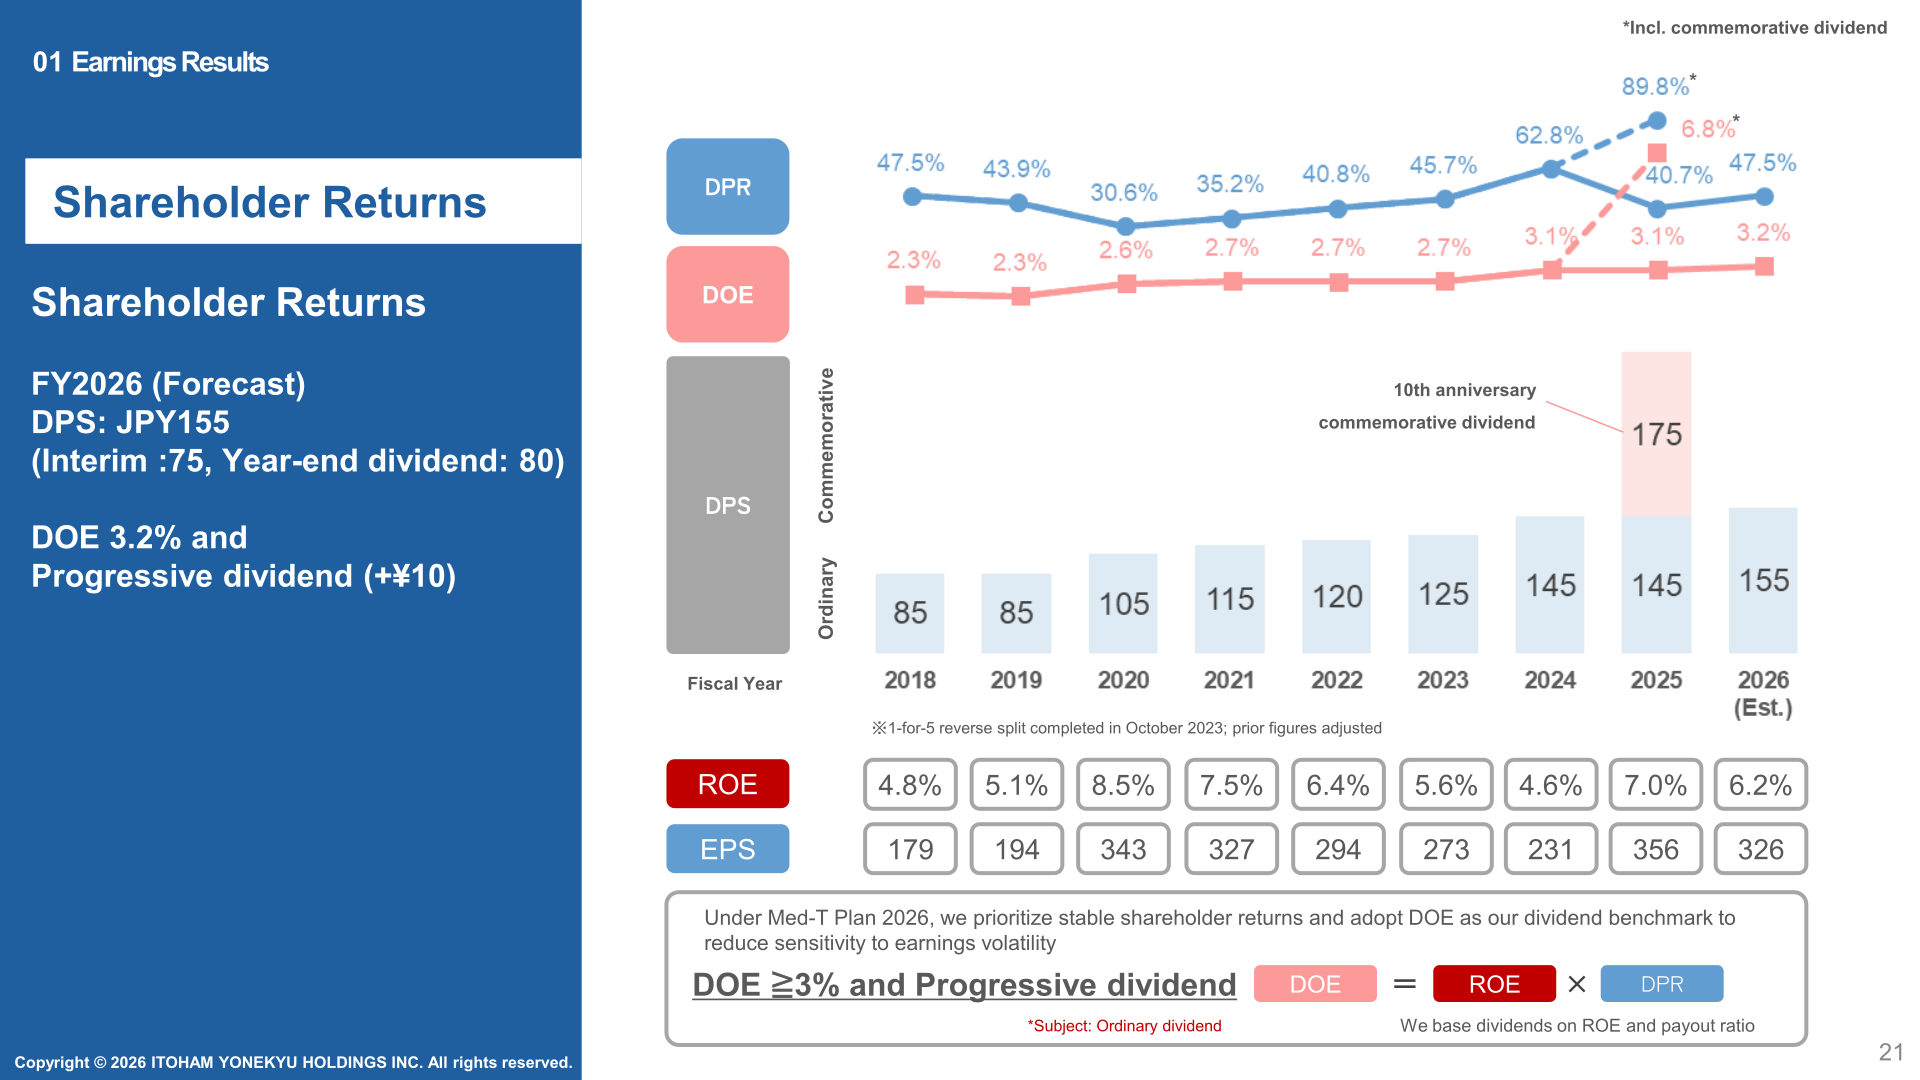
FY2025 DPS was JPY320.0, up JPY175 year on year, a figure that includes a 10th anniversary commemorative dividend of JPY175; DOE on that basis was 6.8% (+3.7%). For FY2026 the company plans DPS of JPY155 (interim JPY75, year-end JPY80), equivalent to DOE of 3.2% and a JPY10 increase under its progressive dividend policy. Under Med-T Plan 2026 the company states that it prioritizes stable shareholder returns and adopts DOE as its dividend benchmark to reduce sensitivity to earnings volatility, targeting DOE of 3% or more together with a progressive dividend (applied to the ordinary dividend). A 1-for-5 reverse stock split was completed in October 2023 and prior per-share figures are adjusted accordingly.
| Item | FY2025 | FY2026 (Forecast) |
|---|---|---|
| DPS (yen) | 320.0 * | 155 (Interim 75 / Year-end 80) |
| DOE | 6.8% * | 3.2% |
| EPS (yen) | 356.4 | 326 |
| ROE | 7.0% | 6.2% |
* FY2025 DPS and DOE include the 10th anniversary commemorative dividend of JPY175 per share.
Medium-Term Plan
The company reports that it achieved its Mid-Term Plan targets one year early. FY2025 ordinary profit of JPY30.4 billion, ROE of 7.0% and ROIC of 6.2% all exceeded the Mid-Term Plan targets of ordinary profit JPY30.0 billion, ROE 6.2% and ROIC 5.9%. The materials note that figures are presented under Japanese GAAP, that FY2026 covers Apr 1, 2026 to March 31, 2027, and that amounts are rounded to two decimal places so sums and differences may not equal totals.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















