
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Link and Motivation Inc. reported record-high revenues of ¥41,522 million for the fiscal year ended December 31, 2025, up 10.9% year on year, with gross profit up 13.7% to ¥22,605 million. Operating income fell 23.4% to ¥4,204 million and net income attributable to owners of the parent fell 56.1% to ¥1,621 million, after the company decided to recognize a full impairment loss on goodwill in the Career School business in order to further accelerate restructuring there. For 2026 the company forecasts record revenues of ¥46.7 billion and record operating income of ¥6.31 billion, and it has decided to carry out its largest share repurchase ever, up to a maximum aggregate amount of ¥6.0 billion.
Consolidated Results (Full-Year Actual)
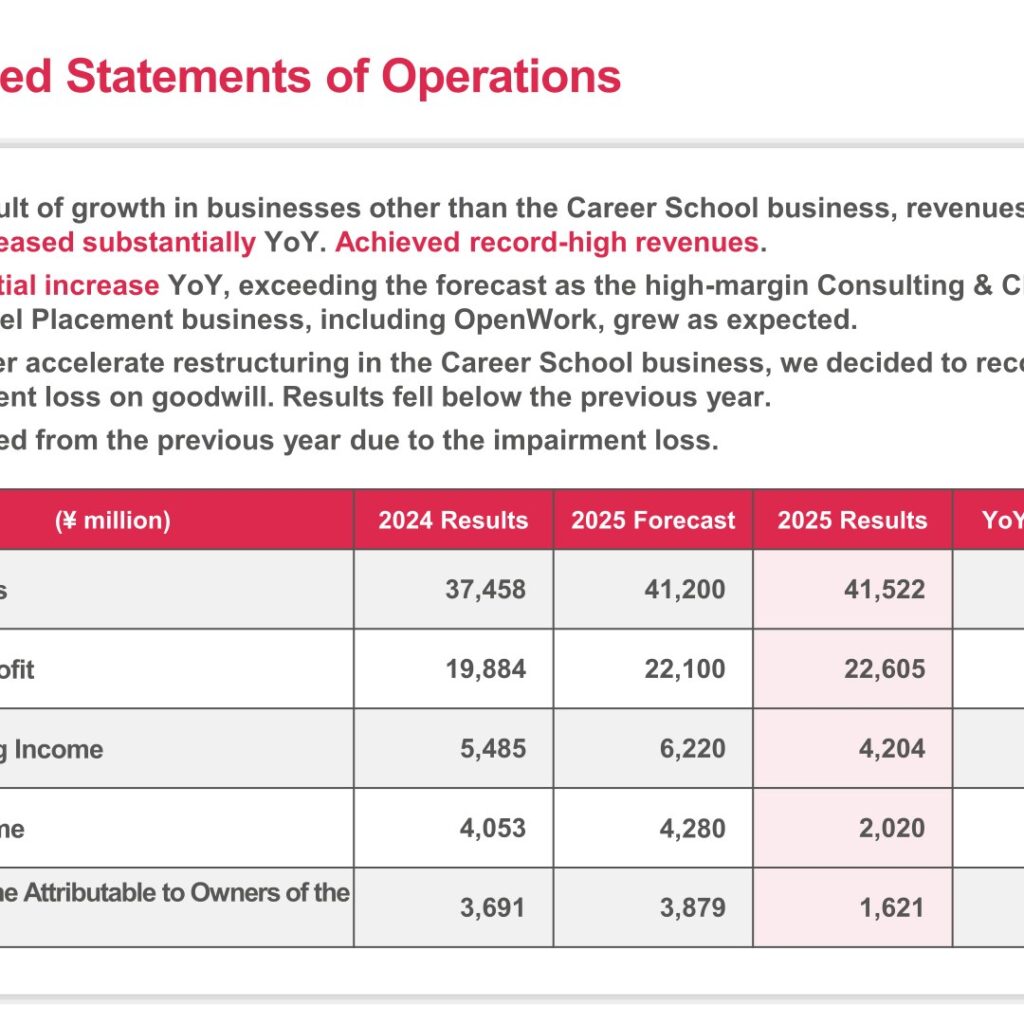
Revenues exceeded the company’s own forecast and increased substantially year on year as a result of growth in businesses other than the Career School business, achieving record-high revenues. Gross profit also increased substantially and exceeded the forecast, as the high-margin Consulting & Cloud business and the Personnel Placement business, including OpenWork, grew as expected. Operating income and net income fell below the previous year because of the impairment loss on goodwill.
| (¥ million) | 2024 Results | 2025 Forecast | 2025 Results | YoY Change |
|---|---|---|---|---|
| Revenues | 37,458 | 41,200 | 41,522 | 10.9% |
| Gross Profit | 19,884 | 22,100 | 22,605 | 13.7% |
| Operating Income | 5,485 | 6,220 | 4,204 | -23.4% |
| Net Income | 4,053 | 4,280 | 2,020 | -50.2% |
| Net Income Attributable to Owners of the Parent | 3,691 | 3,879 | 1,621 | -56.1% |
Total SG&A expenses rose 19.2% year on year to ¥16,925 million from ¥14,196 million, as the company focused on investment for growth acceleration. Each category increased due to the acquisition of three companies, including Unipos Inc., while sales-related expenses rose 27.1% to ¥3,496 million on expanded advertising at OpenWork and enhanced marketing for Motivation Cloud.
On the balance sheet, total assets grew ¥7,821 million to ¥40,999 million, total liabilities grew ¥5,388 million to ¥24,181 million and total equity grew ¥2,432 million to ¥16,817 million. ROE was 13.0%, down from 34.4%, reflecting the decrease in net income and the increase in equity related to the acquisition of Unipos Inc. Goodwill rose to ¥11,983 million from ¥9,346 million, while goodwill in the Career School business was reduced to zero by the impairment loss.
Segment Results
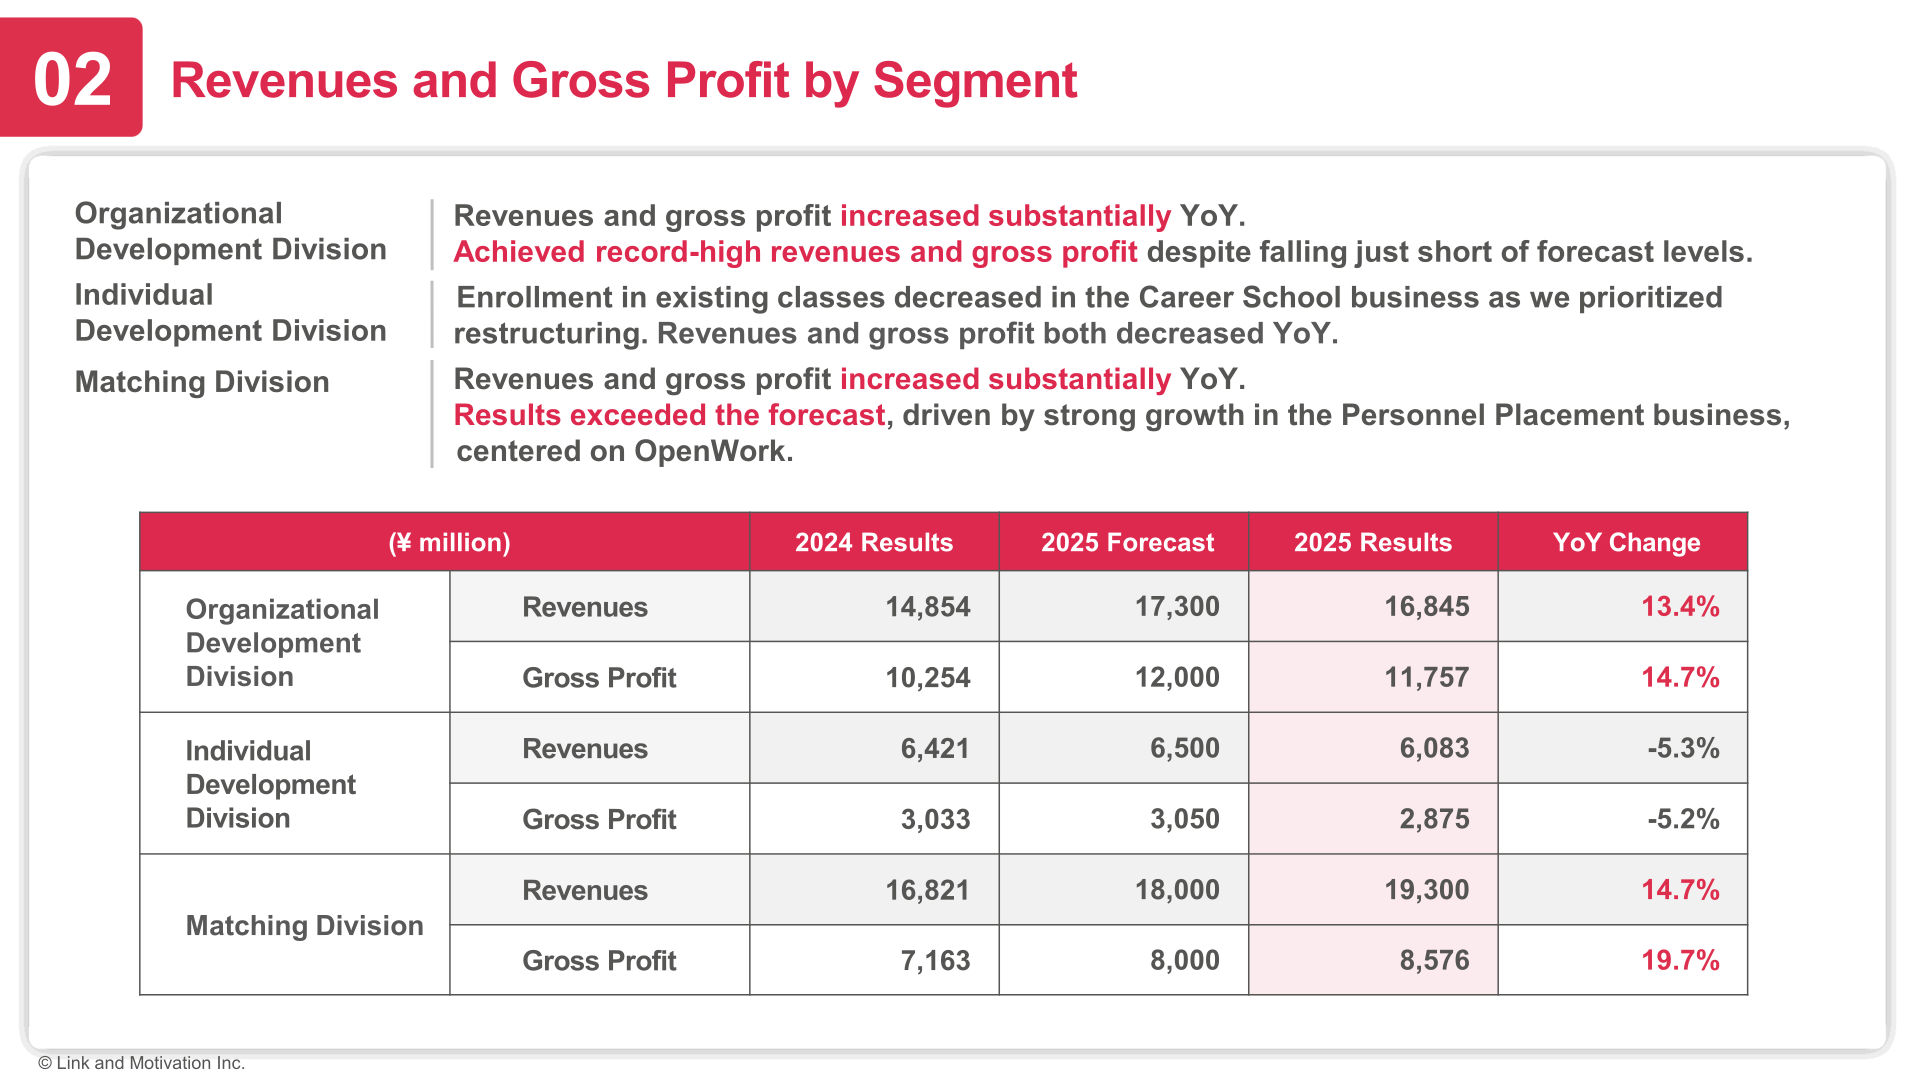
The Organizational Development Division posted substantial year-on-year growth in revenues and gross profit, achieving record highs despite falling just short of forecast levels. The Individual Development Division saw both revenues and gross profit decline as enrollment in existing Career School classes decreased while the company prioritized restructuring. The Matching Division exceeded its forecast, driven by strong growth in the Personnel Placement business centered on OpenWork.
| (¥ million) | Metric | 2024 Results | 2025 Forecast | 2025 Results | YoY Change |
|---|---|---|---|---|---|
| Organizational Development Division | Revenues | 14,854 | 17,300 | 16,845 | 13.4% |
| Organizational Development Division | Gross Profit | 10,254 | 12,000 | 11,757 | 14.7% |
| Individual Development Division | Revenues | 6,421 | 6,500 | 6,083 | -5.3% |
| Individual Development Division | Gross Profit | 3,033 | 3,050 | 2,875 | -5.2% |
| Matching Division | Revenues | 16,821 | 18,000 | 19,300 | 14.7% |
| Matching Division | Gross Profit | 7,163 | 8,000 | 8,576 | 19.7% |
By business, Consulting & Cloud revenues rose 14.8% to ¥13,293 million and gross profit rose 13.9% to ¥9,941 million, as Motivation Cloud drove growth. IR Support revenues rose 6.2% to ¥3,902 million on integrated report production and growth in the video streaming service. Career School revenues fell 7.5% to ¥5,121 million, while Cram School revenues rose 8.7% to ¥962 million. In the Matching Division, ALT Placement revenues rose 11.0% to ¥14,284 million as the number of ALTs dispatched increased in line with expectations, and Personnel Placement revenues rose 27.4% to ¥5,056 million on growth in OpenWork Recruiting.
| Business (¥ million) | Metric | 2024 Results | 2025 Results | YoY Change |
|---|---|---|---|---|
| Consulting & Cloud Business | Revenues | 11,579 | 13,293 | 14.8% |
| Consulting & Cloud Business | Gross Profit | 8,730 | 9,941 | 13.9% |
| IR Support Business | Revenues | 3,674 | 3,902 | 6.2% |
| IR Support Business | Gross Profit | 1,748 | 2,030 | 16.1% |
| Career School Business | Revenues | 5,536 | 5,121 | -7.5% |
| Career School Business | Gross Profit | 2,616 | 2,398 | -8.3% |
| Cram School Business | Revenues | 885 | 962 | 8.7% |
| Cram School Business | Gross Profit | 417 | 476 | 14.3% |
| ALT Placement Business | Revenues | 12,873 | 14,284 | 11.0% |
| ALT Placement Business | Gross Profit | 3,266 | 3,654 | 11.9% |
| Personnel Placement Business | Revenues | 3,968 | 5,056 | 27.4% |
| Personnel Placement Business | Gross Profit | 3,917 | 4,962 | 26.7% |
Motivation Cloud monthly fee revenue was ¥627,382 thousand at December 31, 2025, a year-on-year change of 21.6%, but fell short of the forecast of ¥650,000 thousand for the end of 2025, reflecting a temporary decrease in sales negotiations in the first half as customers’ search behavior changed with the rise of generative AI. The number of negotiations recovered in the second half following countermeasures including an increased marketing budget.
Outlook for 2026
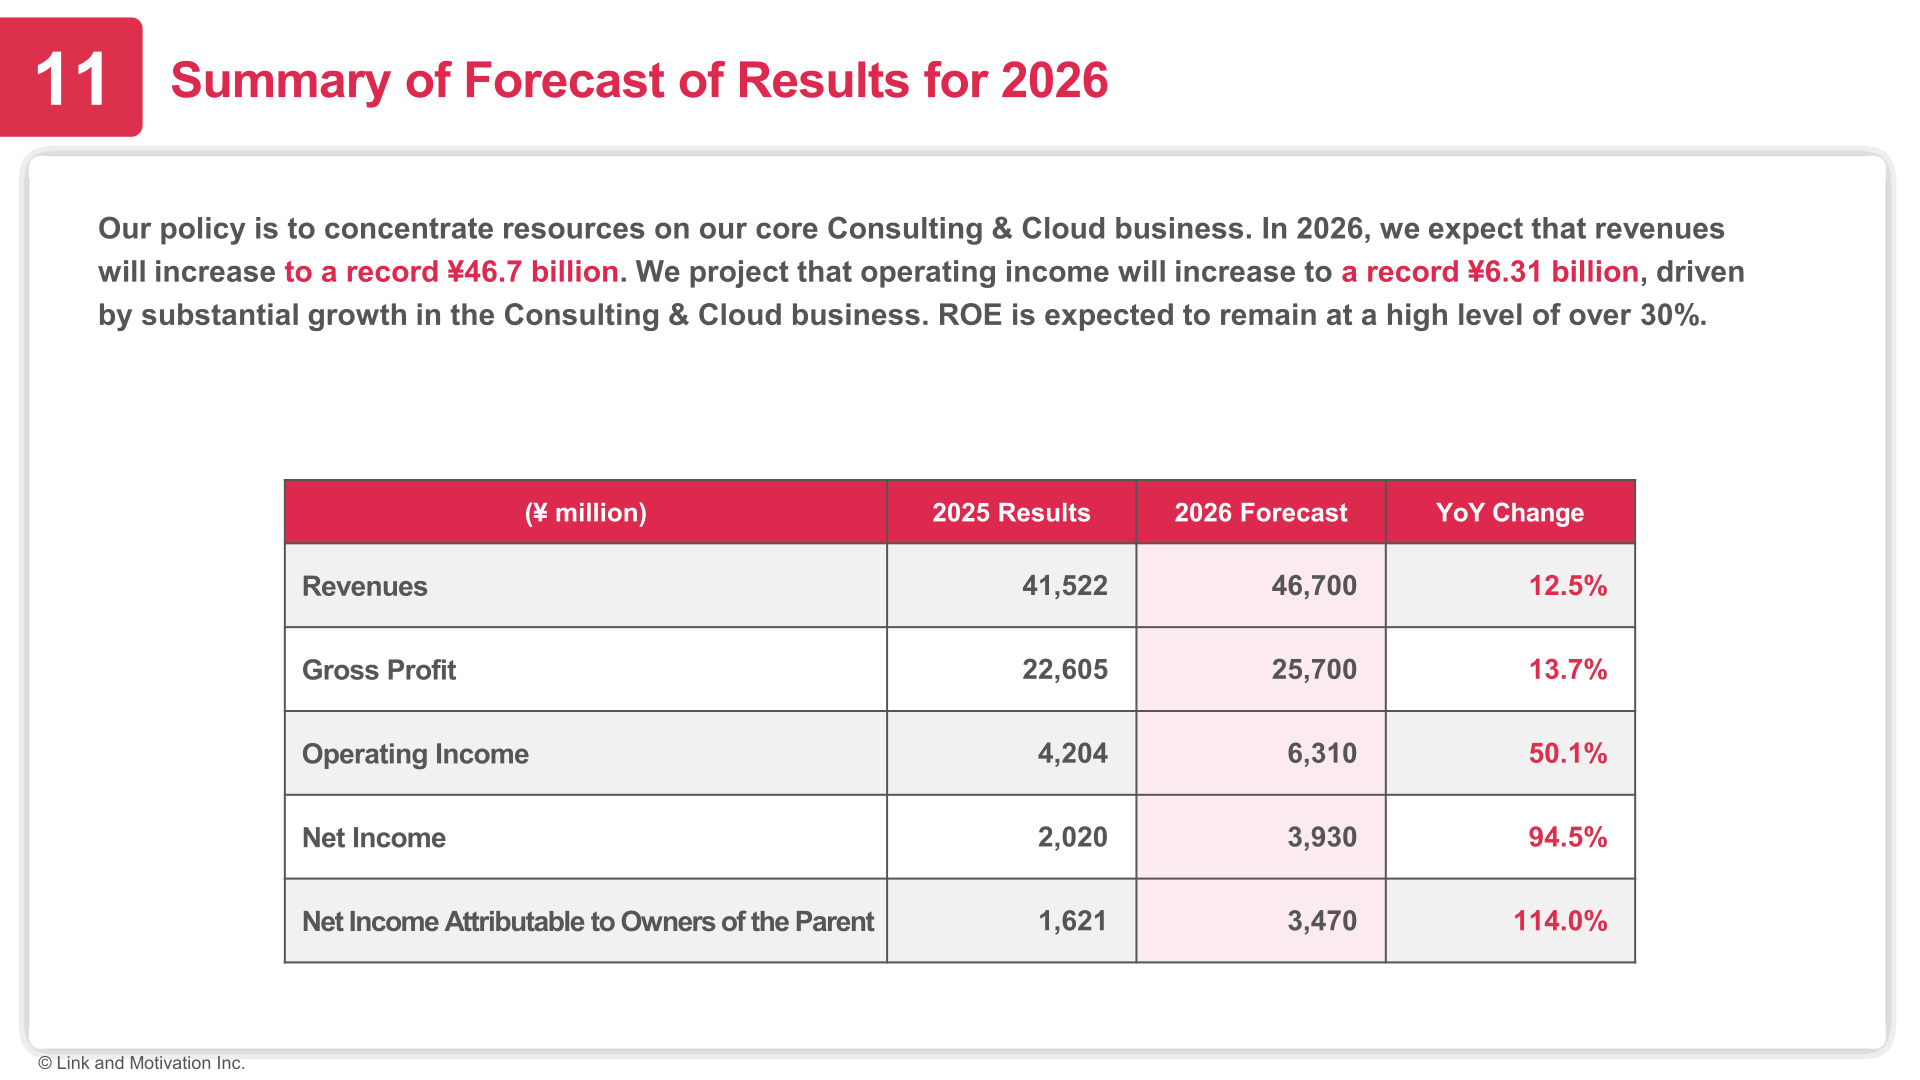
The company’s policy is to concentrate resources on its core Consulting & Cloud business. For 2026 it expects revenues to increase to a record ¥46.7 billion and operating income to increase to a record ¥6.31 billion, driven by substantial growth in the Consulting & Cloud business. ROE is expected to remain at a high level of over 30%.
| (¥ million) | 2025 Results | 2026 Forecast | YoY Change |
|---|---|---|---|
| Revenues | 41,522 | 46,700 | 12.5% |
| Gross Profit | 22,605 | 25,700 | 13.7% |
| Operating Income | 4,204 | 6,310 | 50.1% |
| Net Income | 2,020 | 3,930 | 94.5% |
| Net Income Attributable to Owners of the Parent | 1,621 | 3,470 | 114.0% |
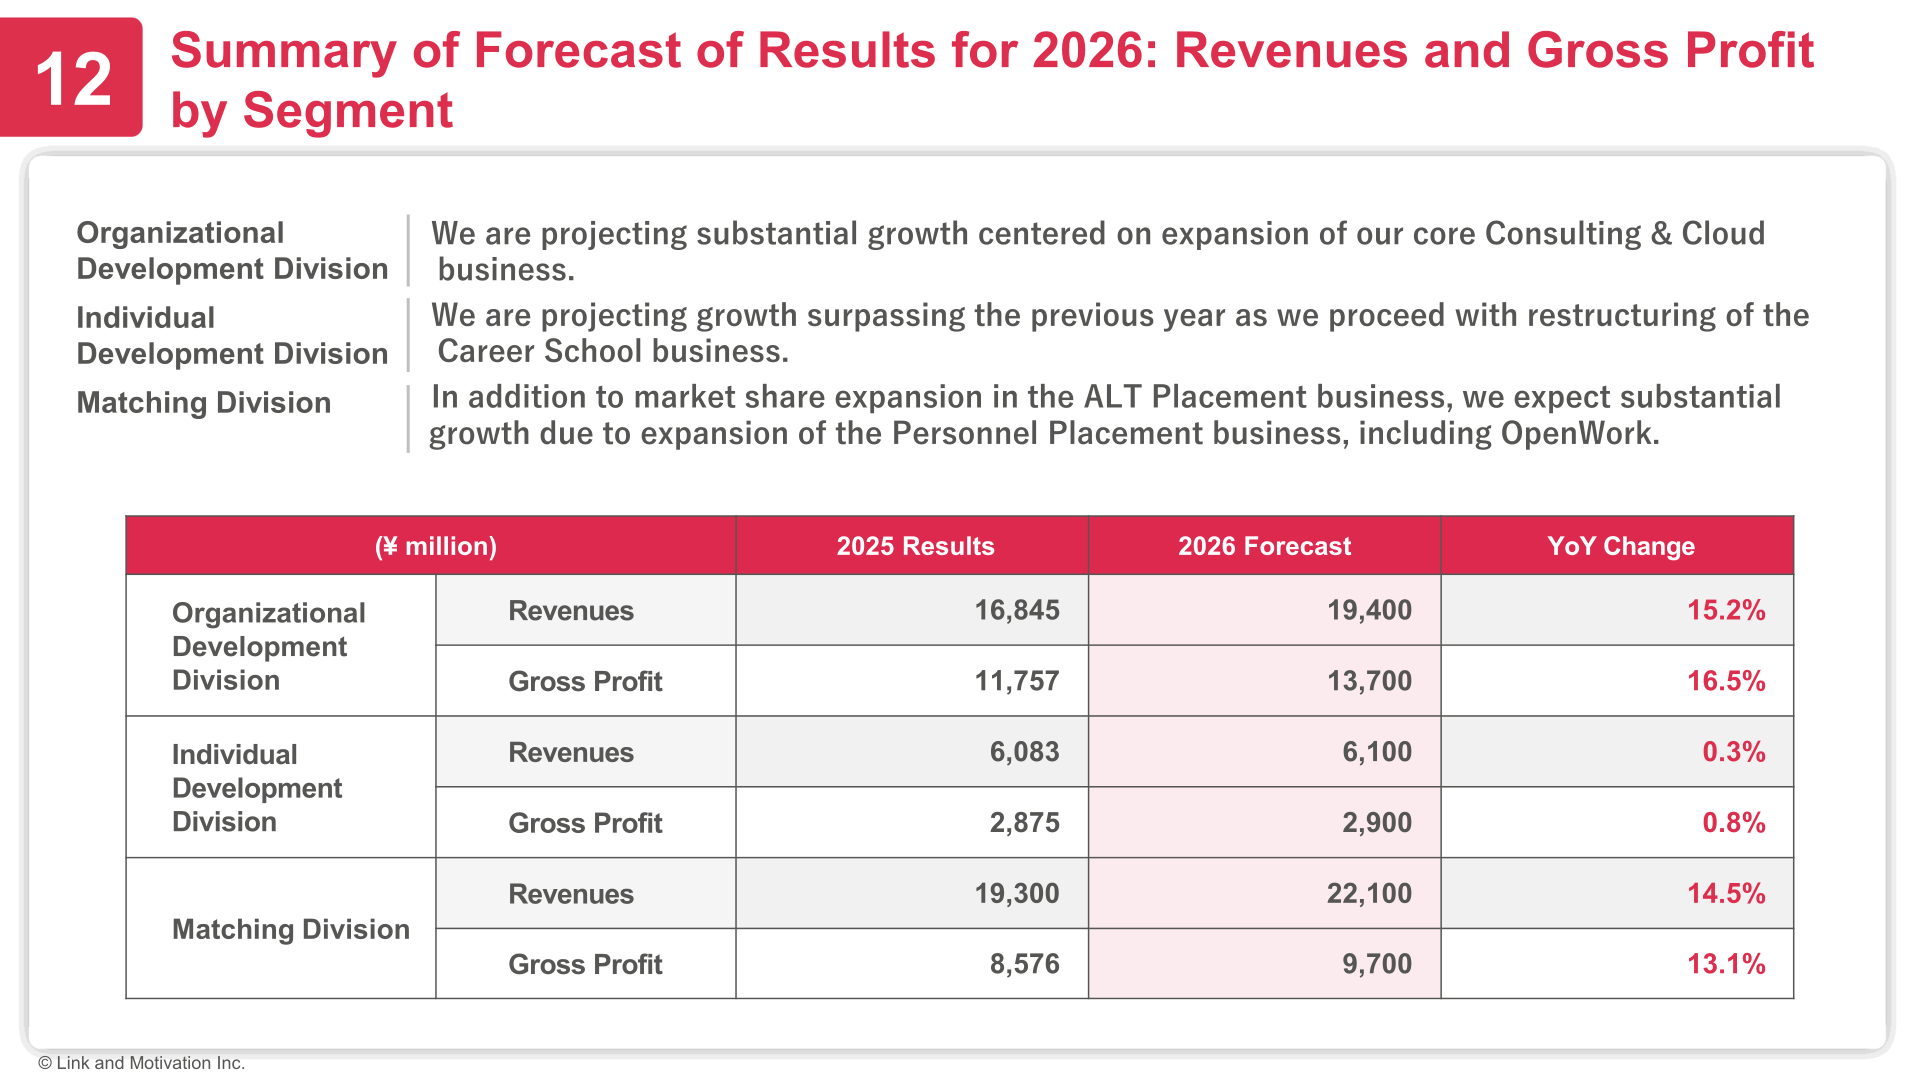
By segment, the company projects substantial growth centered on expansion of the core Consulting & Cloud business, growth surpassing the previous year in the Individual Development Division as restructuring of the Career School business proceeds, and substantial growth in the Matching Division from market share expansion in ALT Placement and expansion of the Personnel Placement business, including OpenWork. Motivation Cloud monthly fee revenue at the end of 2026 is projected at ¥700,000 thousand, an 11.6% increase year on year.
| (¥ million) | Metric | 2025 Results | 2026 Forecast | YoY Change |
|---|---|---|---|---|
| Organizational Development Division | Revenues | 16,845 | 19,400 | 15.2% |
| Organizational Development Division | Gross Profit | 11,757 | 13,700 | 16.5% |
| Individual Development Division | Revenues | 6,083 | 6,100 | 0.3% |
| Individual Development Division | Gross Profit | 2,875 | 2,900 | 0.8% |
| Matching Division | Revenues | 19,300 | 22,100 | 14.5% |
| Matching Division | Gross Profit | 8,576 | 9,700 | 13.1% |
Shareholder Returns
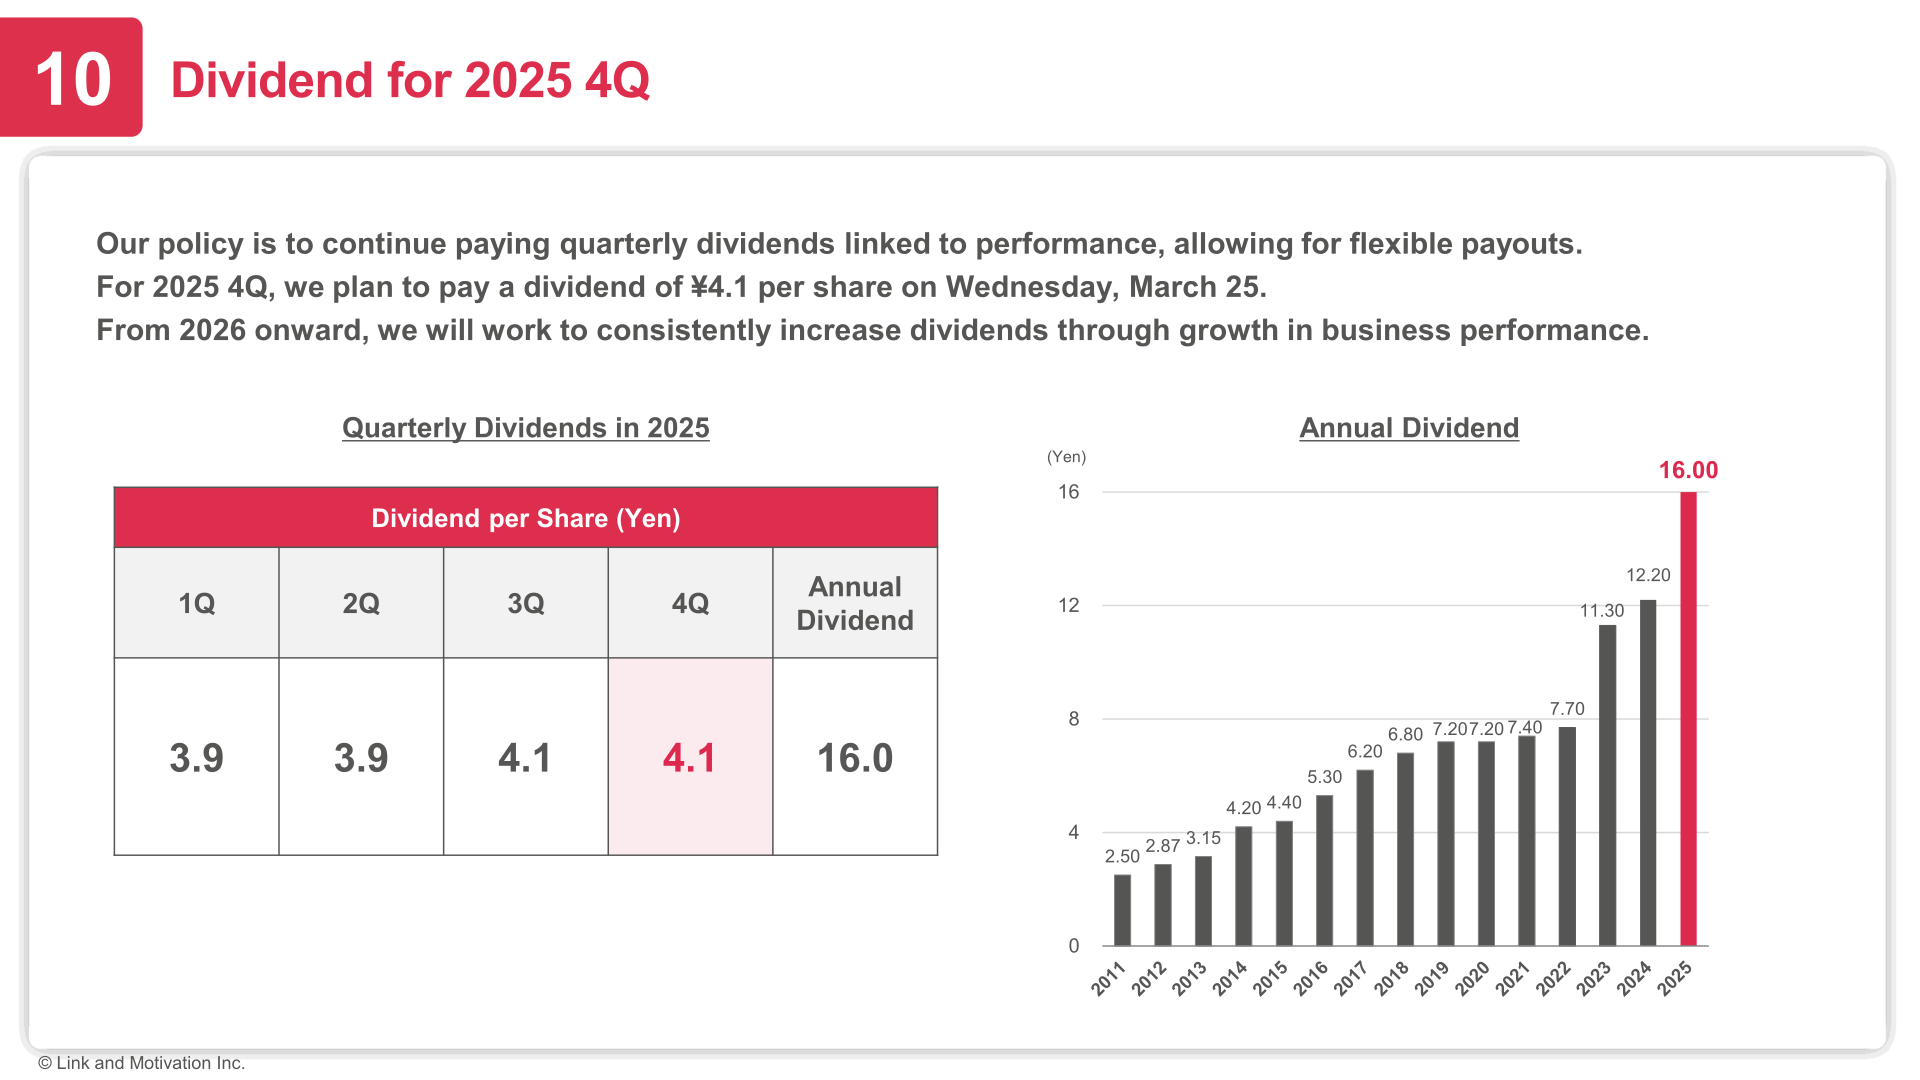
The company’s policy is to continue paying quarterly dividends linked to performance, allowing for flexible payouts. Quarterly dividends for 2025 were ¥3.9 in the first quarter, ¥3.9 in the second quarter, ¥4.1 in the third quarter and ¥4.1 in the fourth quarter, for an annual dividend of ¥16.0 per share. The fourth-quarter dividend of ¥4.1 per share is scheduled to be paid on Wednesday, March 25. From 2026 onward, the company says it will work to consistently increase dividends through growth in business performance.
| Dividend per Share (Yen) | 1Q | 2Q | 3Q | 4Q | Annual Dividend |
|---|---|---|---|---|---|
| Quarterly Dividends in 2025 | 3.9 | 3.9 | 4.1 | 4.1 | 16.0 |
The company has also decided to carry out its largest-ever share buyback, with a maximum amount of ¥6.0 billion and a buyback period from February 13, 2026 to August 31, 2026. The stated objective is to increase ROE through the repurchase of shares. The maximum amounts of the most recent acquisitions were ¥2.0 billion in November 2023 and ¥1.0 billion in May 2024.
Medium-Term Growth Strategy
For medium-term growth, the company will shift to a recurring revenue business model centered on the Consulting & Cloud business. Its targets for 2030 are operating income of ¥15.0 billion (approximately 3.5 times higher than 2025) and ARR of ¥24.0 billion (approximately 3.0 times higher than 2025), mainly centered on Motivation Cloud. To further accelerate restructuring in the Career School business, the company decided to recognize a full impairment loss on goodwill.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















