
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
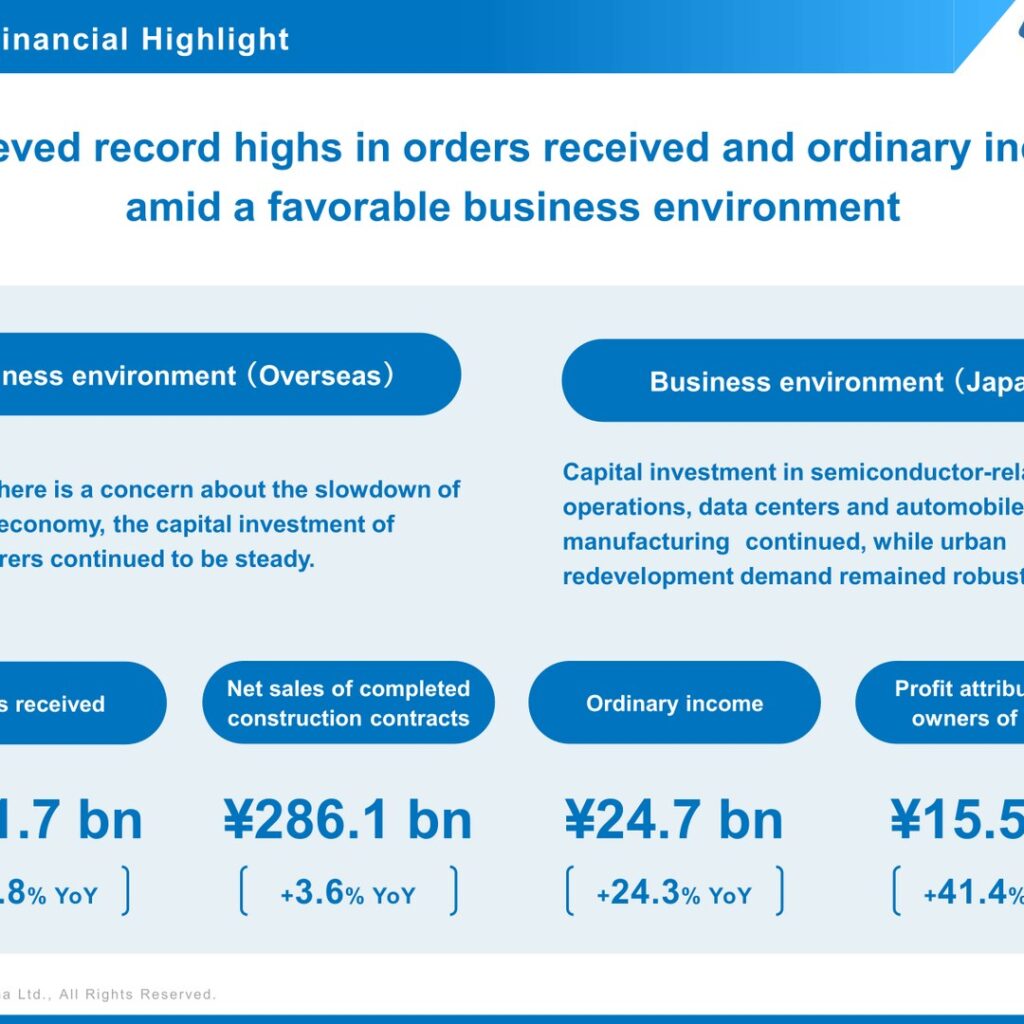
Taikisha Ltd. released its Financial Results Material for FY2025, the fiscal year ended March 31, 2026. The company achieved record highs in orders received and ordinary income amid a favorable business environment: orders received came to 351.7 billion yen (+26.8% YoY), net sales of completed construction contracts to 286.1 billion yen (+3.6% YoY), ordinary income to 24.7 billion yen (+24.3% YoY) and profit attributable to owners of parent to 15.5 billion yen (+41.4% YoY). Orders received and profit figures exceeded the forecasts that had been revised at the announcement of the third-quarter results.
Consolidated Results (Full-Year Actual)
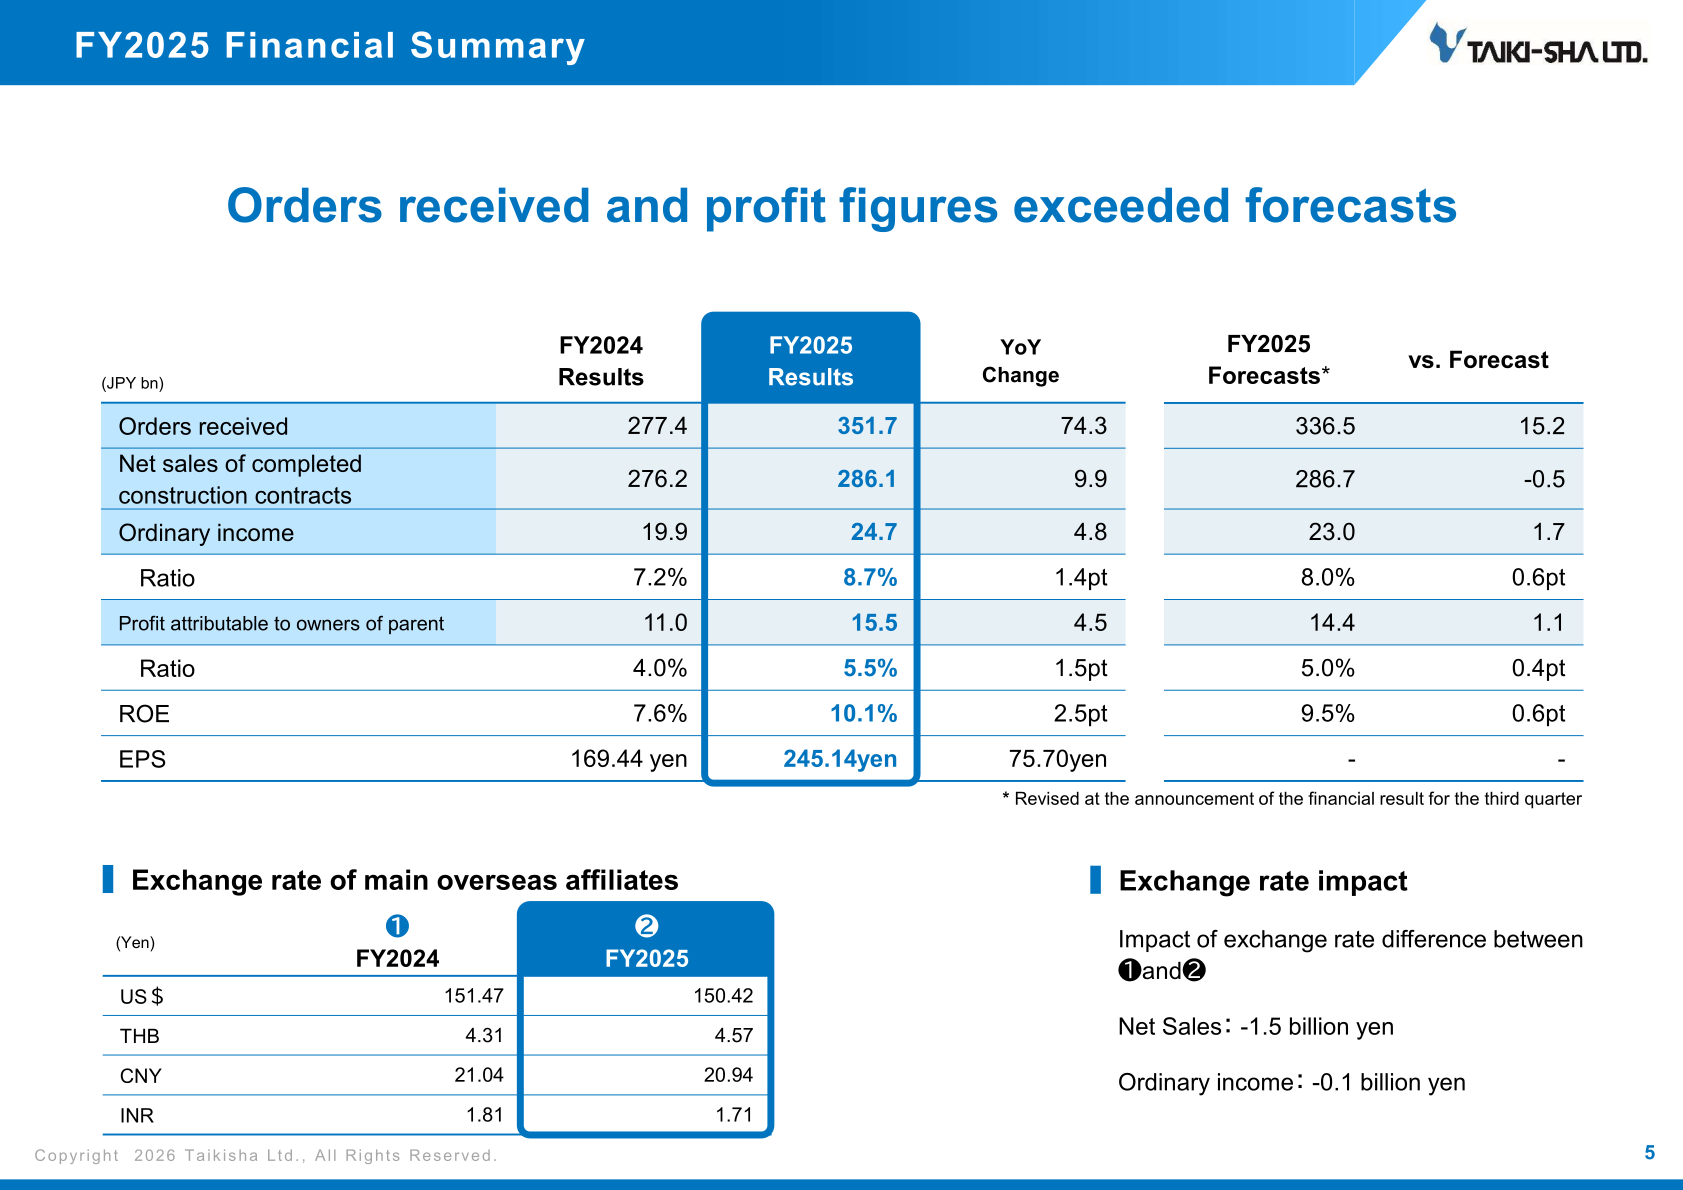
Net sales of completed construction contracts rose 9.9 billion yen year on year to 286.1 billion yen, while ordinary income increased 4.8 billion yen to 24.7 billion yen, lifting the ordinary income ratio by 1.4pt to 8.7%. ROE improved 2.5pt to 10.1% and EPS rose 75.70 yen to 245.14 yen. On the income statement, gross profit on completed construction contracts was 55.2 billion yen (ratio 19.3%, versus 16.3% in FY2024) and operating income was 23.3 billion yen, against 17.9 billion yen in FY2024. The materials attribute the year-on-year increase in ordinary income to higher net sales and improved profitability of construction work, breaking the change down into +8.33 from the increase of net sales, +1.91 from improvement of gross profit on completed construction contracts, -4.90 from the increase of selling, general and administrative expenses and -0.49 from non-operating income and expenses.
Regarding the business environment, the company notes that overseas, although there is a concern about the slowdown of the global economy, the capital investment of manufacturers continued to be steady; in Japan, capital investment in semiconductor-related operations, data centers and automobile manufacturing continued, while urban redevelopment demand remained robust. The difference in exchange rates between FY2025 and FY2024 had an impact of -1.5 billion yen on net sales and -0.1 billion yen on ordinary income.
| Item (JPY bn unless noted) | FY2025 Results | FY2024 Results | YoY Change | FY2025 Forecasts* | vs. Forecast |
|---|---|---|---|---|---|
| Orders received | 351.7 | 277.4 | 74.3 | 336.5 | 15.2 |
| Net sales of completed construction contracts | 286.1 | 276.2 | 9.9 | 286.7 | -0.5 |
| Ordinary income | 24.7 | 19.9 | 4.8 | 23.0 | 1.7 |
| Ordinary income ratio | 8.7% | 7.2% | 1.4pt | 8.0% | 0.6pt |
| Profit attributable to owners of parent | 15.5 | 11.0 | 4.5 | 14.4 | 1.1 |
| Net income ratio | 5.5% | 4.0% | 1.5pt | 5.0% | 0.4pt |
| ROE | 10.1% | 7.6% | 2.5pt | 9.5% | 0.6pt |
| EPS | 245.14 yen | 169.44 yen | 75.70 yen | – | – |
* FY2025 forecasts were revised at the announcement of the financial result for the third quarter.
Segment Results
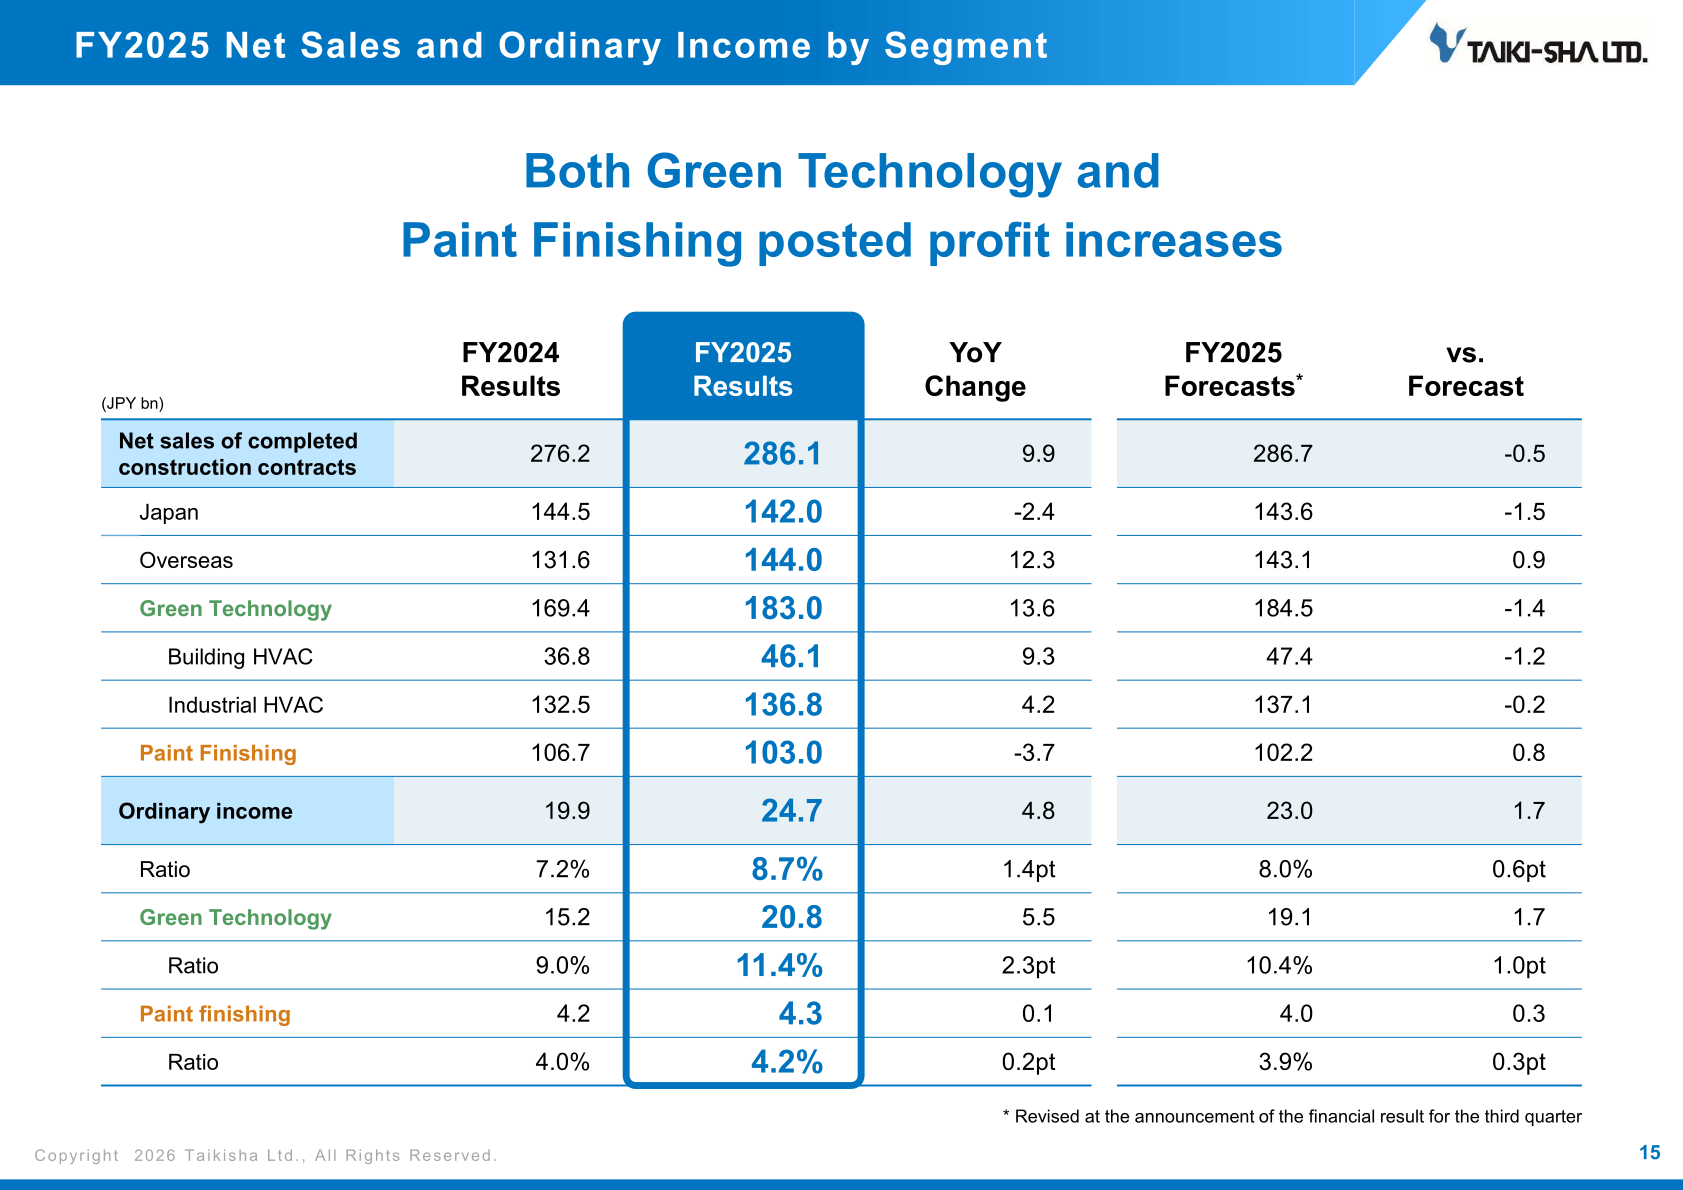
Orders received increased in both the Green Technology System Division and the Paint Finishing System Division. Green Technology orders received rose 37.3 billion yen to 216.5 billion yen, driven by orders received for semiconductor, electrical and electronics, and data center projects, while Paint Finishing orders received rose 36.9 billion yen to 135.1 billion yen on large-scale projects in Japan and overseas. By region, orders received in Japan were 166.2 billion yen (+29.0) and overseas 185.4 billion yen (+45.3).
On the profit side, both divisions posted profit increases. Green Technology ordinary income rose 5.5 billion yen to 20.8 billion yen, with the ratio up 2.3pt to 11.4%, due to higher sales and improved profitability in domestic projects. Paint Finishing ordinary income rose 0.1 billion yen to 4.3 billion yen (ratio 4.2%) on improved profitability of projects on hand, even though its net sales declined 3.7 billion yen to 103.0 billion yen. Construction carried-forward reached a record high of 304.4 billion yen, up 64.5 billion yen year on year, comprising 186.2 billion yen in Green Technology and 118.1 billion yen in Paint Finishing.
| Segment / Item (JPY bn) | FY2025 Results | FY2024 Results | YoY Change |
|---|---|---|---|
| Orders received – Green Technology | 216.5 | 179.1 | 37.3 |
| Orders received – Building HVAC | 77.1 | 53.7 | 23.3 |
| Orders received – Industrial HVAC | 139.4 | 125.4 | 14.0 |
| Orders received – Paint Finishing | 135.1 | 98.2 | 36.9 |
| Net sales – Green Technology | 183.0 | 169.4 | 13.6 |
| Net sales – Building HVAC | 46.1 | 36.8 | 9.3 |
| Net sales – Industrial HVAC | 136.8 | 132.5 | 4.2 |
| Net sales – Paint Finishing | 103.0 | 106.7 | -3.7 |
| Net sales – Japan | 142.0 | 144.5 | -2.4 |
| Net sales – Overseas | 144.0 | 131.6 | 12.3 |
| Ordinary income – Green Technology | 20.8 | 15.2 | 5.5 |
| Ordinary income ratio – Green Technology | 11.4% | 9.0% | 2.3pt |
| Ordinary income – Paint Finishing | 4.3 | 4.2 | 0.1 |
| Ordinary income ratio – Paint Finishing | 4.2% | 4.0% | 0.2pt |
FY2026 Forecast
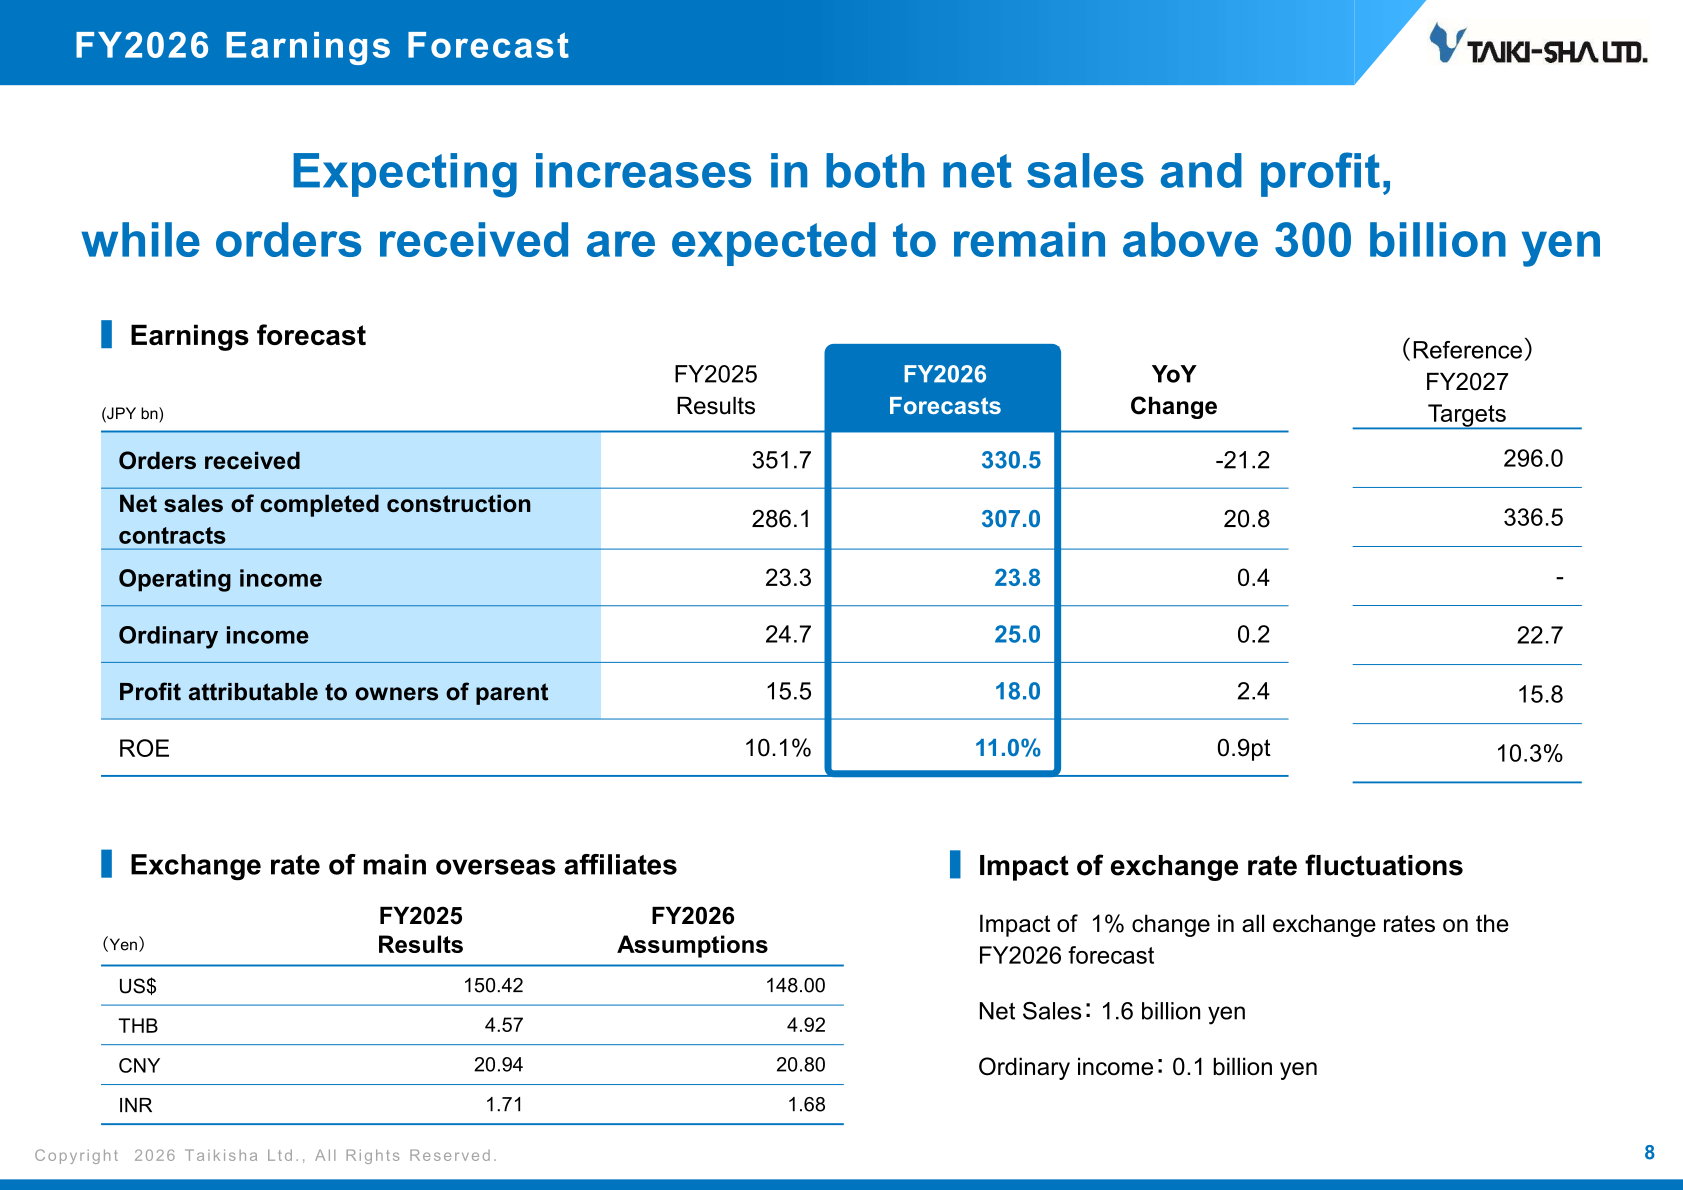
For FY2026, Taikisha expects increases in both net sales and profit, while orders received are expected to remain above 300 billion yen. Net sales of completed construction contracts are forecast at 307.0 billion yen (+20.8 YoY), operating income at 23.8 billion yen, ordinary income at 25.0 billion yen and profit attributable to owners of parent at 18.0 billion yen, with ROE of 11.0%. Orders received are forecast at 330.5 billion yen, down 21.2 billion yen from the record FY2025 level. The change in ordinary income is broken down into +3.92 from the increase of net sales, -1.38 from the decline in gross profit on completed construction contracts, -2.06 from the increase of selling, general and administrative expenses and -0.26 from non-operating income and expenses. The forecast assumes exchange rates of 148.00 yen to the US dollar, 4.92 yen to the Thai baht, 20.80 yen to the Chinese yuan and 1.68 yen to the Indian rupee; a 1% change in all exchange rates would affect the FY2026 forecast by 1.6 billion yen in net sales and 0.1 billion yen in ordinary income.
By segment, Green Technology is expected to achieve higher net sales and profit, with orders received of 231.0 billion yen (record high) and ordinary income of 21.8 billion yen, while Paint Finishing is expected to achieve higher net sales of 110.0 billion yen but slightly lower ordinary income of 4.2 billion yen, with orders received of 97.0 billion yen after a pullback from prior large-scale projects. Segment classifications will change from FY2026, and FY2025 results have been reclassified and presented based on the new classifications.
| Item (JPY bn unless noted) | FY2026 Forecasts | FY2025 Results | YoY Change | FY2027 Targets (Reference) |
|---|---|---|---|---|
| Orders received | 330.5 | 351.7 | -21.2 | 296.0 |
| Net sales of completed construction contracts | 307.0 | 286.1 | 20.8 | 336.5 |
| Operating income | 23.8 | 23.3 | 0.4 | – |
| Ordinary income | 25.0 | 24.7 | 0.2 | 22.7 |
| Profit attributable to owners of parent | 18.0 | 15.5 | 2.4 | 15.8 |
| ROE | 11.0% | 10.1% | 0.9pt | 10.3% |
Shareholder Returns
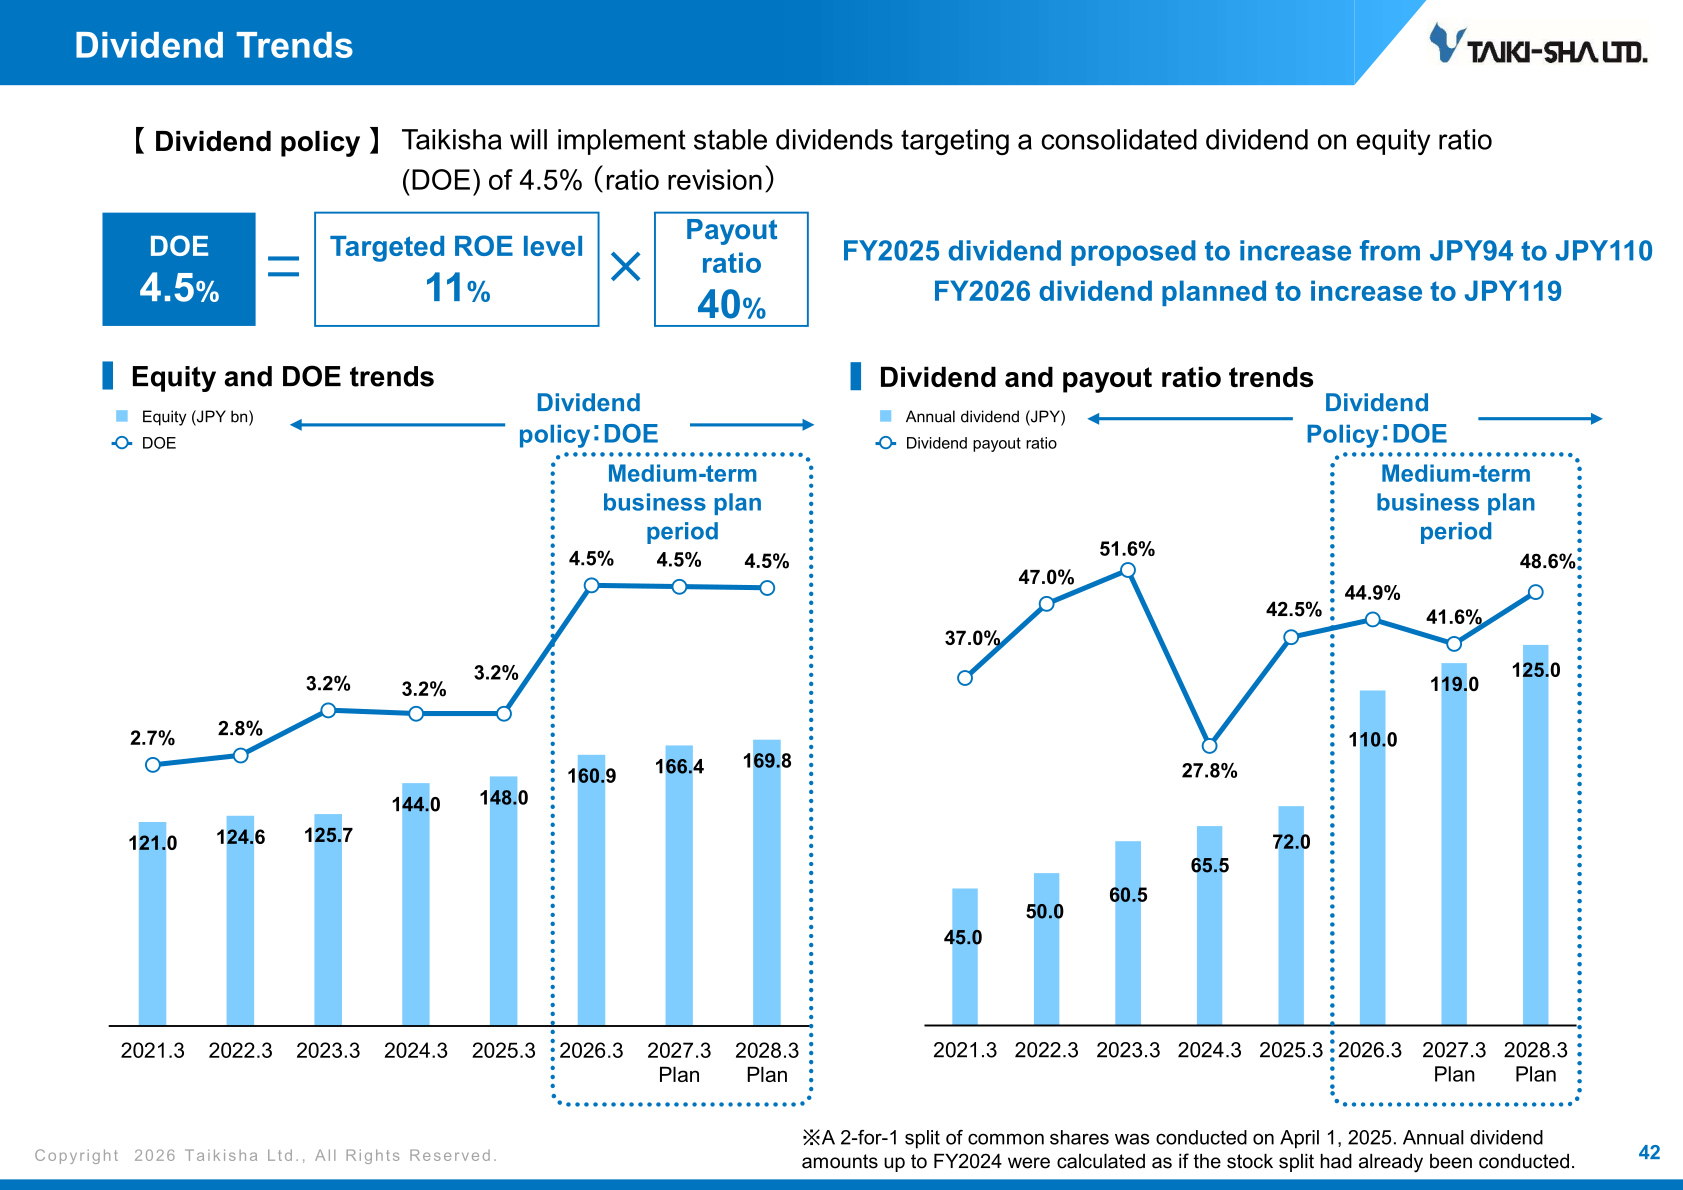
Taikisha’s dividend policy is to implement stable dividends targeting a consolidated dividend on equity ratio (DOE) of 4.5%. The FY2025 dividend is proposed to increase from 94 yen to 110 yen, and the FY2026 dividend is planned to increase to 119 yen. A 2-for-1 split of common shares was conducted on April 1, 2025, and annual dividend amounts up to FY2024 were calculated as if the stock split had already been conducted. For treasury shares, the company plans to acquire 5 billion yen in treasury shares per year during the period of its medium-term business plan, in order to improve capital efficiency and realize flexible financial policies.
| Item | FY2025 | FY2026 (Plan) | FY2027 (Plan) |
|---|---|---|---|
| Annual dividend per share | 110 yen | 119 yen | – |
| DOE | 4.5% | 4.5% | 4.5% |
| Share buybacks (JPY bn) | 5.0 | 5.0 | 5.0 |
Medium-Term Business Plan and Topics
Under the Medium-Term Business Plan covering FY2025 to FY2027, the company states that the ROE level moved upward along with continuous profit growth, and it has raised the target ROE from the initial 10.0% to 11.0% while revising the dividend policy to a DOE of 4.5% (previously 4.0%). The FY2027 targets are orders received of 296.0 billion yen, net sales of completed construction projects of 336.5 billion yen, ordinary income of 22.7 billion yen, profit attributable to owners of parent of 15.8 billion yen and ROE of 10.3%. The 10-Year Plan 2035 targets net sales of 400.0 billion yen for FY2030 and more than 500.0 billion yen for FY2034, with ROE of 12% or higher and DOE of 5.0% or higher for FY2034.
On cross-shareholdings, proceeds from sale were 1.9 billion yen in FY2025 and the ratio to net assets stood at 21.1% as of the end of March 2026, affected by the stock price increase. The company has increased its planned sales of cross-shareholdings to 9.5 billion yen during the current Medium-Term Business Plan period (from 5.0 billion yen as of May 2025), targeting a ratio to net assets of 15% or lower as of the end of March 2028. Investment under the plan totals 38.0 billion yen over three years, of which 3.1 billion yen was invested in FY2025. Reported topics include an M&A transaction executed by North American group company Encore Automation LLC with a North American automation company, expanded cleanroom panel production capacity at Indian consolidated subsidiary Nicomac Taikisha Clean Rooms Private Limited, an order in Europe for a project worth several hundred million euros scheduled for completion in FY2028, the establishment of a Regional Strategy Department, and a new credit rating of “A (Stable)” obtained from Japan Credit Rating Agency, Ltd.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















