
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
SEIKITOKYU KOGYO CO., LTD. reported consolidated net sales of 95,259 million yen for FY2025 (the fiscal year ended March 31, 2026), down 4.1% year on year, while operating profit rose 9.9% to 6,417 million yen, ordinary profit rose 8.5% to 6,278 million yen and profit rose 20.0% to 4,666 million yen. The company states that it achieved profit growth for the third consecutive year despite the impact of rising costs. Operating profit and profit both reached the target figures for the final year of the Medium-term Management Plan (FY2024-2026) one year ahead of schedule. For FY2026 (the fiscal year ending March 31, 2027), the company forecasts consolidated net sales of 102,700 million yen and profit of 4,700 million yen.
Consolidated Results (Full-Year Actual)
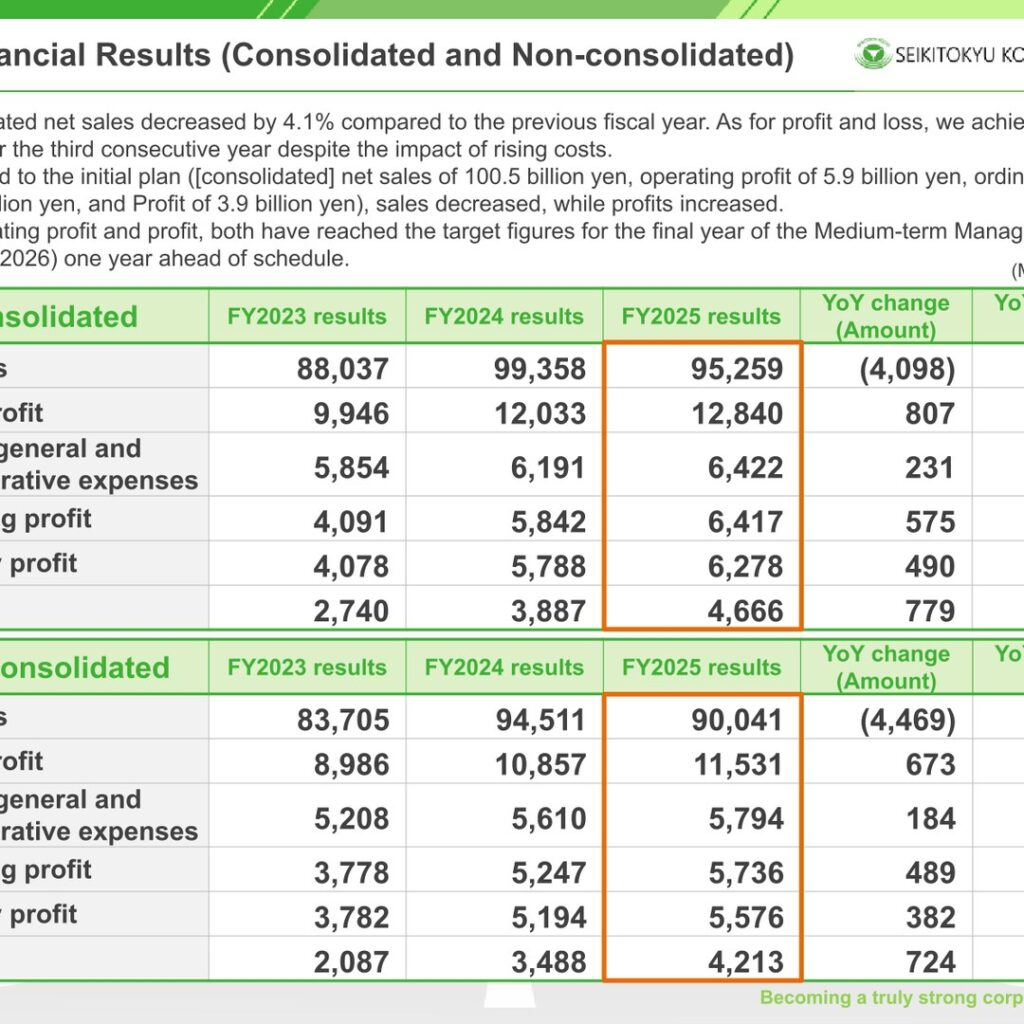
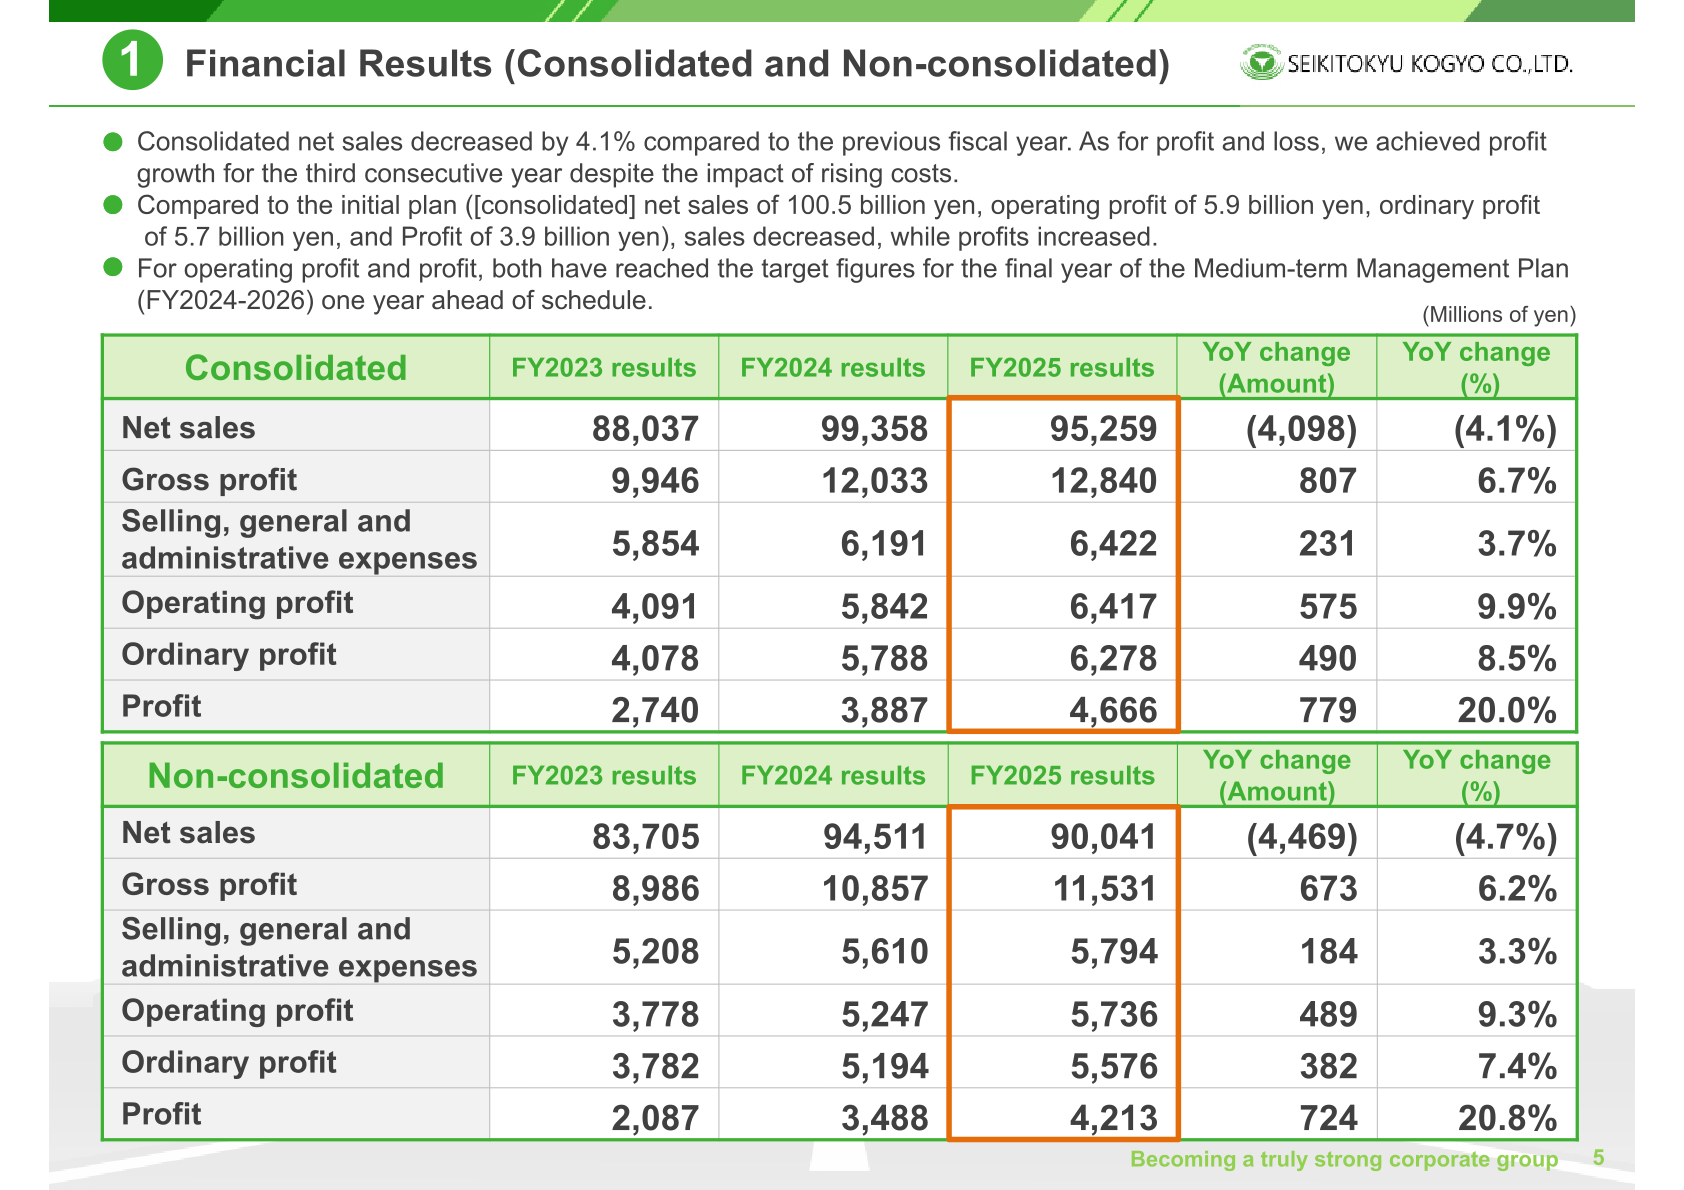
Consolidated net sales decreased by 4.1% compared to the previous fiscal year. As for profit and loss, the company achieved profit growth for the third consecutive year despite the impact of rising costs. Compared to the initial plan (consolidated net sales of 100.5 billion yen, operating profit of 5.9 billion yen, ordinary profit of 5.7 billion yen, and Profit of 3.9 billion yen), sales decreased, while profits increased. On the business environment, the presentation notes that public construction investment in the road construction market remained strong due to disaster prevention and mitigation projects as well as for building national resilience, while raw material and energy prices continued to remain at a high level and crude oil prices surged from late in the fiscal year given the increased tension in the Middle East.
| Consolidated (Millions of yen) | FY2025 results | FY2024 results | FY2023 results | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|---|
| Net sales | 95,259 | 99,358 | 88,037 | (4,098) | (4.1%) |
| Gross profit | 12,840 | 12,033 | 9,946 | 807 | 6.7% |
| Selling, general and administrative expenses | 6,422 | 6,191 | 5,854 | 231 | 3.7% |
| Operating profit | 6,417 | 5,842 | 4,091 | 575 | 9.9% |
| Ordinary profit | 6,278 | 5,788 | 4,078 | 490 | 8.5% |
| Profit | 4,666 | 3,887 | 2,740 | 779 | 20.0% |
On a non-consolidated basis, net sales were 90,041 million yen (down 4.7%), operating profit was 5,736 million yen (up 9.3%), ordinary profit was 5,576 million yen (up 7.4%) and profit was 4,213 million yen (up 20.8%). Total consolidated orders received rose 1.4% to 96,367 million yen. Net sales of completed construction contracts decreased 7.1% for this fiscal year, compared with the fiscal year ended March 31, 2025 in which they increased significantly by over 10.0 billion yen (14.3%); although large-scale projects in progress decreased, construction carried forward exceeded the previous fiscal year and remained at a high level.
Segment Results
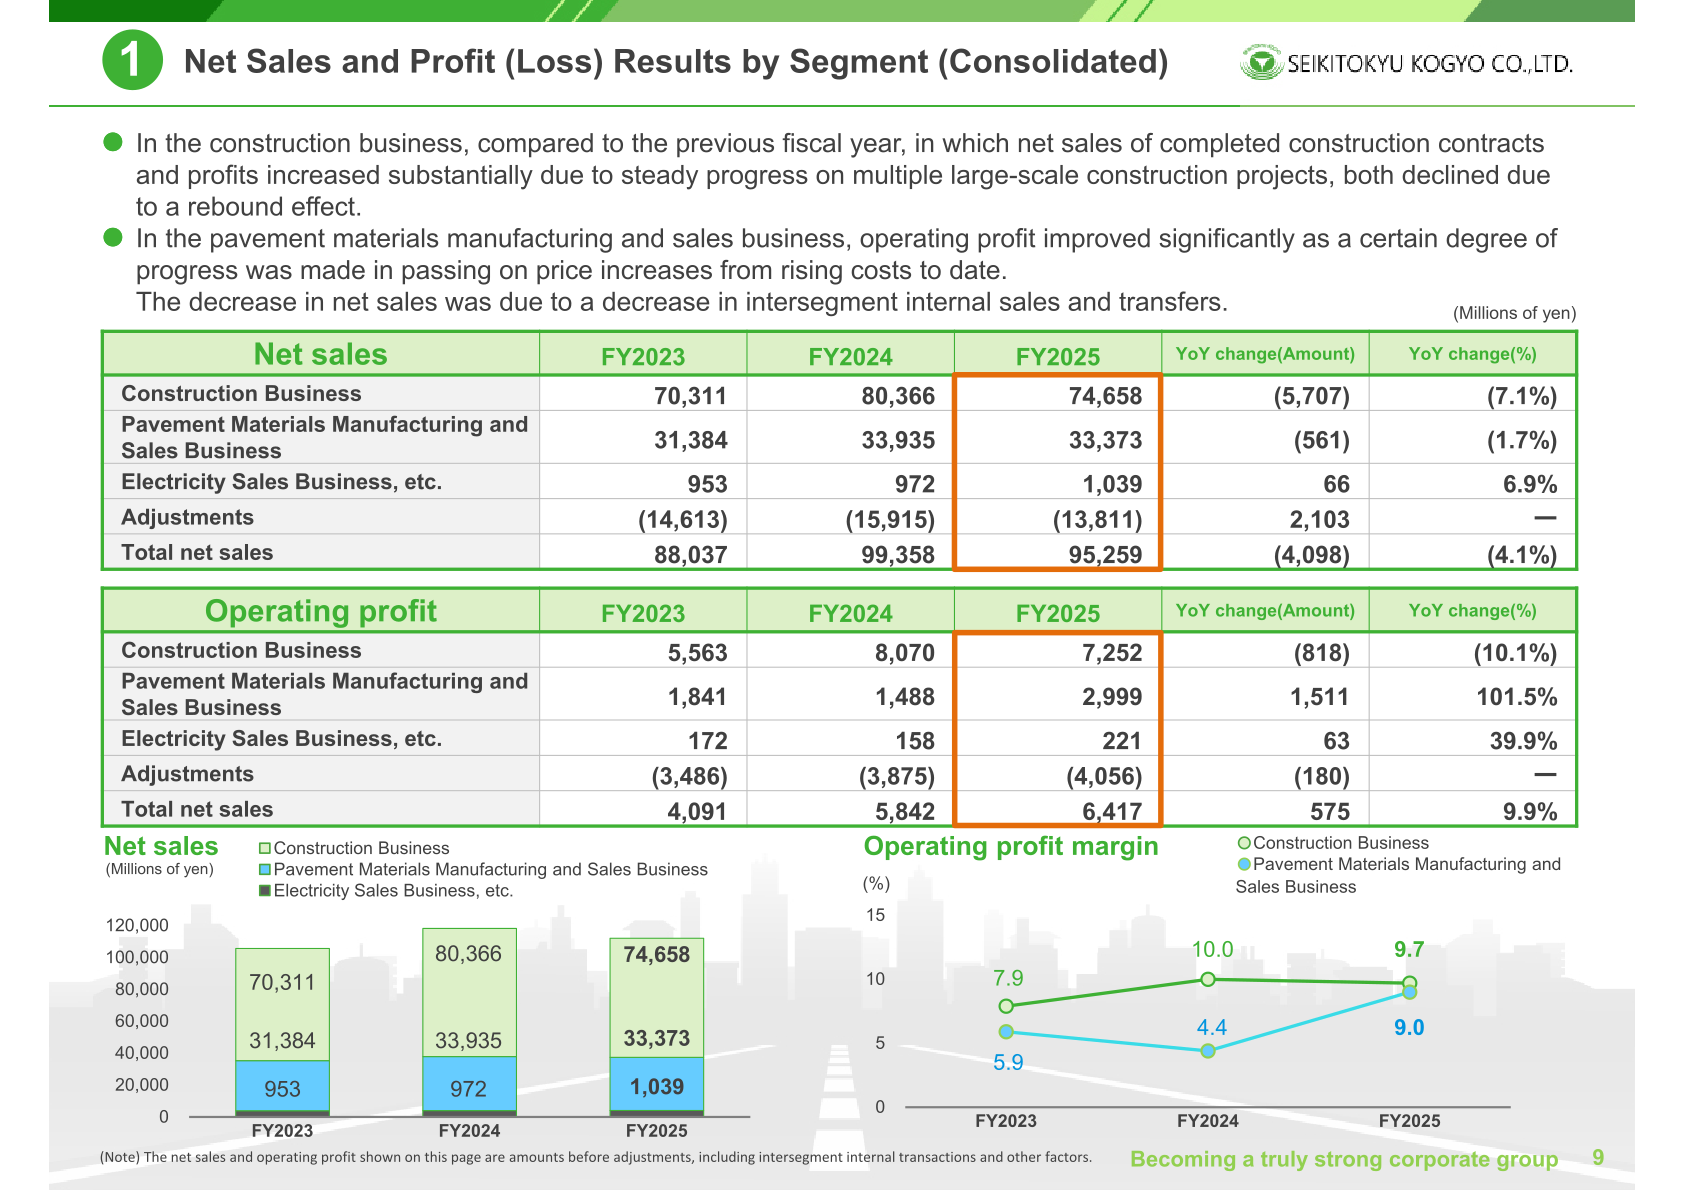
In the construction business, compared to the previous fiscal year, in which net sales of completed construction contracts and profits increased substantially due to steady progress on multiple large-scale construction projects, both declined due to a rebound effect. In the pavement materials manufacturing and sales business, operating profit improved significantly as a certain degree of progress was made in passing on price increases from rising costs to date. The decrease in net sales was due to a decrease in intersegment internal sales and transfers. The figures below are amounts before adjustments, including intersegment internal transactions and other factors.
| Segment (Millions of yen) | Metric | FY2025 | FY2024 | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|---|
| Construction Business | Net sales | 74,658 | 80,366 | (5,707) | (7.1%) |
| Pavement Materials Manufacturing and Sales Business | Net sales | 33,373 | 33,935 | (561) | (1.7%) |
| Electricity Sales Business, etc. | Net sales | 1,039 | 972 | 66 | 6.9% |
| Adjustments | Net sales | (13,811) | (15,915) | 2,103 | ー |
| Total | Net sales | 95,259 | 99,358 | (4,098) | (4.1%) |
| Construction Business | Operating profit | 7,252 | 8,070 | (818) | (10.1%) |
| Pavement Materials Manufacturing and Sales Business | Operating profit | 2,999 | 1,488 | 1,511 | 101.5% |
| Electricity Sales Business, etc. | Operating profit | 221 | 158 | 63 | 39.9% |
| Adjustments | Operating profit | (4,056) | (3,875) | (180) | ー |
| Total | Operating profit | 6,417 | 5,842 | 575 | 9.9% |
In non-consolidated construction work orders received, orders from the public sector decreased 9.3% to 23,121 million yen as orders for large-scale projects such as expressways were sluggish, although construction orders for U.S. military-related construction remained strong. Orders from the private sector, which the company is focusing on to strengthen the foundations of business offices, grew 4.6% to 47,160 million yen, of which Tokyu Group accounted for 2,646 million yen. In the product business, production volume of asphalt composites was 1,567 kilotons and sales volume was 1,226 kilotons, with total net sales of finished goods up 7.3% to 20,796 million yen.
Financial Position and Cash Flows
Total assets stood at 84,530 million yen as of March 31, 2026, up 1,973 million yen, and net assets were 44,215 million yen, up 2,522 million yen. The equity ratio improved to 52.3% from 50.5%, and interest-bearing debt was 6,605 million yen. Net cash provided by operating activities was 11,417 million yen, against negative 971 million yen in the previous fiscal year, which the company describes as a temporary phenomenon caused by an increase in trade receivables associated with a significant increase in net sales. Cash and cash equivalents at end of period were 14,437 million yen. Dividends paid were 2,929 million yen and purchase of property, plant and equipment was 1,808 million yen, including facility upgrade of plants and rebuilding offices. Refinancing was carried out for 5.0 billion yen in long-term borrowings upon maturity.
Full-Year Forecast
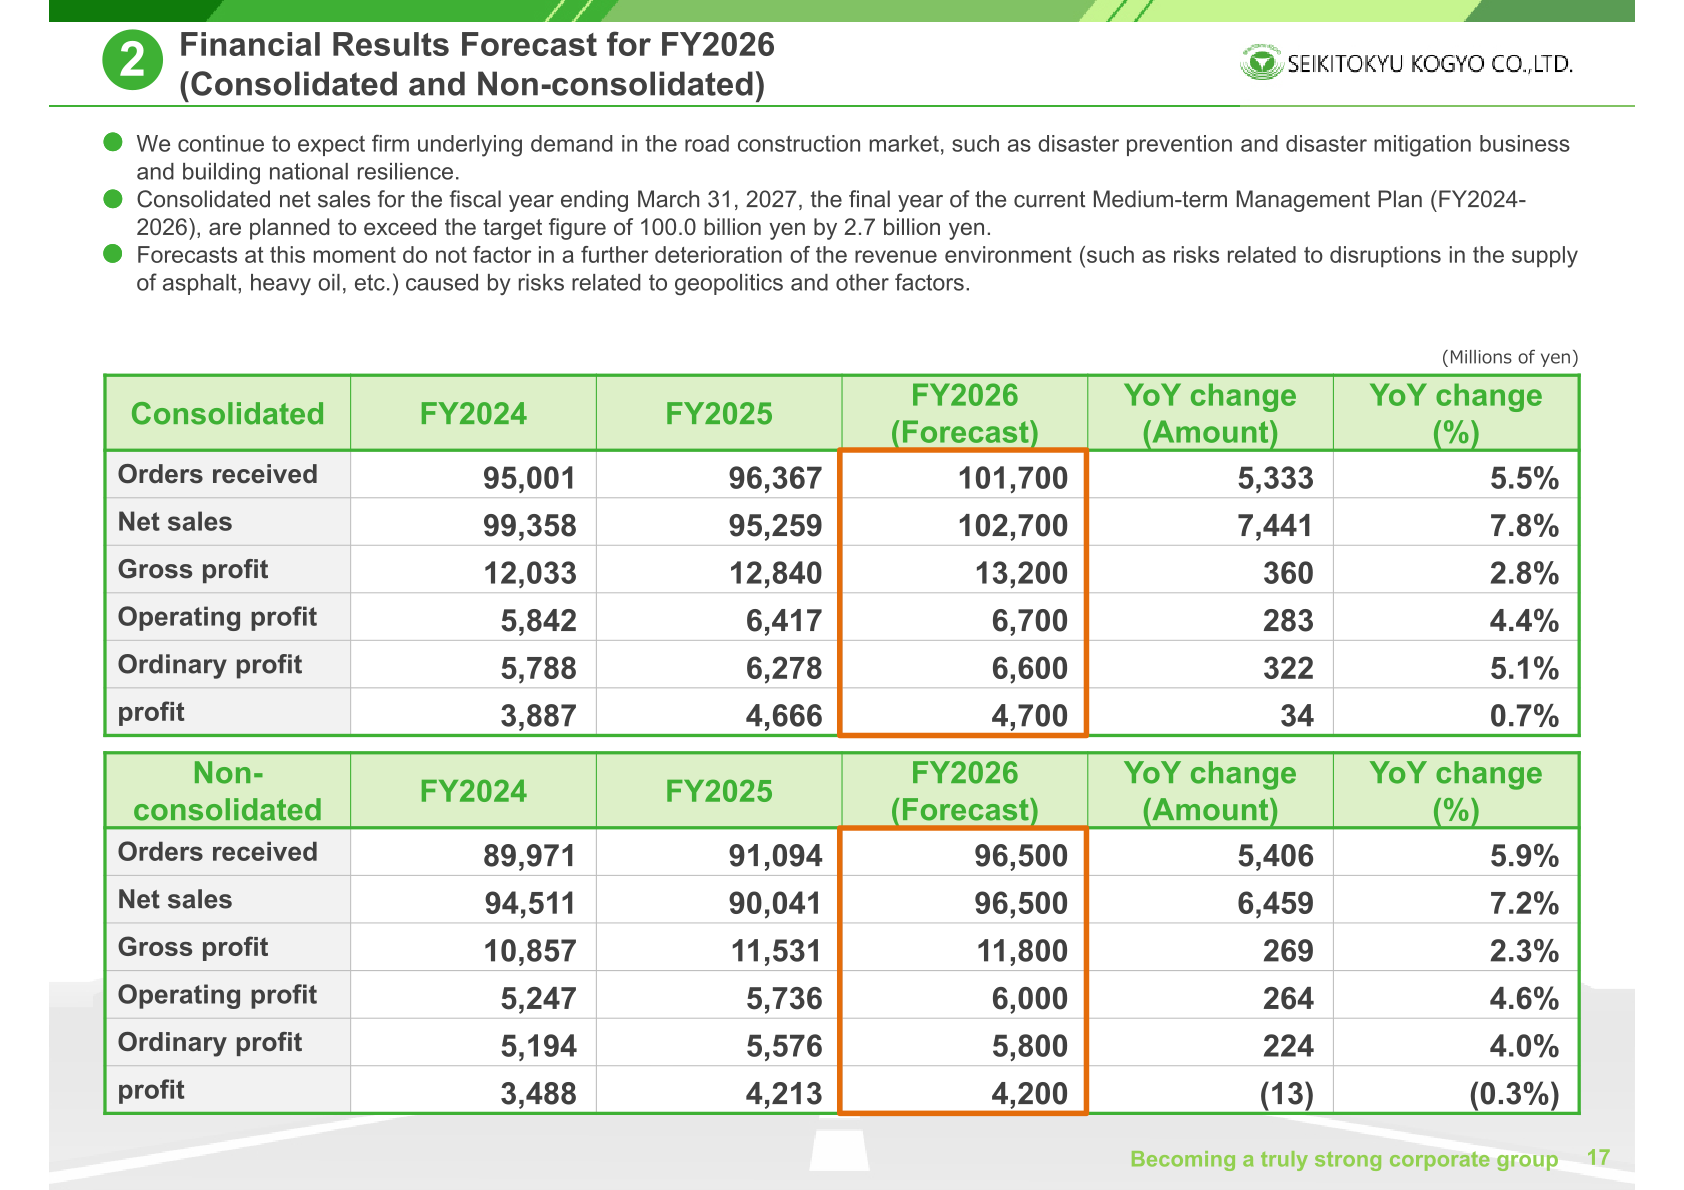
The company continues to expect firm underlying demand in the road construction market, such as disaster prevention and disaster mitigation business and building national resilience. Consolidated net sales for the fiscal year ending March 31, 2027, the final year of the current Medium-term Management Plan (FY2024-2026), are planned to exceed the target figure of 100.0 billion yen by 2.7 billion yen. Forecasts at this moment do not factor in a further deterioration of the revenue environment (such as risks related to disruptions in the supply of asphalt, heavy oil, etc.) caused by risks related to geopolitics and other factors.
| Consolidated (Millions of yen) | FY2026 (Forecast) | FY2025 | FY2024 | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|---|
| Orders received | 101,700 | 96,367 | 95,001 | 5,333 | 5.5% |
| Net sales | 102,700 | 95,259 | 99,358 | 7,441 | 7.8% |
| Gross profit | 13,200 | 12,840 | 12,033 | 360 | 2.8% |
| Operating profit | 6,700 | 6,417 | 5,842 | 283 | 4.4% |
| Ordinary profit | 6,600 | 6,278 | 5,788 | 322 | 5.1% |
| Profit | 4,700 | 4,666 | 3,887 | 34 | 0.7% |
On a non-consolidated basis the company forecasts orders received of 96,500 million yen (up 5.9%), net sales of 96,500 million yen (up 7.2%), operating profit of 6,000 million yen (up 4.6%), ordinary profit of 5,800 million yen (up 4.0%) and profit of 4,200 million yen (down 0.3%). Non-consolidated construction work orders to be received are forecast at 75,000 million yen in total, up 6.7%, comprising 24,400 million yen from the public sector and 50,600 million yen from the private sector, of which Tokyu Group accounts for 3,600 million yen.
| Segment (Millions of yen) | Metric | FY2026 (Forecast) | FY2025 | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|---|
| Construction Business | Net sales | 81,100 | 74,658 | 6,442 | 8.6% |
| Pavement Materials Manufacturing and Sales Business | Net sales | 34,500 | 33,373 | 1,127 | 3.4% |
| Electricity Sales Business, etc. | Net sales | 1,100 | 1,039 | 61 | 5.9% |
| Adjustments | Net sales | (14,000) | (13,811) | (189) | ー |
| Total | Net sales | 102,700 | 95,259 | 7,441 | 7.8% |
| Construction Business | Operating profit | 7,800 | 7,252 | 548 | 7.6% |
| Pavement Materials Manufacturing and Sales Business | Operating profit | 2,800 | 2,999 | (199) | (6.6%) |
| Electricity Sales Business, etc. | Operating profit | 200 | 221 | (21) | (9.5%) |
| Adjustments | Operating profit | (4,100) | (4,056) | (44) | ー |
| Total | Operating profit | 6,700 | 6,417 | 283 | 4.4% |
In the construction business, net sales of completed construction contracts are expected to exceed the previous fiscal year, backed by extensive construction works in progress and a solid order environment. In terms of profit, although the company expects increases in costs and expenses due to rising costs and human resources investment, it will seek to secure profits through thorough implementation of measures to prevent loss of profits. In the pavement materials manufacturing and sales business, crude oil prices remain unstable due to escalating tensions in the Middle East, but the company will continue to strive to realize selling prices reflecting manufacturing and transportation costs, to secure sales volume, and improve manufacturing efficiency.
Shareholder Returns
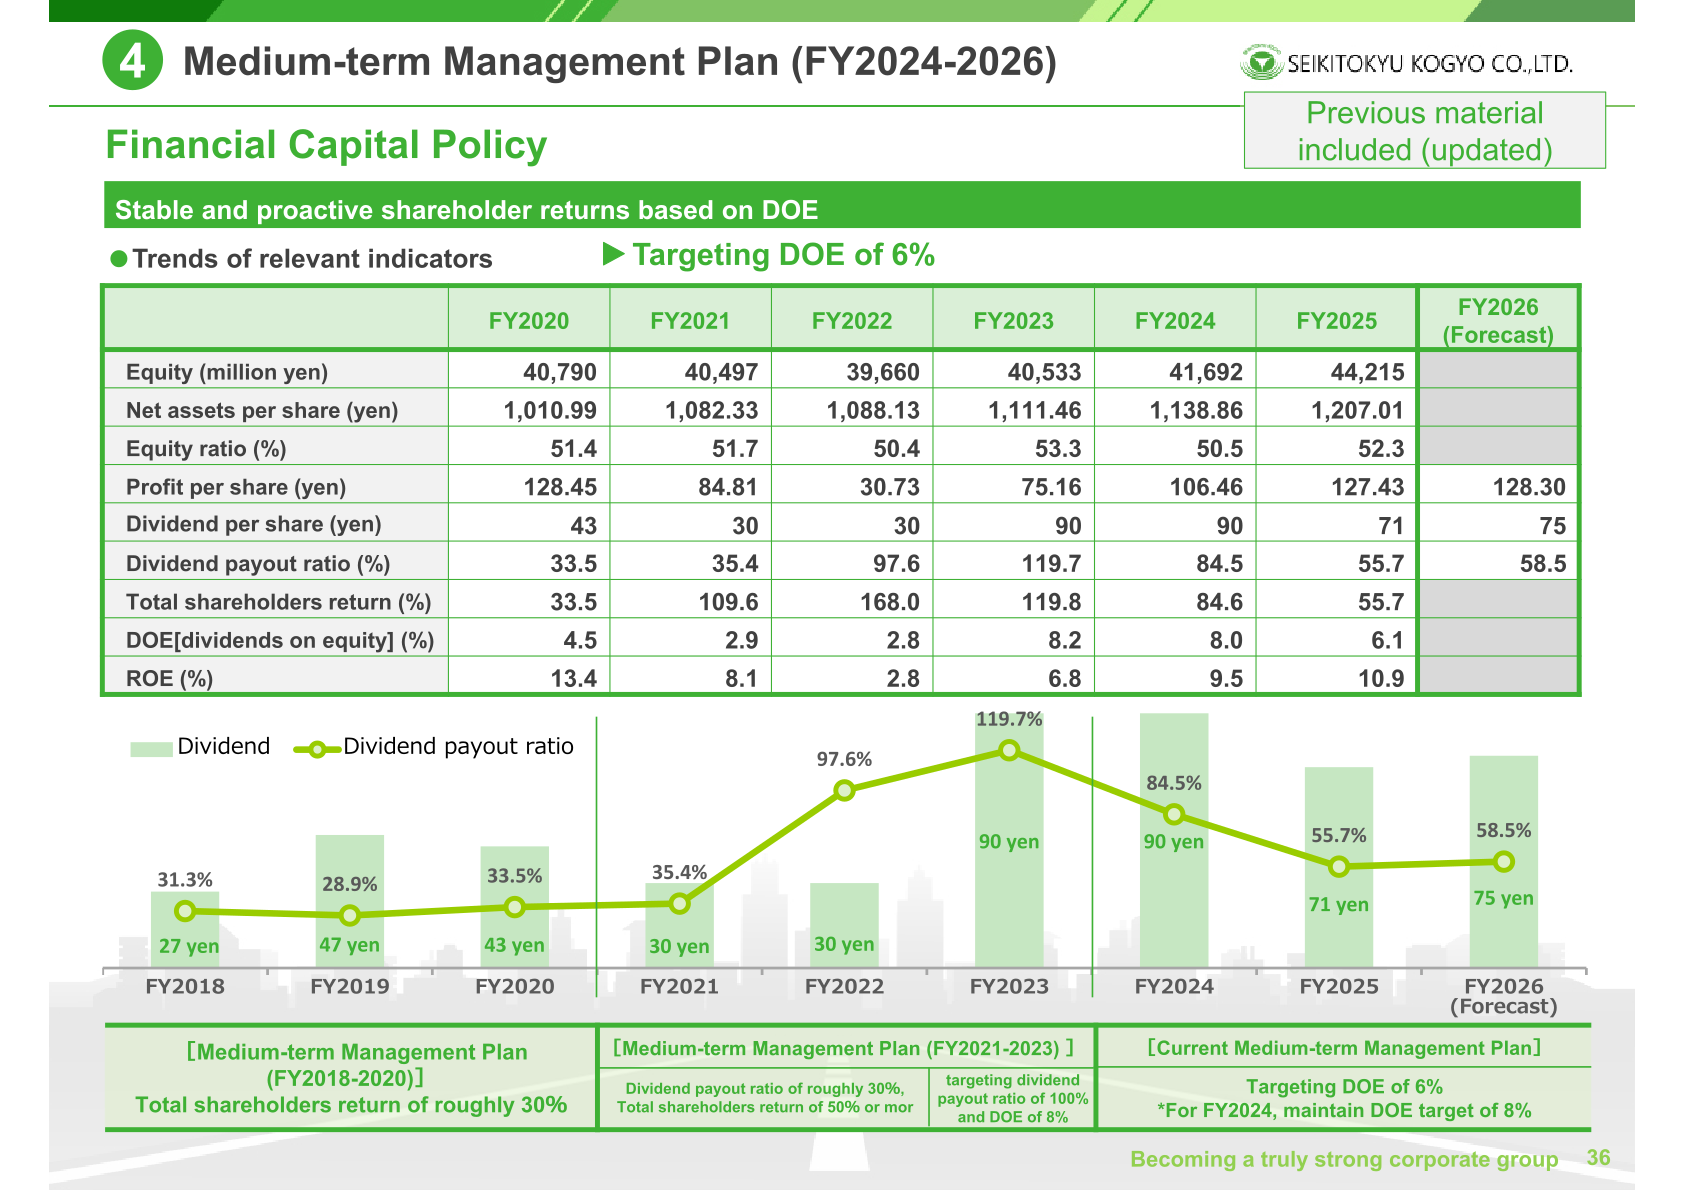
Under the current Medium-term Management Plan (FY2024-2026), the company targets stable and proactive shareholder returns based on DOE, with a target of DOE of 6% from FY2024 (for FY2024, the DOE target of 8% was maintained), in the absence of unexpected demand for considerable funds or a marked change in the environment. The dividend per share for FY2025 was 71 yen, with a dividend payout ratio of 55.7% and DOE of 6.1%, and the forecast dividend for FY2026 is 75 yen with a payout ratio of 58.5%.
| Item | FY2026 (Forecast) | FY2025 | FY2024 | FY2023 |
|---|---|---|---|---|
| Dividend per share (yen) | 75 | 71 | 90 | 90 |
| Dividend payout ratio (%) | 58.5 | 55.7 | 84.5 | 119.7 |
| Total shareholders return (%) | – | 55.7 | 84.6 | 119.8 |
| DOE [dividends on equity] (%) | – | 6.1 | 8.0 | 8.2 |
| Profit per share (yen) | 128.30 | 127.43 | 106.46 | 75.16 |
| Net assets per share (yen) | – | 1,207.01 | 1,138.86 | 1,111.46 |
| Equity (million yen) | – | 44,215 | 41,692 | 40,533 |
| Equity ratio (%) | – | 52.3 | 50.5 | 53.3 |
| ROE (%) | 10.4 | 10.9 | 9.5 | 6.8 |
Medium-Term Plan and Capital Policy
Against the FY2026 plan announced in May 2024 (net sales of 100.0 billion yen, operating profit of 6.0 billion yen, profit of 4.0 billion yen, ROE of 9.5% and an equity ratio of approx. 50%), FY2025 actual results were net sales of 95.2 billion yen, operating profit of 6.4 billion yen, profit of 4.6 billion yen, ROE of 10.9% and an equity ratio of 52.3%. The company states that both the FY2026 ROE target of 9.5% and the FY2030 ROE target of 10.0% were achieved ahead of schedule in FY2024 and FY2025 respectively. Shareholders’ equity cost is calculated at 6.4%-8.0% on a CAPM basis, using a risk-free rate of 2.0%-3.0%, a risk premium of 5.5%-6.0% and a beta of 0.64-1.01.
On capital allocation for FY2024-2026, against the initial plan of 10.5 billion yen of capital expenditure, 1.5 billion yen of strategic investments, 1.5 billion yen of R&D expenses and 8.5 billion yen of dividends, the current forecast is 6.0 billion yen of capital expenditure, 0.6 billion yen of strategic investments, 1.5 billion yen of R&D expenses and 8.8 billion yen of dividends. The company explains that as a result of revising (postponing) the timing of major plant renewals and other factors, the three-year cumulative capital investment during the Medium-term Management Plan period is expected to be lower than the initial plan, while the investment plan through 2030 remains unchanged. Targets include an equity ratio of approximately 50% and a DE ratio of less than 0.3, and maintaining a credit rating at an equivalent BBB+ as a benchmark for financial soundness.
Topics
The company acquired shares of General Act Co., Ltd. (Takasaki City, Gunma Prefecture) as a wholly owned subsidiary and entered the recycling business for agricultural plastic waste, processing the recycled raw materials as an additive to develop a highly durable asphalt mixture called “α Strong.” It also revised its HR system with a transition to the new system from April 2026, and was selected for the first time as a 2026 Outstanding Organization of the KENKO Investment for Health Program (Large Enterprise Category) on March 9, 2026. During the fiscal year the company sold two issues of strategic shareholdings and completed the disposition of all strategic shareholdings, leaving a balance of 0 as of March 31, 2026, and recorded extraordinary income of 174 million yen from the gain on sale of investment securities. In connection with the refinancing of 5.0 billion yen in long-term borrowings, a syndicated loan origination fee of 118 million yen was recorded.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















