
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
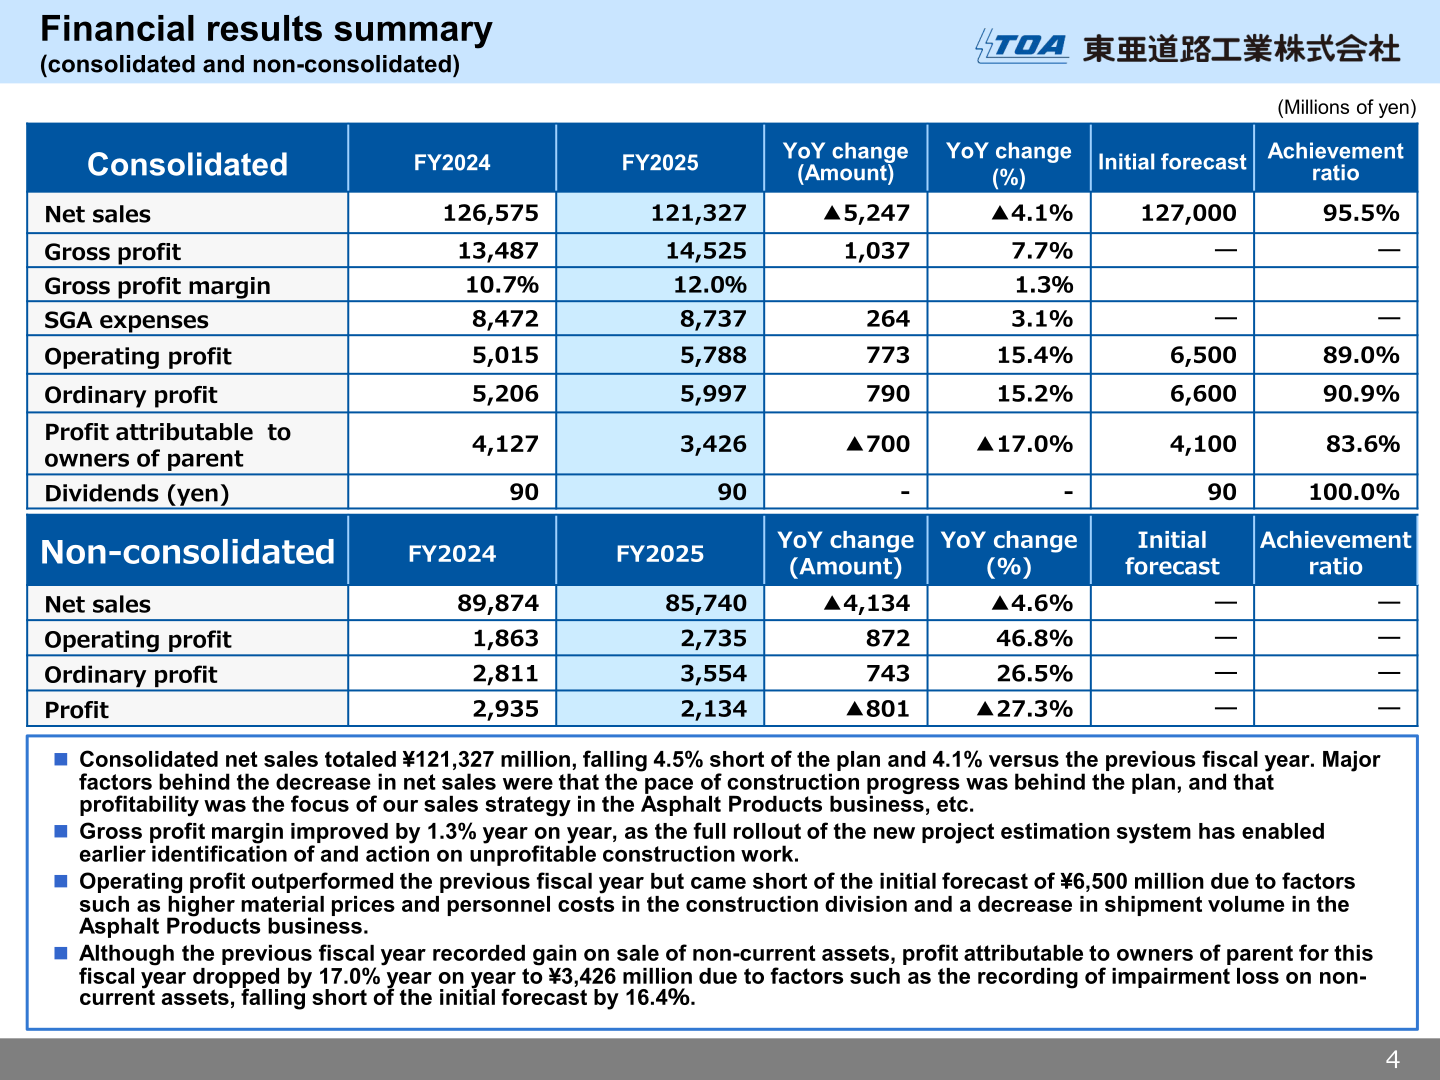
TOA ROAD CORPORATION (Prime Market of the Tokyo Stock Exchange, 1882) reported lower sales but higher operating and ordinary profit for FY2025, the fiscal year ended March 31, 2026. Consolidated net sales fell 4.1% year on year to ¥121,327 million, while operating profit rose 15.4% to ¥5,788 million and ordinary profit rose 15.2% to ¥5,997 million on a 1.3 point improvement in the gross profit margin to 12.0%. Profit attributable to owners of parent declined 17.0% to ¥3,426 million, reflecting the absence of the prior year’s gain on sale of non-current assets and the recording of impairment loss on non-current assets. The annual dividend was ¥90 per share, unchanged year on year and in line with the initial forecast.
Consolidated Results (Full-Year Actual)
The company states that net sales fell 4.5% short of the plan and 4.1% versus the previous fiscal year, mainly because the pace of construction progress was behind plan and because profitability was the focus of its sales strategy in the Asphalt Products business. The gross profit margin improved by 1.3% year on year as the full rollout of the new project estimation system enabled earlier identification of and action on unprofitable construction work. Operating profit outperformed the previous fiscal year but came short of the initial forecast of ¥6,500 million due to factors such as higher material prices and personnel costs in the construction division and a decrease in shipment volume in the Asphalt Products business. On a non-consolidated basis, net sales were ¥85,740 million (▲4.6%), operating profit ¥2,735 million (+46.8%), ordinary profit ¥3,554 million (+26.5%) and profit ¥2,134 million (▲27.3%).
| Consolidated (Millions of yen) | FY2024 | FY2025 | YoY change (Amount) | YoY change (%) | Initial forecast | Achievement ratio |
|---|---|---|---|---|---|---|
| Net sales | 126,575 | 121,327 | ▲5,247 | ▲4.1% | 127,000 | 95.5% |
| Gross profit | 13,487 | 14,525 | 1,037 | 7.7% | ― | ― |
| Gross profit margin | 10.7% | 12.0% | 1.3% | ― | ― | ― |
| SGA expenses | 8,472 | 8,737 | 264 | 3.1% | ― | ― |
| Operating profit | 5,015 | 5,788 | 773 | 15.4% | 6,500 | 89.0% |
| Ordinary profit | 5,206 | 5,997 | 790 | 15.2% | 6,600 | 90.9% |
| Profit attributable to owners of parent | 4,127 | 3,426 | ▲700 | ▲17.0% | 4,100 | 83.6% |
| Dividends (yen) | 90 | 90 | – | – | 90 | 100.0% |
On the balance sheet, total assets decreased 2.4% year on year to ¥88,501 million and total liabilities decreased 1.0% to ¥33,441 million, with interest-bearing liabilities down ¥1,266 million to ¥4,633 million. Net assets fell 3.3% to ¥55,059 million as retained earnings were increased by profit attributable to owners of parent but decreased by dividends of surplus, and the equity-to-asset ratio was 60.6%, down 0.5 points. Cash flows from operating activities were ¥12,205 million, investing activities ▲¥2,331 million and financing activities ▲¥8,271 million, leaving cash and cash equivalents at the end of the period at ¥13,909 million, an increase of ¥1,601 million year on year.
Segment Results
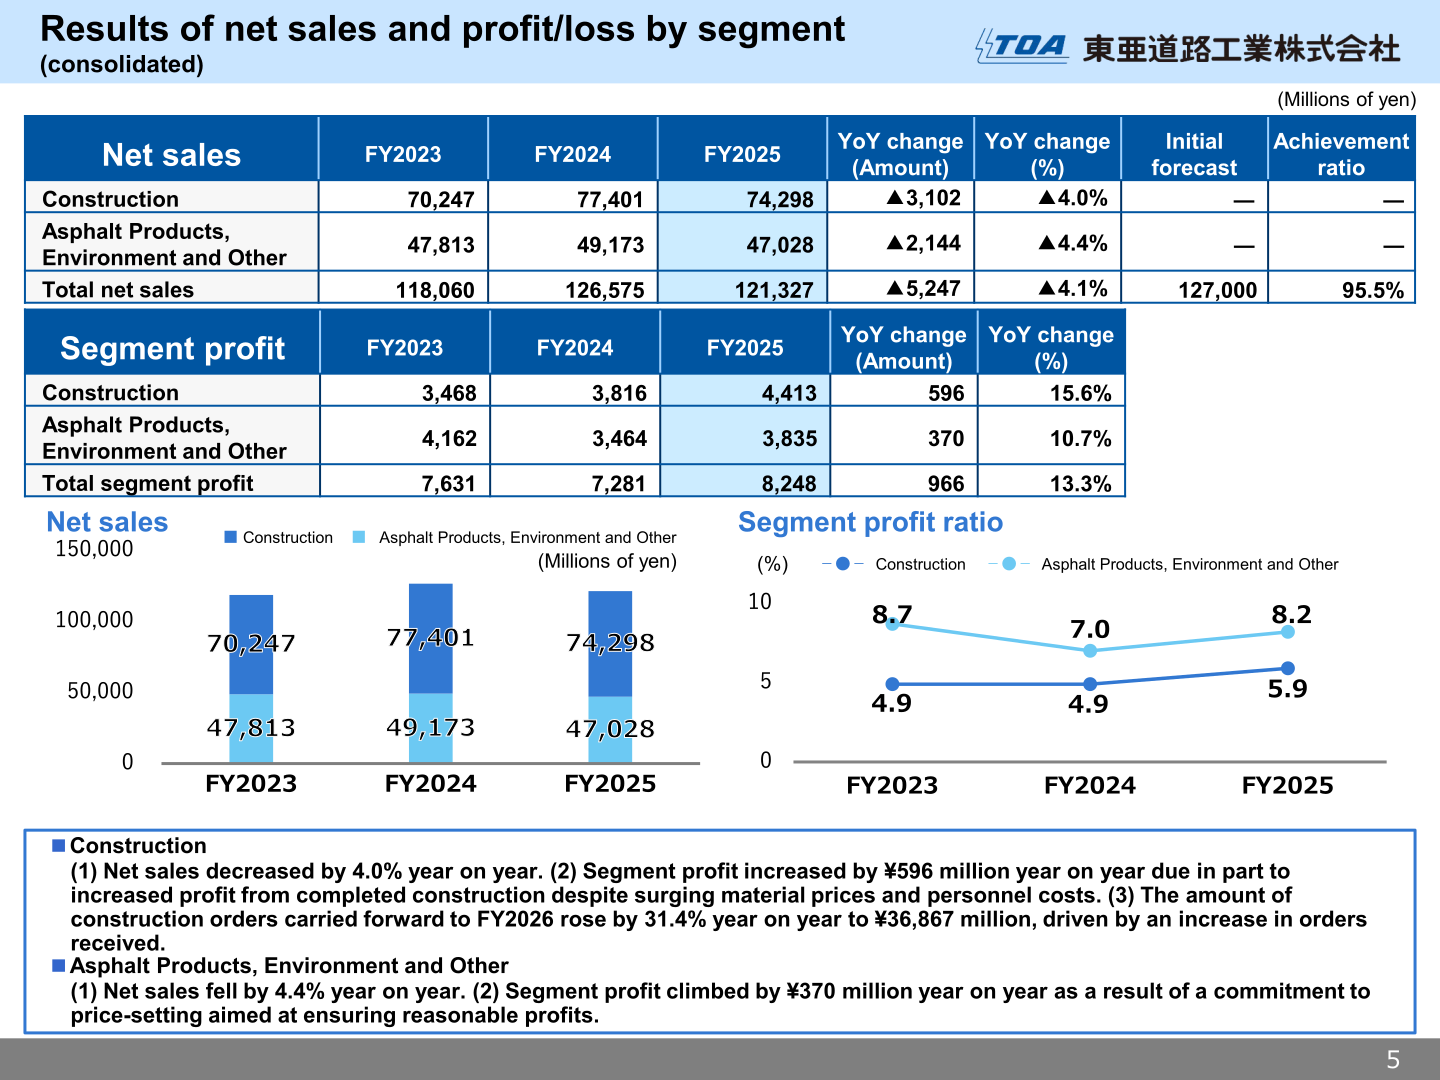
In Construction, net sales decreased 4.0% year on year while segment profit increased ¥596 million due in part to increased profit from completed construction despite surging material prices and personnel costs. The amount of construction orders carried forward to FY2026 rose 31.4% year on year, driven by an increase in orders received. In Asphalt Products, Environment and Other, net sales fell 4.4% year on year while segment profit climbed ¥370 million as a result of a commitment to price-setting aimed at ensuring reasonable profits. Total segment profit rose 13.3% to ¥8,248 million.
| Segment (Millions of yen) | Metric | FY2023 | FY2024 | FY2025 | YoY change (%) |
|---|---|---|---|---|---|
| Construction | Net sales | 70,247 | 77,401 | 74,298 | ▲4.0% |
| Asphalt Products, Environment and Other | Net sales | 47,813 | 49,173 | 47,028 | ▲4.4% |
| Total | Net sales | 118,060 | 126,575 | 121,327 | ▲4.1% |
| Construction | Segment profit | 3,468 | 3,816 | 4,413 | 15.6% |
| Asphalt Products, Environment and Other | Segment profit | 4,162 | 3,464 | 3,835 | 10.7% |
| Total | Segment profit | 7,631 | 7,281 | 8,248 | 13.3% |
Orders received rose 8.8% year on year to ¥130,134 million, with pavement construction up 14.9% to ¥66,427 million and civil engineering up 31.7% to ¥16,677 million, while Asphalt Products, Environment and Other declined 4.4% to ¥47,028 million. The balance of orders carried forward increased 31.4% to ¥36,864 million, comprising pavement construction of ¥27,587 million (+39.9%) and civil engineering of ¥9,276 million (+11.3%).
| Orders (Millions of yen) | FY2024 | FY2025 | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|
| Orders received: Pavement construction | 57,809 | 66,427 | 8,618 | 14.9 |
| Orders received: Civil engineering | 12,659 | 16,677 | 4,018 | 31.7 |
| Orders received: Asphalt Products, Environment and Other | 49,173 | 47,028 | ▲2,144 | ▲4.4 |
| Orders received: Total | 119,642 | 130,134 | 10,491 | 8.8 |
| Balance of orders carried forward: Pavement construction | 19,720 | 27,587 | 7,867 | 39.9 |
| Balance of orders carried forward: Civil engineering | 8,337 | 9,276 | 938 | 11.3 |
| Balance of orders carried forward: Total | 28,057 | 36,864 | 8,806 | 31.4 |
FY2026 Forecast
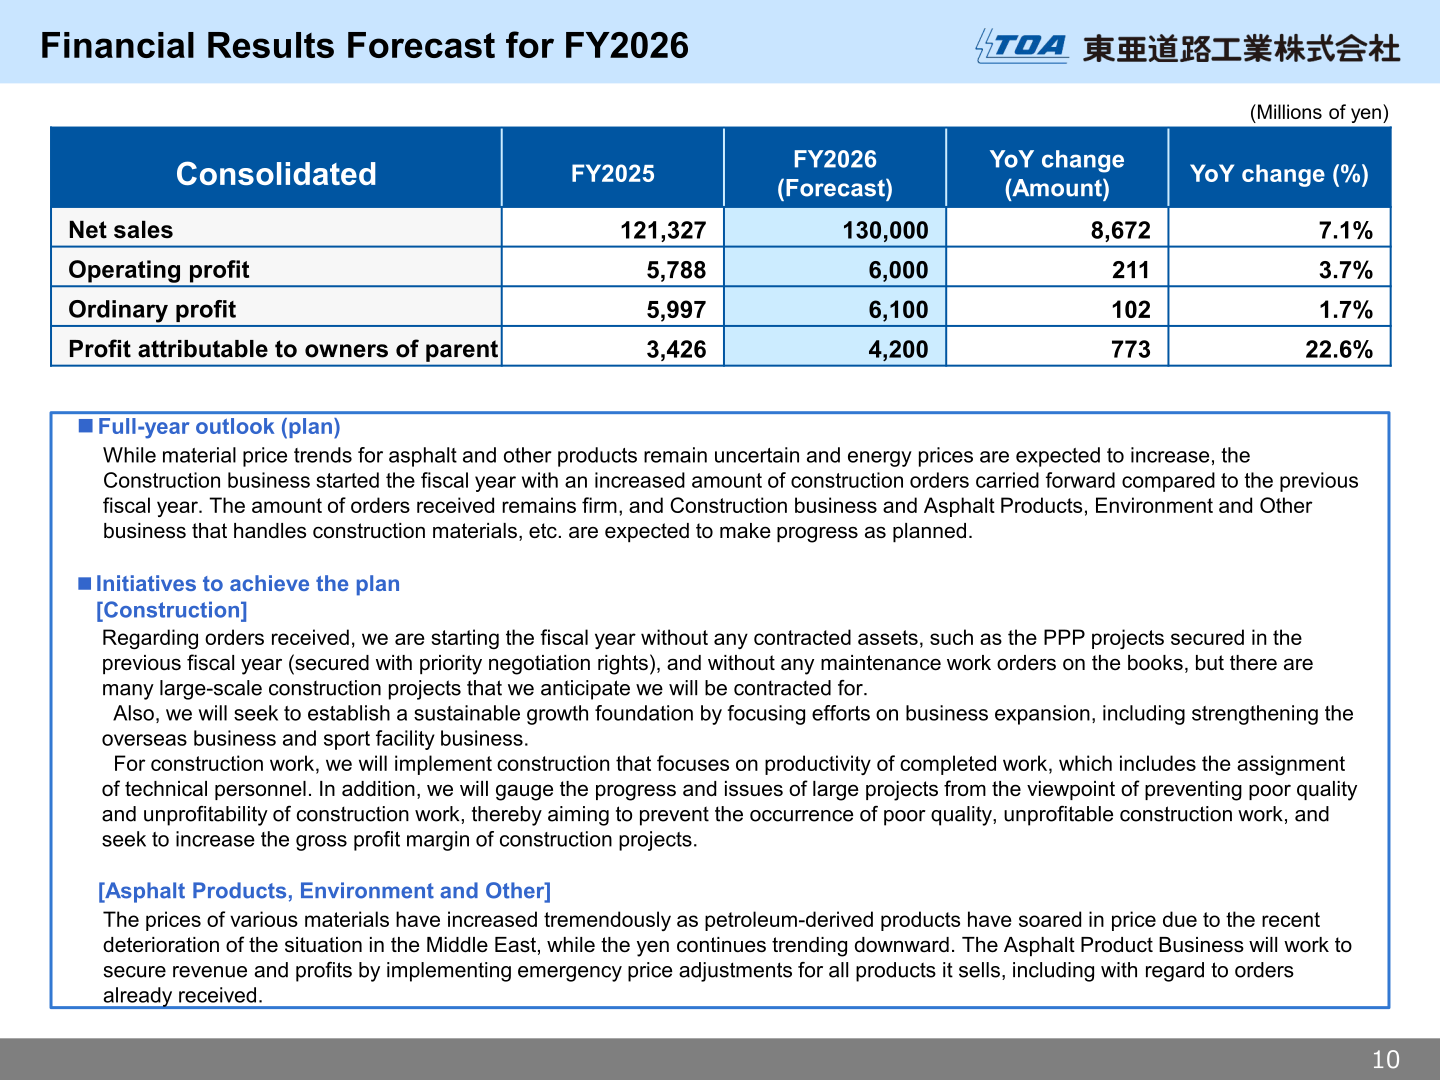
For FY2026, the fiscal year ending March 31, 2027, the company forecasts consolidated net sales of ¥130,000 million (+7.1%), operating profit of ¥6,000 million (+3.7%), ordinary profit of ¥6,100 million (+1.7%) and profit attributable to owners of parent of ¥4,200 million (+22.6%). The company notes that while material price trends for asphalt and other products remain uncertain and energy prices are expected to increase, the Construction business started the fiscal year with an increased amount of construction orders carried forward compared with the previous fiscal year, orders received remain firm, and both the Construction business and the Asphalt Products, Environment and Other business are expected to make progress as planned. In Construction, the company begins the year without contracted assets such as the PPP projects secured in the previous fiscal year and without maintenance work orders on the books, but anticipates being contracted for many large-scale projects, and will focus on strengthening the overseas business and sport facility business. In Asphalt Products, the business will work to secure revenue and profits by implementing emergency price adjustments for all products it sells, including with regard to orders already received.
| Consolidated (Millions of yen) | FY2025 | FY2026 (Forecast) | YoY change (Amount) | YoY change (%) |
|---|---|---|---|---|
| Net sales | 121,327 | 130,000 | 8,672 | 7.1% |
| Operating profit | 5,788 | 6,000 | 211 | 3.7% |
| Ordinary profit | 5,997 | 6,100 | 102 | 1.7% |
| Profit attributable to owners of parent | 3,426 | 4,200 | 773 | 22.6% |
Shareholder Returns
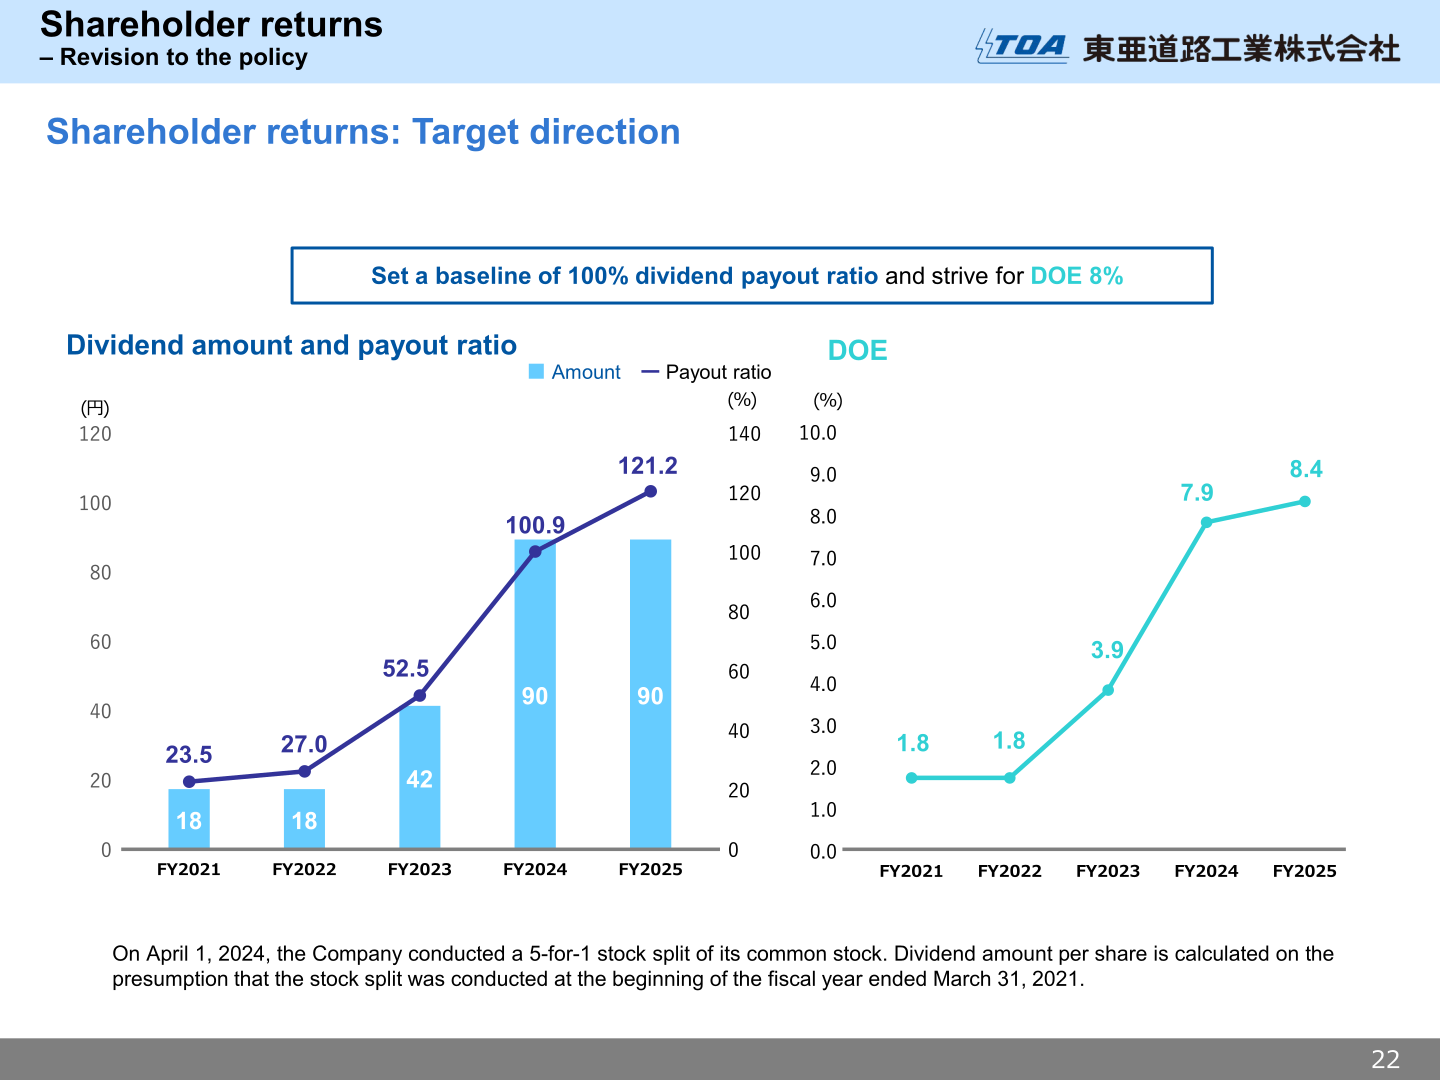
The company’s stated shareholder returns direction is to set a baseline of a 100% dividend payout ratio and strive for DOE of 8%. The dividend paid for FY2025 was ¥90 per share, giving a dividend payout ratio of 121.2% and DOE of 8.4%, compared with ¥90 per share (payout ratio 100.9%, DOE 7.9%) for FY2024 and ¥42 per share (payout ratio 52.5%, DOE 3.9%) for FY2023. Dividend amounts per share are calculated on the presumption that the 5-for-1 stock split conducted on April 1, 2024 was carried out at the beginning of the fiscal year ended March 31, 2021. The company also states that it will flexibly consider future retirement of treasury shares to further return profits to shareholders.
| Shareholder returns | FY2023 | FY2024 | FY2025 |
|---|---|---|---|
| Dividend per share (yen) | 42 | 90 | 90 |
| Dividend payout ratio (%) | 52.5 | 100.9 | 121.2 |
| DOE (%) | 3.9 | 7.9 | 8.4 |
Capital Cost and Stock Price Initiatives
ROE as of March 31, 2026 was 6.3%, which the company attributes partially to increased crude oil prices, and it will work for continuous improvement aiming at ROE of 8.0% or more under the medium-term management plan. PBR was 1.47x in the fiscal year ended March 31, 2026 (1.2x in the preceding year), above the Tokyo Stock Exchange requirement of 1.0x, and the company will strive to achieve a higher PBR by providing shareholder returns with a baseline dividend payout ratio of 100% and a target DOE of 8.0%. EPS was ¥74.24 for FY2025. On cross-shareholdings, the target is to reduce holdings to around one third of the fair value of shares held as of March 31, 2024 of ¥3.96 billion over the three years from FY2024 to FY2026; cross-shareholdings were reduced by approximately ¥0.2 billion during FY2025, but the market value recorded on the balance sheet of ¥3.21 billion as of March 31, 2026 exceeded the ¥2.76 billion level as of March 31, 2025 due to the recent rise in stock prices, and the company will accelerate the sale of shares to ensure achievement of the target.
Medium-Term Management Plan
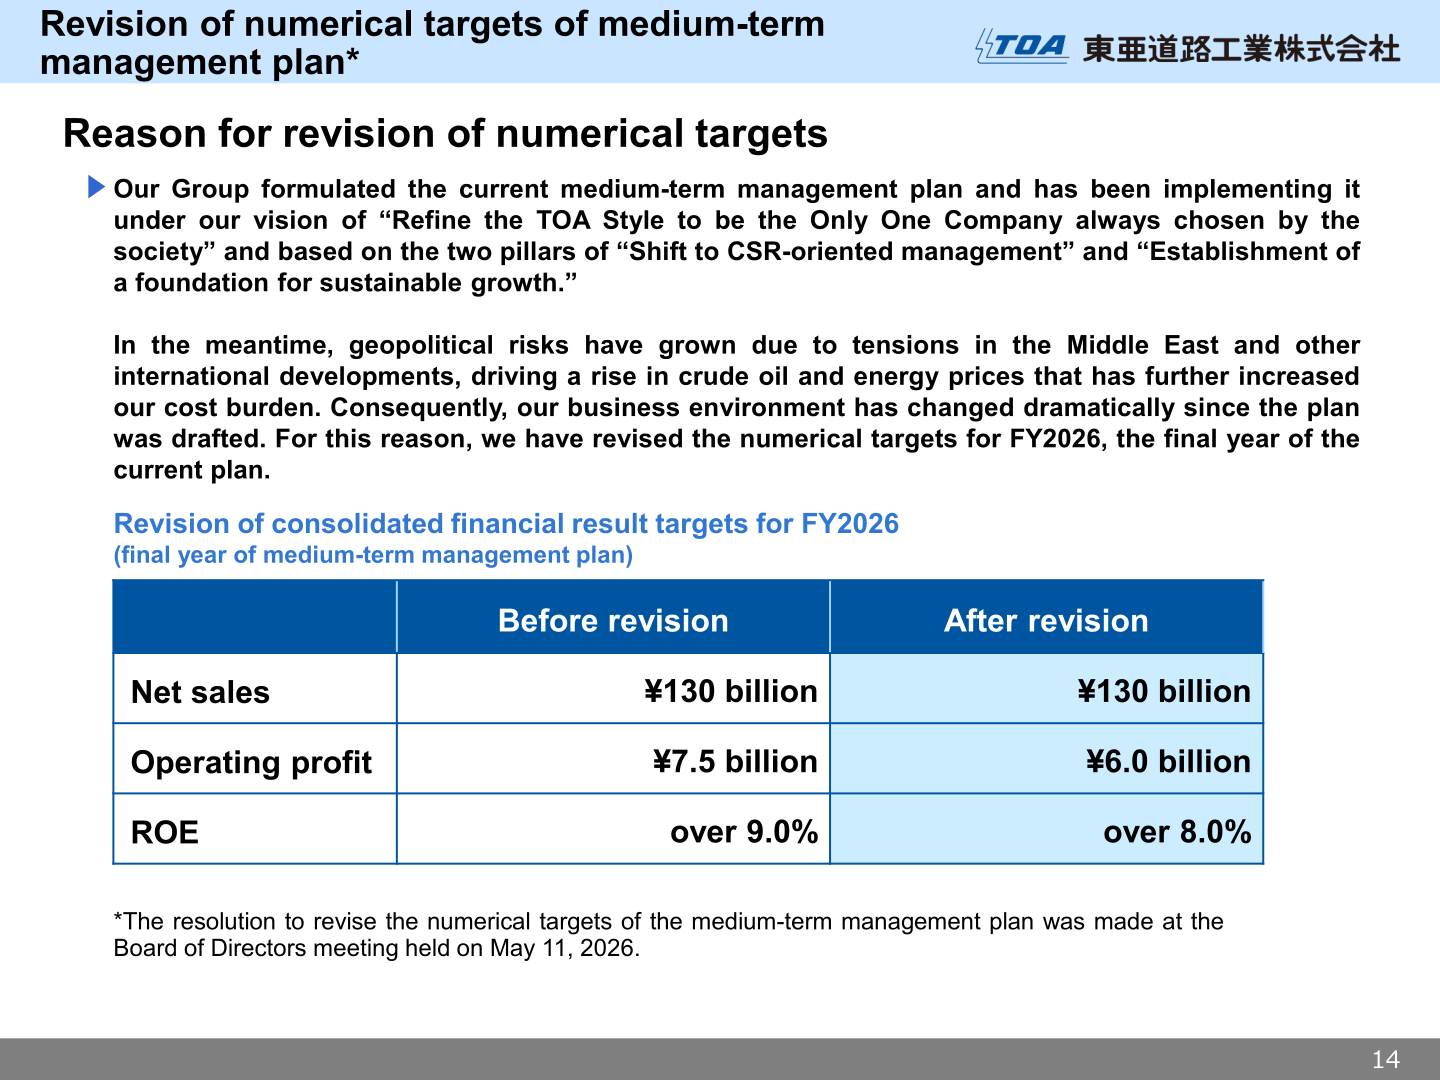
FY2025 was the second year of the FY2024–FY2026 medium-term management plan, “TOA ROAD Sustainable Plan 2026,” which is built on the two pillars of a “shift to CSR-oriented management” and “establishment of a foundation for sustainable growth.” At the Board of Directors meeting held on May 11, 2026, the company resolved to revise the numerical targets for FY2026, the final year of the plan: net sales remain at ¥130 billion, operating profit was revised from ¥7.5 billion to ¥6.0 billion, and ROE from over 9.0% to over 8.0%. The company cites growing geopolitical risks due to tensions in the Middle East and other international developments, which drove a rise in crude oil and energy prices and further increased its cost burden.
| FY2026 consolidated targets | Before revision | After revision |
|---|---|---|
| Net sales | ¥130 billion | ¥130 billion |
| Operating profit | ¥7.5 billion | ¥6.0 billion |
| ROE | over 9.0% | over 8.0% |
On capital policy, a cumulative total of approximately ¥5.6 billion had been invested as of the end of FY2025, the second year of the plan, representing 37.2% of the three-year total investment target of ¥15 billion or more (renewal of existing facilities ¥10,000 million and growth investments ¥5,000 million). Investment to date comprises existing facilities in Construction of ¥1,826 million, Asphalt Products, Environment and Other of ¥2,512 million and common items of ¥394 million (sub total ¥4,732 million), plus DX, environment and other investment of ¥842 million, for total investment of ¥5,574 million. Business strategy progress cited by the company includes ¥3.3 billion of cumulative business investment, the launch of a project for METI’s Global South demonstration program, mechanical warm-mix equipment installed at 11 plants nationwide as of March 31, 2026, and the launch of road inspections using AI camera-equipped smartphones. For FY2025 the company reported consolidated net sales of ¥121,327 million, ordinary profit of ¥5,997 million and 1,644 employees.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















