
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
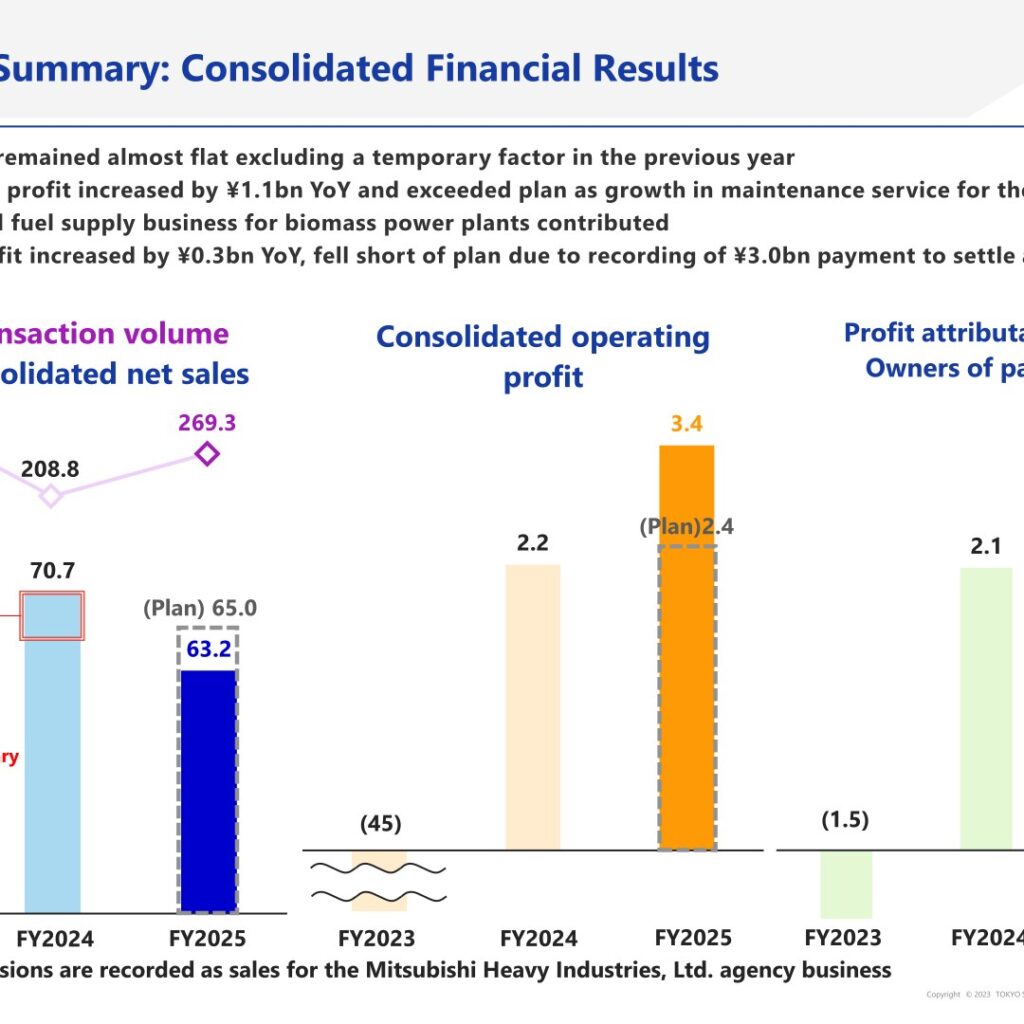
Tokyo Sangyo Co., Ltd. (8070), an integrated machinery trading company focused on the environment and energy sectors, reported consolidated net sales of ¥63.2 billion for the fiscal year ended March 31, 2026 (FY2025), down from ¥70.7 billion a year earlier, a decline the company attributes mainly to the absence of a one-off ¥6.0 billion factor recorded in the prior year. Consolidated operating profit rose ¥1.1 billion year on year to a record ¥3.4 billion, exceeding the company’s plan, on growth in maintenance services for thermal power plants and the fuel supply business for biomass power plants. Profit attributable to owners of parent increased ¥0.3 billion year on year to a record ¥2.5 billion, though this fell short of the company’s original ¥3.7 billion plan after Tokyo Sangyo recorded a ¥3.0 billion payment to settle a pending lawsuit.
Consolidated Results (Full-Year Actual)
Both operating profit and profit attributable to owners of parent reached record highs in FY2025. Net sales were roughly flat versus the prior year once the one-off ¥6.0 billion recorded in FY2024 (related to the transfer of a business license for the solar-related business) is excluded.
| Item | FY2025 | FY2024 | Change (YoY) |
|---|---|---|---|
| Transaction volume (¥bn) | 269.3 | 208.8 | — |
| Consolidated net sales (¥bn) | 63.2 | 70.7 | Roughly flat, excluding one-off ¥6.0bn factor in FY2024 (per company commentary) |
| Consolidated operating profit (¥bn) | 3.4 | 2.2 | +1.1 |
| Profit attributable to owners of parent (¥bn) | 2.5 | 2.1 | +0.3 |
Segment Results
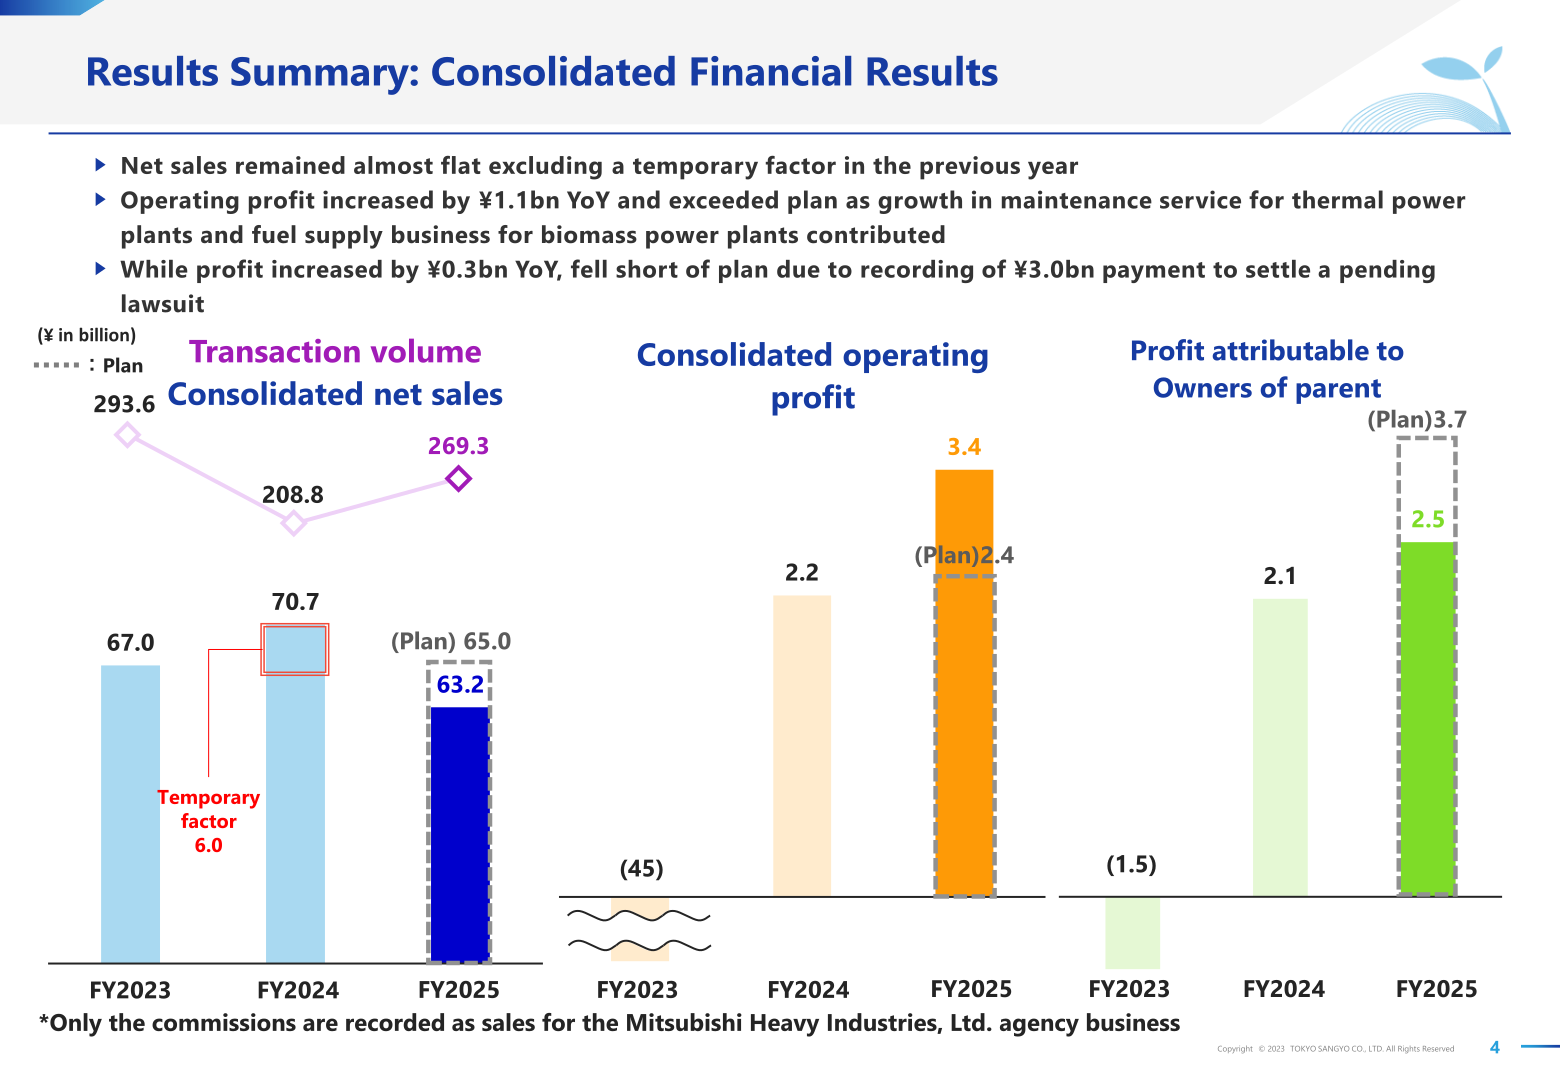
By business domain, growth in Thermal Power and Nuclear Power, etc. reflected strength in the agency business for power-generation equipment, while Renewable Energy’s profit recovery reflected the start of deliveries under all contracted biomass fuel-supply agreements and one-off income related to a solar-related construction project completed in the prior fiscal year. Net sales and profit in Production/Environmental Equipment declined mainly due to a reaction to a large-scale equipment delivery by a European subsidiary in the prior year.
| Business Domain | Metric | FY2025 | FY2024 |
|---|---|---|---|
| Thermal Power | Net sales (¥bn) | 5.4 | 4.5 |
| Thermal Power | Operating profit (¥bn, margin) | 0.90 (16.5%) | 0.55 |
| Nuclear Power, etc. | Net sales (¥bn) | 5.2 | 6.3 |
| Nuclear Power, etc. | Operating profit (¥bn, margin) | 0.73 (13.9%) | 0.81 |
| Renewable Energy | Net sales (¥bn) | 17.0 | 22.2 |
| Renewable Energy | Operating profit (¥bn, margin) | 1.20 (7.0%) | (0.32) |
| Production/Environmental Equipment | Net sales (¥bn) | 35.3* | 37.5* |
| Production/Environmental Equipment | Operating profit (¥bn, margin) | 0.58 (1.6%) | 1.21 |
*FY2024 Production/Environmental Equipment net sales include ¥6.0 billion from the transfer of a business license for the solar-related business.
On a reportable-segment basis (an alternative grouping the company also discloses): Electric Power segment net sales were ¥23.8 billion (+¥8.1 billion YoY) with operating profit of ¥2.18 billion (9.1% margin, +¥0.69 billion YoY); the Environment, Chemicals, and Electric Power Machinery segment posted net sales of ¥33.4 billion (-¥16.4 billion YoY) with operating profit of ¥0.97 billion (2.9% margin, +¥0.48 billion YoY); and the Lifestyle segment posted net sales of ¥5.9 billion (+¥0.8 billion YoY) with operating profit of ¥0.27 billion (4.5% margin, +¥0.05 billion YoY).
| Segment | Net Sales FY2025 (¥bn) | Net Sales YoY (¥bn) | Operating Profit FY2025 (¥bn, margin) | Operating Profit YoY (¥bn) |
|---|---|---|---|---|
| Electric Power | 23.8 | +8.1 | 2.18 (9.1%) | +0.69 |
| Environment, Chemicals, and Electric Power Machinery | 33.4 | (16.4) | 0.97 (2.9%) | +0.48 |
| Lifestyle | 5.9 | +0.8 | 0.27 (4.5%) | +0.05 |
FY2026 Forecast
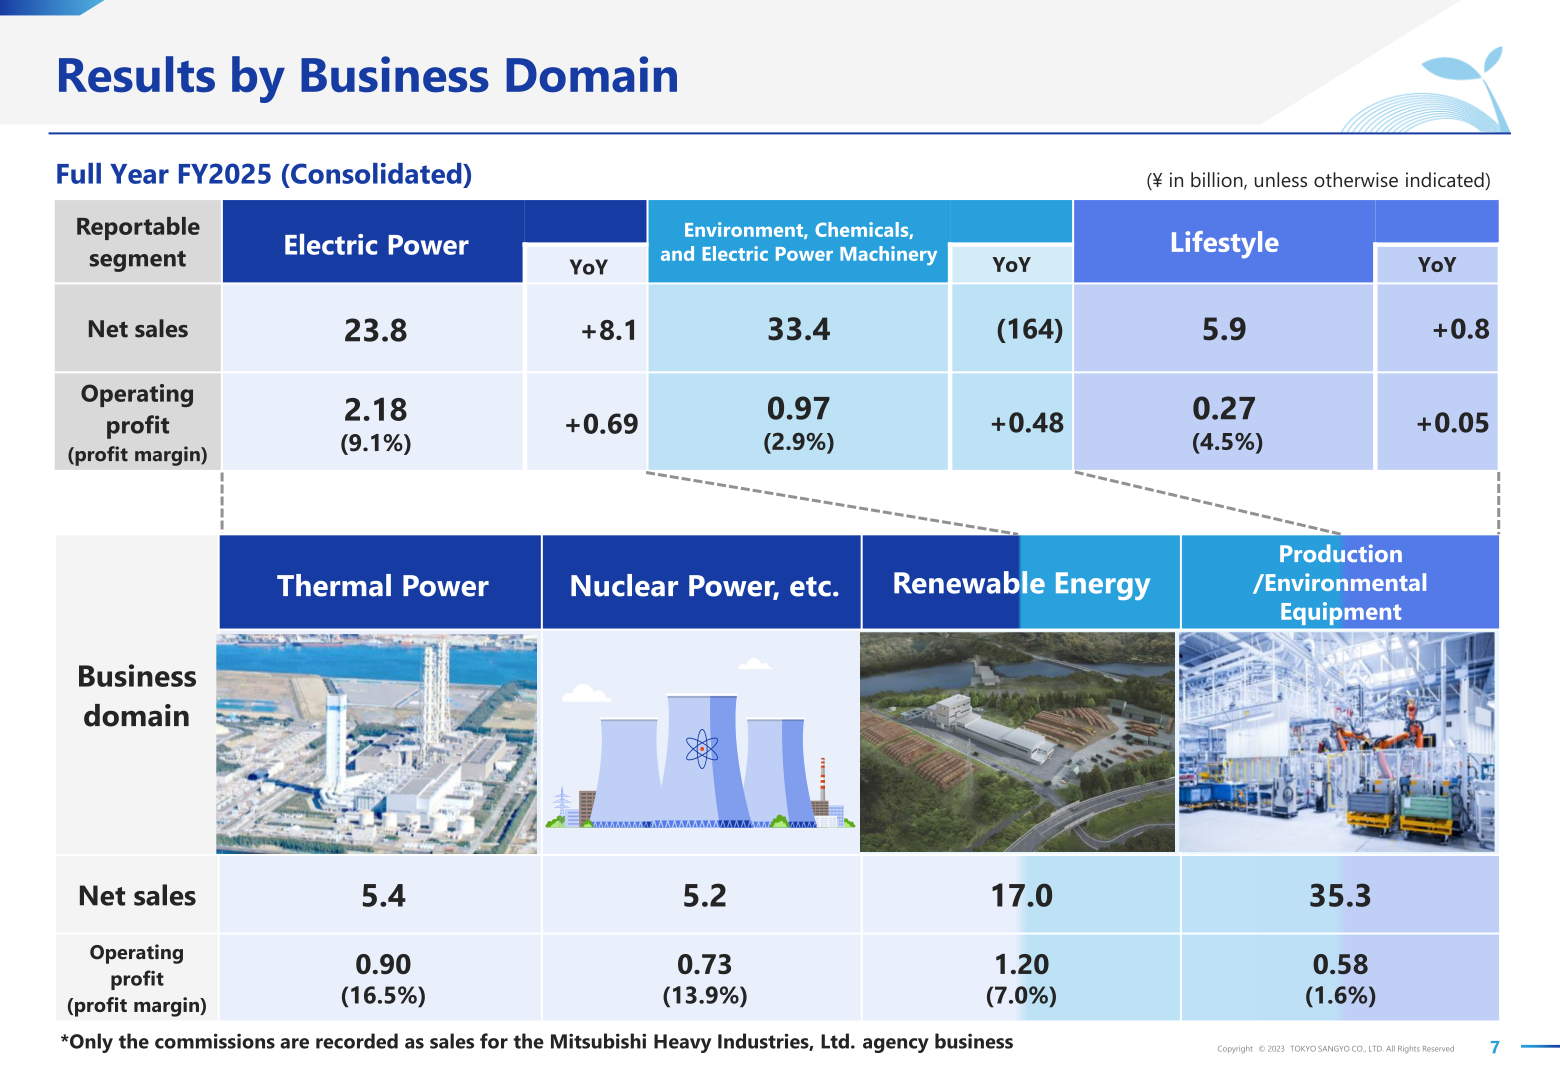
For the fiscal year ending March 31, 2027 (FY2026), Tokyo Sangyo forecasts consolidated net sales of ¥63.0 billion (down ¥0.2 billion from FY2025), consolidated operating profit of ¥2.5 billion (down ¥0.9 billion), and consolidated profit of ¥1.7 billion (down ¥0.8 billion). On the operating profit bridge from the FY2025 result of ¥3.4 billion: a ¥0.6 billion decline reflects the absence of one-off items recorded in FY2025 (a refund of costs related to a large-scale solar-related construction contracting work and a reversal of an allowance for doubtful accounts); a further ¥0.4 billion decline reflects the completion of multiple large-scale production-related construction contracting works and the absence of last-minute demand in the packaging materials business linked to the Middle East situation; and personnel expenses are expected to reduce profit by a further ¥0.4 billion. These declines are expected to be partially offset by ¥0.5 billion of profit growth from the equipment supply business within the Production/Environmental Equipment domain, resulting in an FY2026 operating profit plan of ¥2.5 billion.
| Item | FY2026 Forecast (¥bn) | FY2025 (Actual, ¥bn) | Change |
|---|---|---|---|
| Consolidated net sales | 63.0 | 63.2 | (0.2) |
| Consolidated operating profit | 2.5 | 3.4 | (0.9) |
| Consolidated profit | 1.7 | 2.5 | (0.8) |
Shareholder Returns
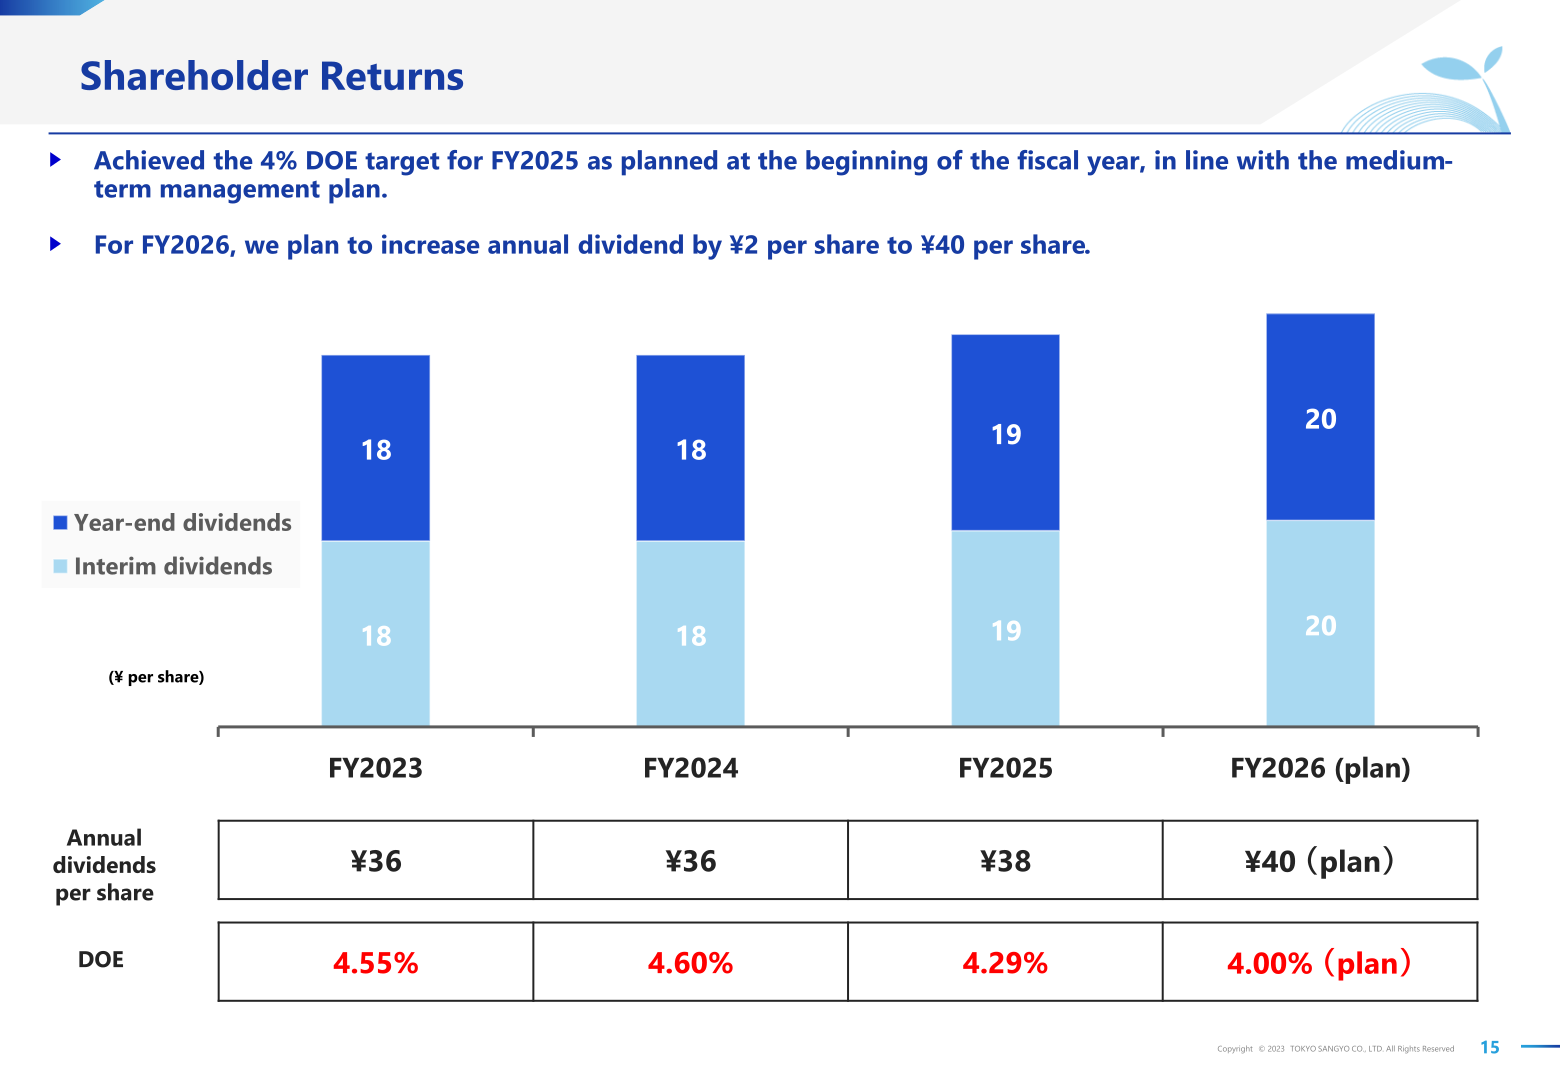
Tokyo Sangyo achieved its 4% dividend on equity (DOE) target for FY2025 as planned at the start of the fiscal year, in line with its medium-term management plan. The company paid an annual dividend of ¥38 per share for FY2025 (¥19 interim, ¥19 year-end), up from ¥36 per share (¥18 interim, ¥18 year-end) in FY2024, equivalent to a DOE of 4.29% (versus 4.60% in FY2024). For FY2026, the company plans to increase its annual dividend by ¥2 per share to ¥40 per share (¥20 interim, ¥20 year-end), targeting a DOE of 4.00%.
| Item | FY2025 (Actual) | FY2026 (Plan) |
|---|---|---|
| Interim dividend (¥/share) | 19 | 20 |
| Year-end dividend (¥/share) | 19 | 20 |
| Annual dividend (¥/share) | 38 | 40 |
| DOE | 4.29% | 4.00% |
Medium-Term Plan / Topics
Tokyo Sangyo reported progress on its medium-term management plan, T-ScaleUp2027, across five priority strategies. In energy transition, the company used on-site capabilities to capture new customer opportunities and develop new business domains in the nuclear power-related business, and resolved a pending lawsuit related to its solar-related business through a settlement, after which it stopped accepting new orders for solar-related construction contracting work while continuing to execute remaining projects. In sustainable-business creation, the company reviewed its EV business in light of a difficult business environment under a policy of strategic selection and concentration, redeploying personnel to leverage its existing customer base. The company also continued the reorganization of unprofitable subsidiaries begun in the prior fiscal year, continued to strengthen risk management based on recurrence-prevention measures formulated two fiscal years earlier, formulated a basic framework for strengthening system governance, and continued to prioritize shareholder returns with a DOE target of 4% or higher.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















