
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Mitsubishi Pencil Co., Ltd. reported consolidated net sales of ¥89,814 million for the twelve months ended December 31, 2025, up 1.1% year on year, supported by steady sales in Japan and Asia despite adjustments to distributed inventory overseas. Operating profit fell 20.5% to ¥9,692 million, ordinary profit fell 22.6% to ¥10,028 million, and profit attributable to owners of parent fell 44.7% to ¥6,235 million, reflecting a decline in gross profit margin from changes in product mix and rising costs, higher selling, general and administrative expenses for growth investment, and the absence of a gain on sale of non-current assets that had been recorded as extraordinary income in the previous fiscal year. For the twelve months ending December 31, 2026, the company forecasts net sales of ¥94,000 million and a return to profit growth.
Consolidated Results (Full-Year Actual)
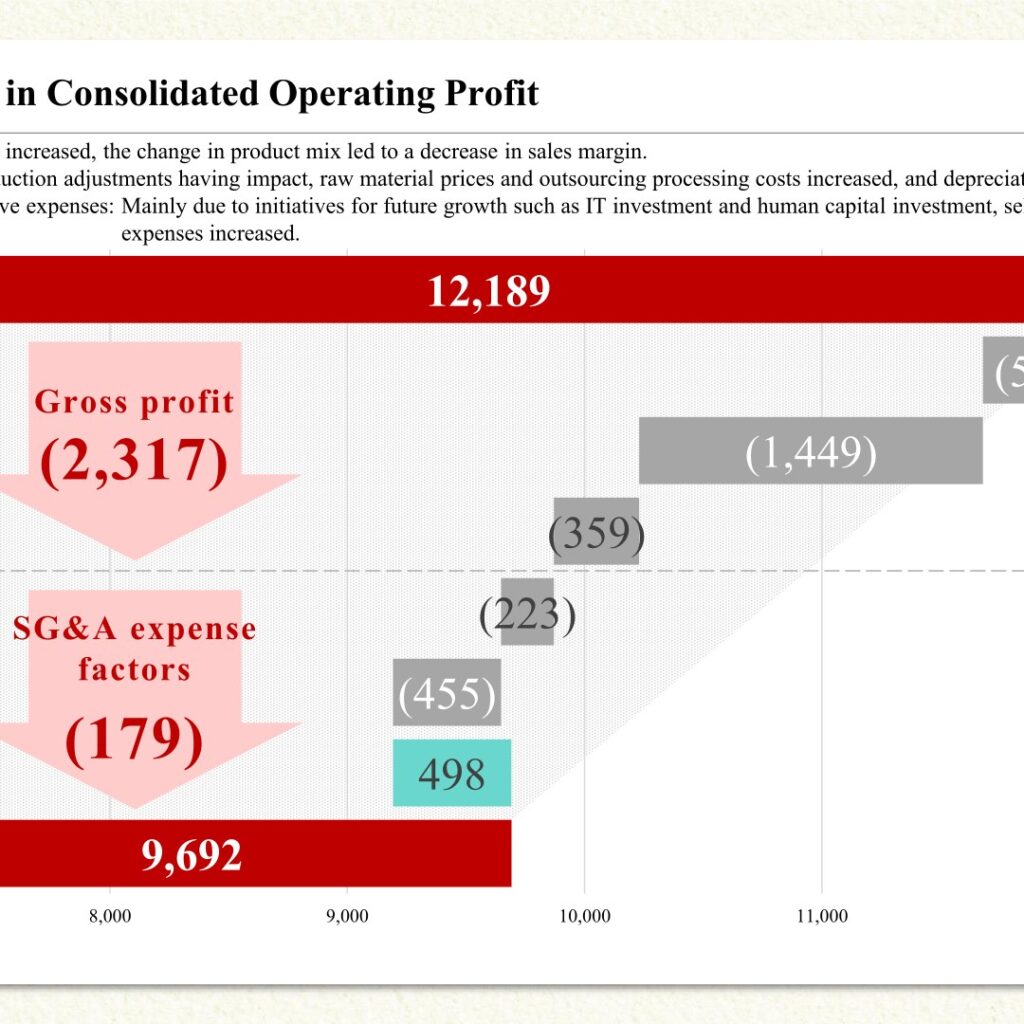
Net sales increased due to steady sales in Japan and Asia, despite the impact of adjustments in distributed inventory overseas. Gross profit decreased due to the impact of a decline in sales margin from changes in product mix and profit squeeze from rising costs. Profit was affected by the absence of the gain on sale of non-current assets recorded as extraordinary income in the previous fiscal year.
| Item (Millions of yen unless noted) | FY2025 | FY2024 | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 89,814 | 88,820 | 994 | 1.1% |
| Gross profit | 44,522 | 46,840 | (2,317) | (4.9%) |
| (Gross profit margin) | 49.6% | 52.7% | (3.2%) | – |
| Selling, general and administrative expenses | 34,830 | 34,650 | 179 | 0.5% |
| Operating profit | 9,692 | 12,189 | (2,496) | (20.5%) |
| Ordinary profit | 10,028 | 12,952 | (2,924) | (22.6%) |
| Profit attributable to owners of parent* | 6,235 | 11,272 | (5,037) | (44.7%) |
Segment Results
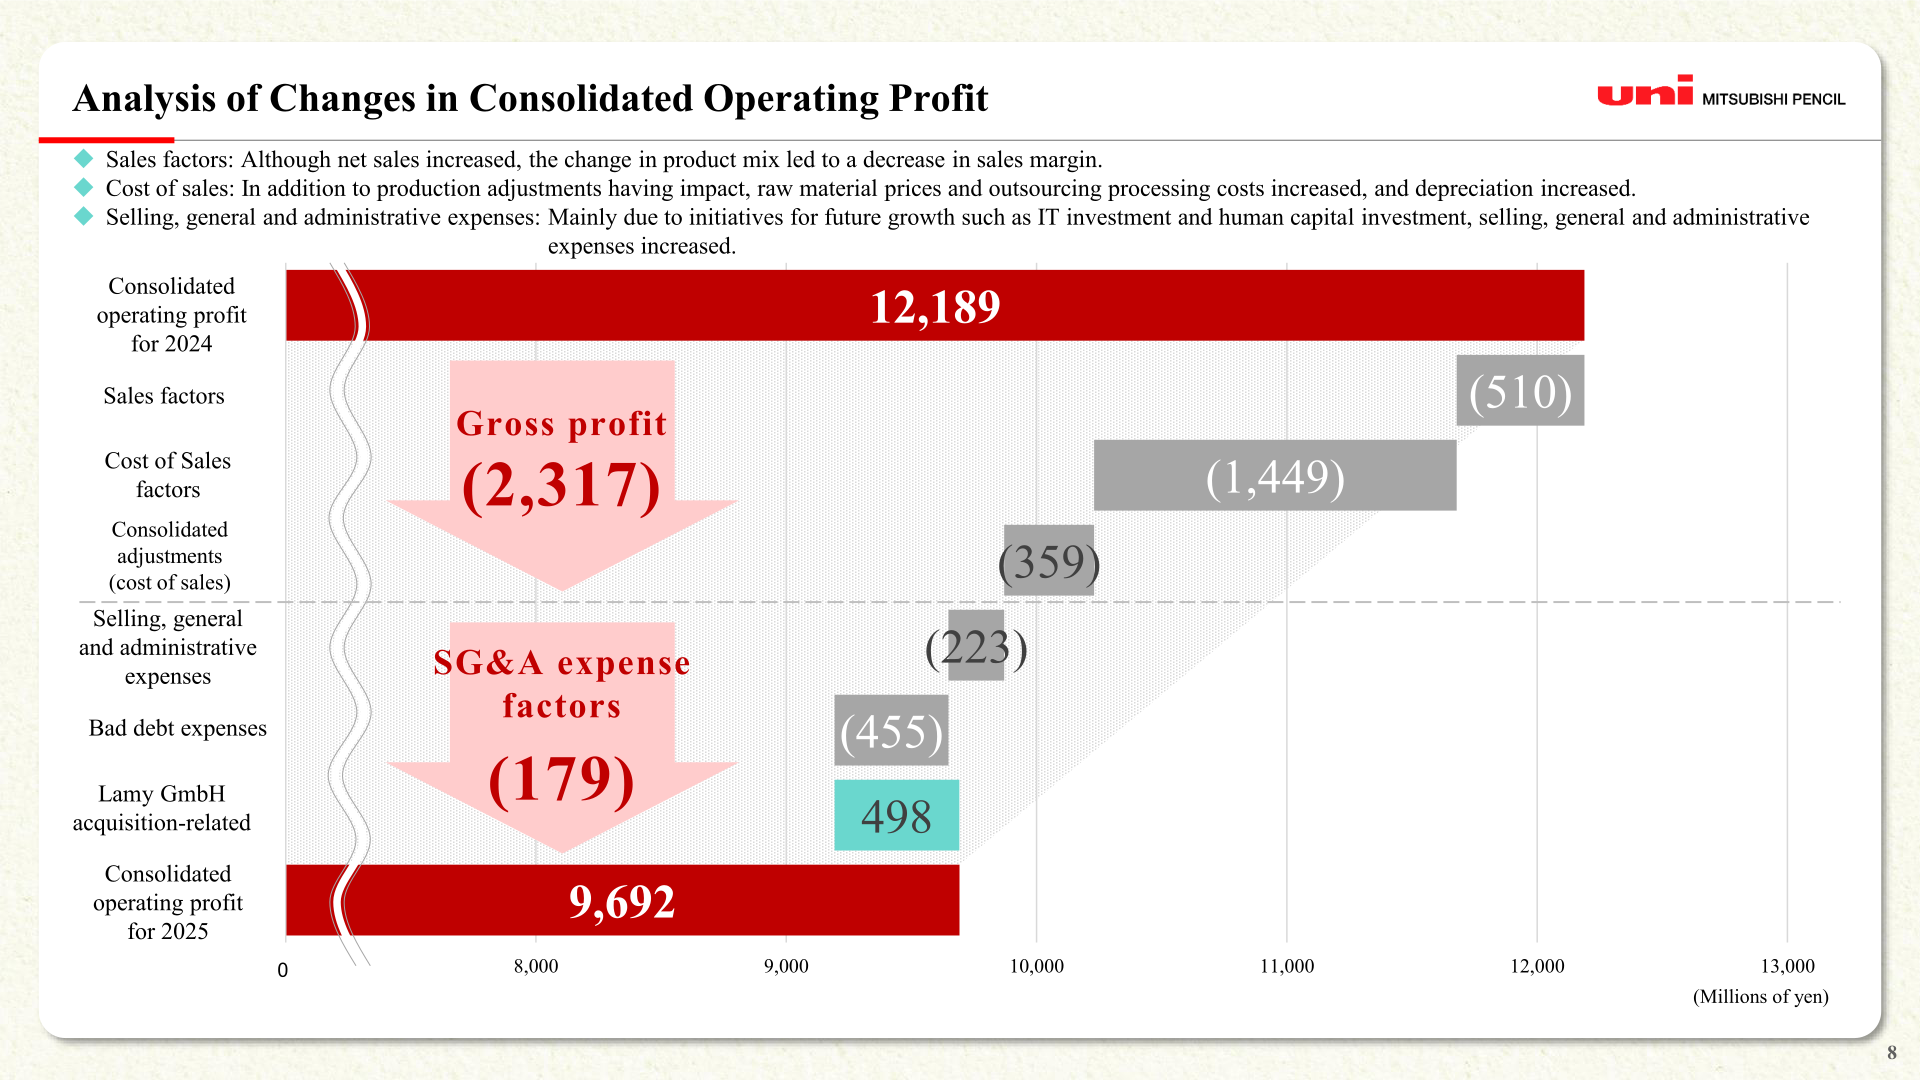
Domestic writing instruments business sales grew on JETSTREAM and new products such as uniball ZENTO, KURUTOGA Wood, and LAMY safari JETSTREAM INSIDE. Overseas writing instruments business sales were boosted by new products and the LAMY brand, but net sales decreased due to adjustments in distributed inventory of POSCA, a big seller in the previous fiscal year. In businesses other than writing instruments, the cosmetics business and industrial materials business performed well; the cosmetics business in particular increased sales due to overlapping product renewals by OEM clients.
| Segment | FY2025 Net Sales (Millions of yen) | YoY Change (Millions of yen) |
|---|---|---|
| Domestic writing instruments business | 30,499 | 1,385 |
| Overseas writing instruments business | 51,000 | (1,996) |
| Business other than writing instruments | 8,316 | 1,605 |
| Total net sales | 89,814 | 994 |
FY2026 Forecast
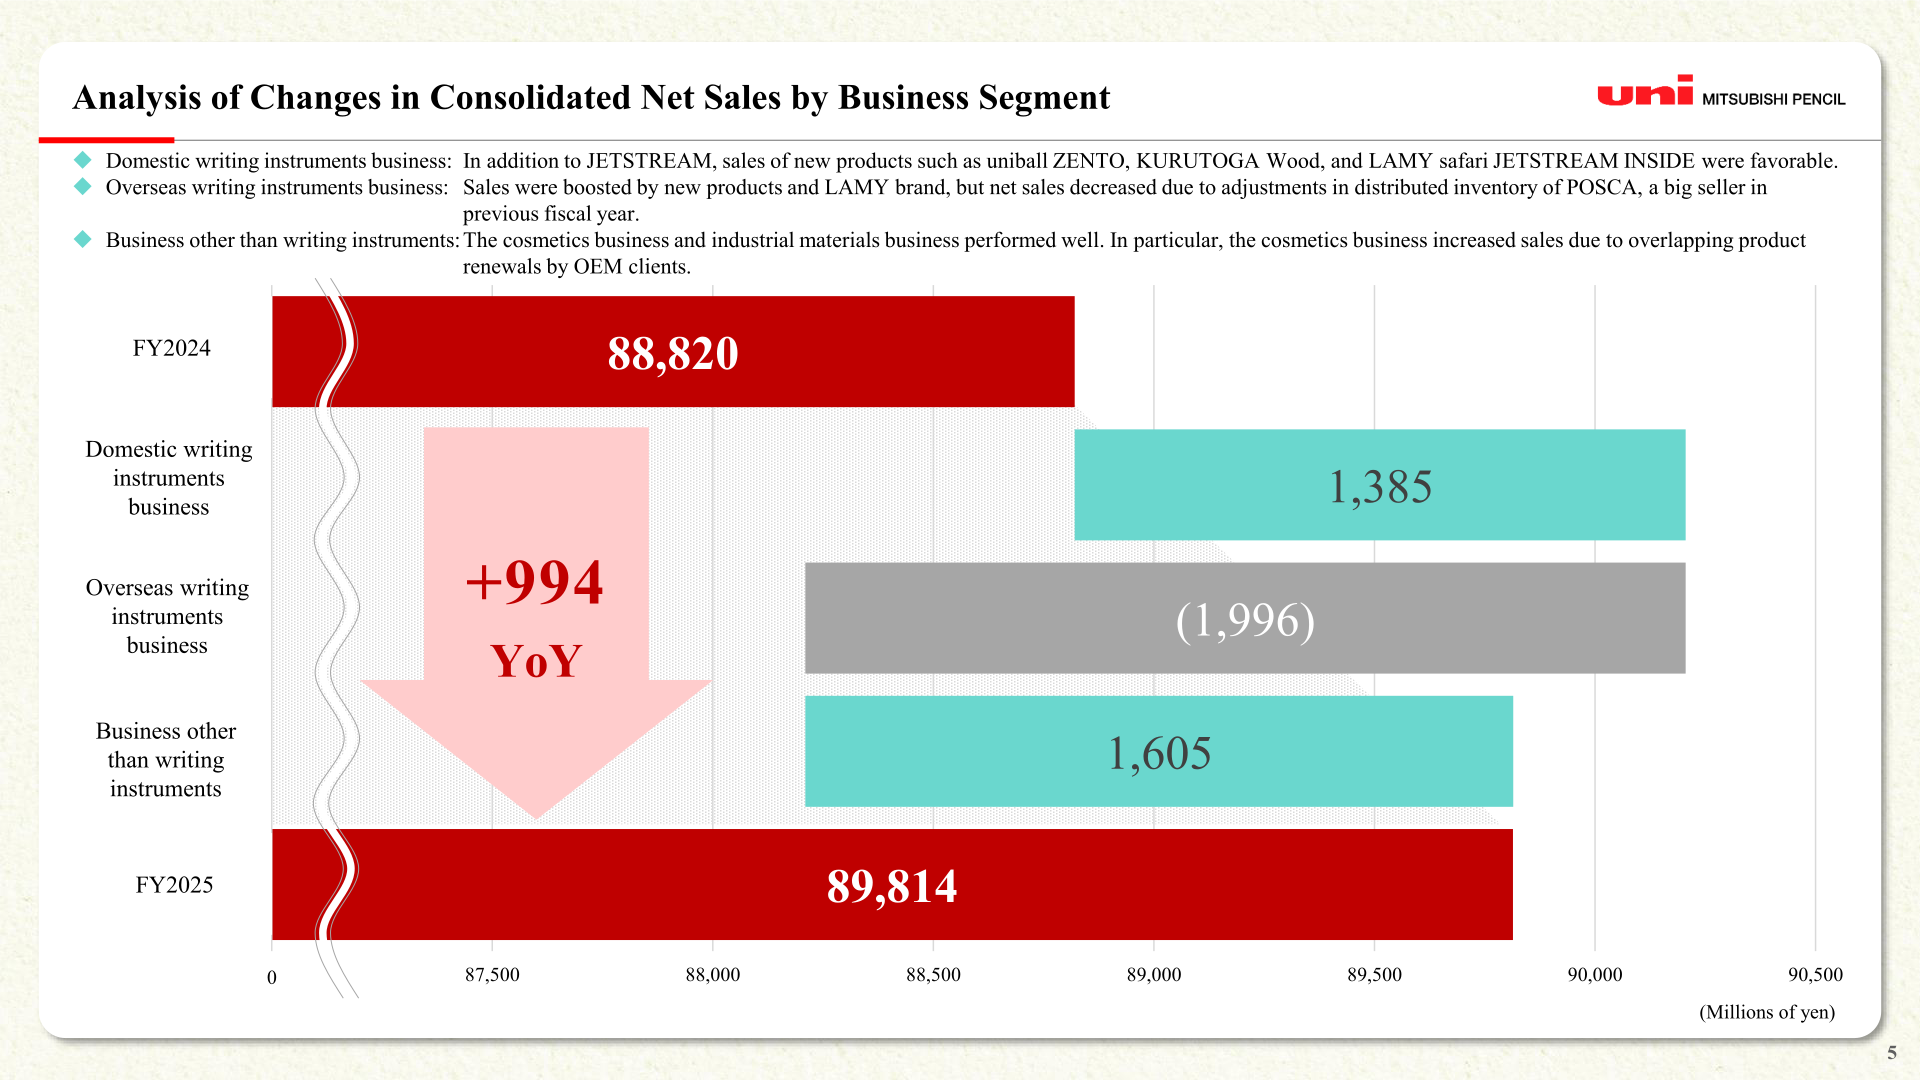
Net sales are expected to increase due to the resolution of distributed inventory adjustments in overseas markets, the regrowth of the uniball brand, and the strengthening of sales structure in various overseas regions. Operating profit is expected to increase overall, despite anticipating higher selling, general and administrative expenses due to growth investments for the future, such as IT investment, human capital investment, and production facility maintenance.
| Item | FY2025 (Actual) | FY2026 (Forecast) | Change | Change (%) |
|---|---|---|---|---|
| Net sales (Millions of yen) | 89,814 | 94,000 | 4,186 | 4.7% |
| Operating profit (Millions of yen) | 9,692 | 10,500 | 808 | 8.3% |
| (Operating profit margin) | 10.8% | 11.2% | 0.4% | – |
| Ordinary profit (Millions of yen) | 10,028 | 11,000 | 972 | 9.7% |
| Profit attributable to owners of parent (Millions of yen) | 6,235 | 7,700 | 1,465 | 23.5% |
| (Avg. USD exchange rate) | ¥150.40 | ¥150.00 | (¥0.40) | – |
| (Avg. EUR exchange rate) | ¥169.14 | ¥175.00 | ¥5.86 | – |
| Earnings Per Share | ¥114.27 | ¥142.35 | ¥28.08 | – |
| Segment (Millions of yen) | FY2025 (Actual) | FY2026 (Forecast) | Change | Change (%) |
|---|---|---|---|---|
| Domestic writing instruments business | 30,499 | 30,600 | 101 | 0.3% |
| Overseas writing instruments business | 51,000 | 55,300 | 4,300 | 8.4% |
| Business other than writing instruments | 8,316 | 8,100 | (216) | (2.6%) |
Shareholder Returns
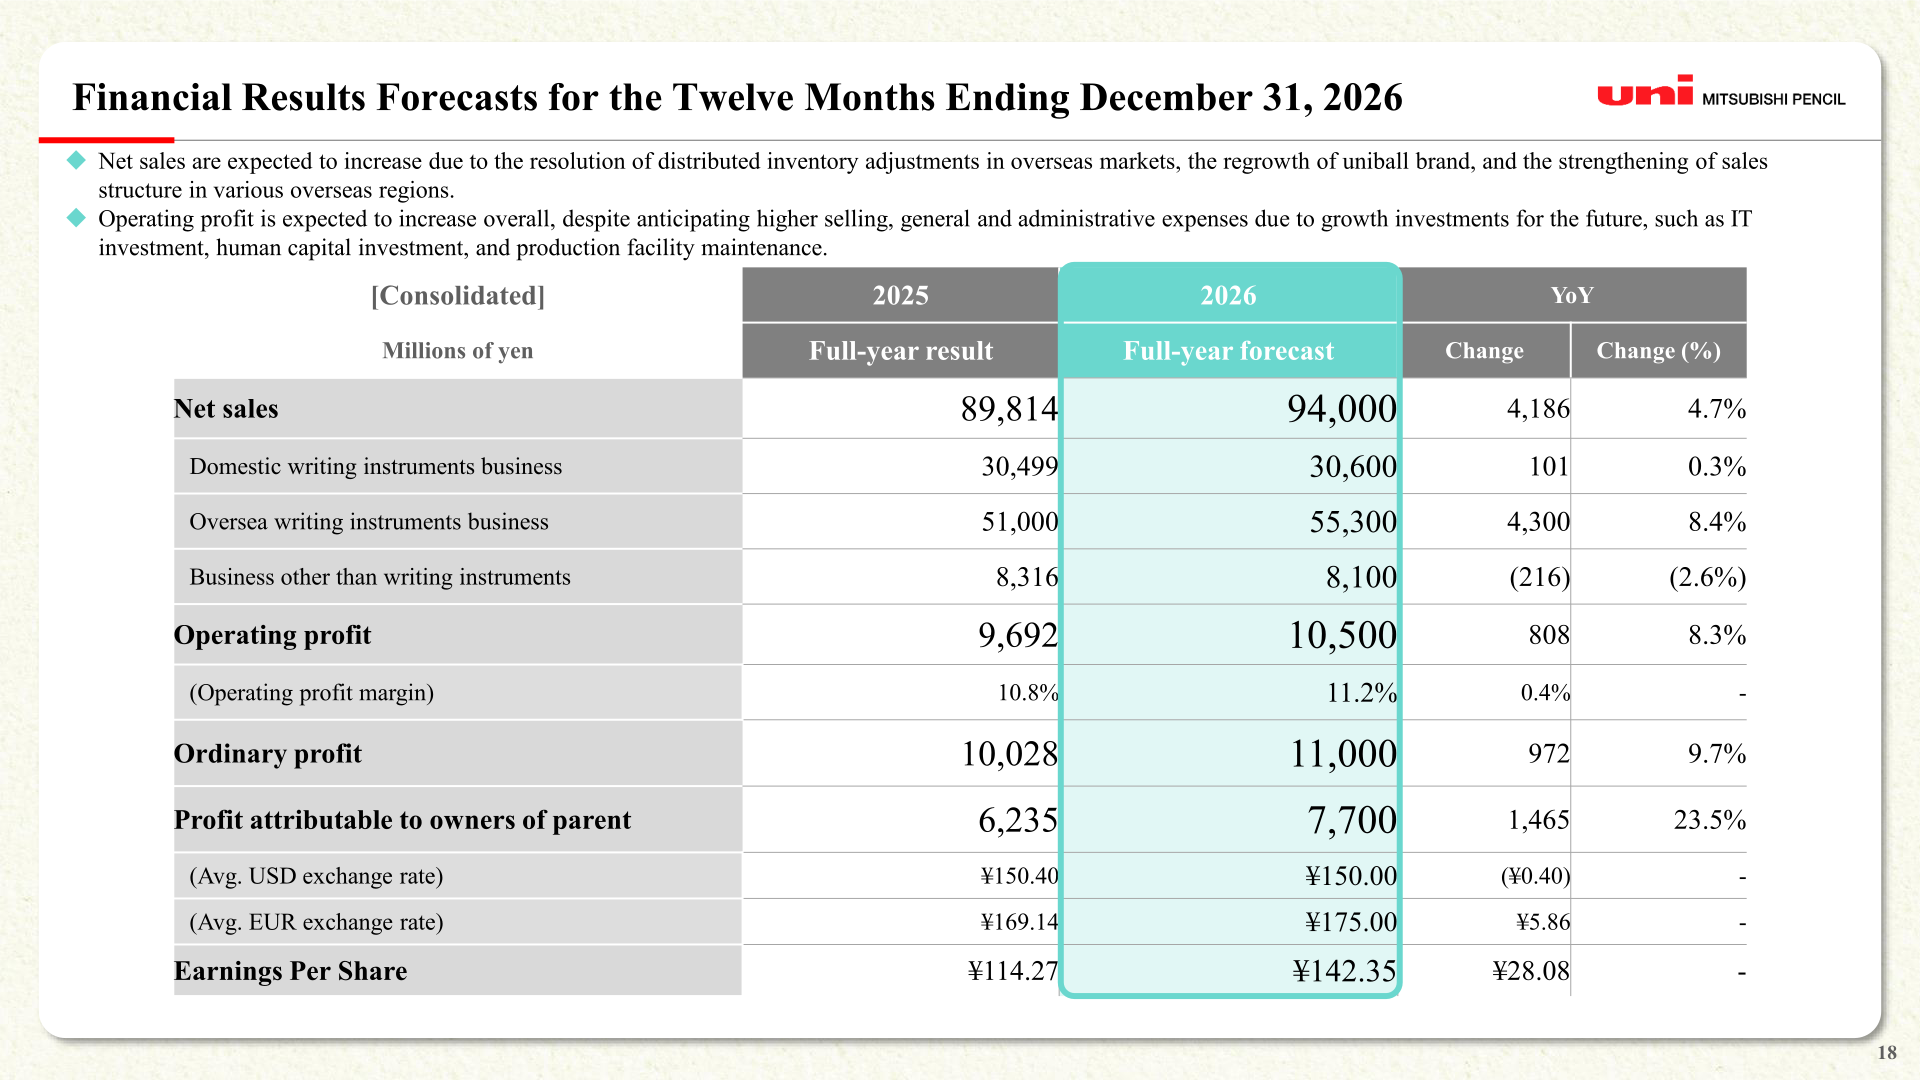
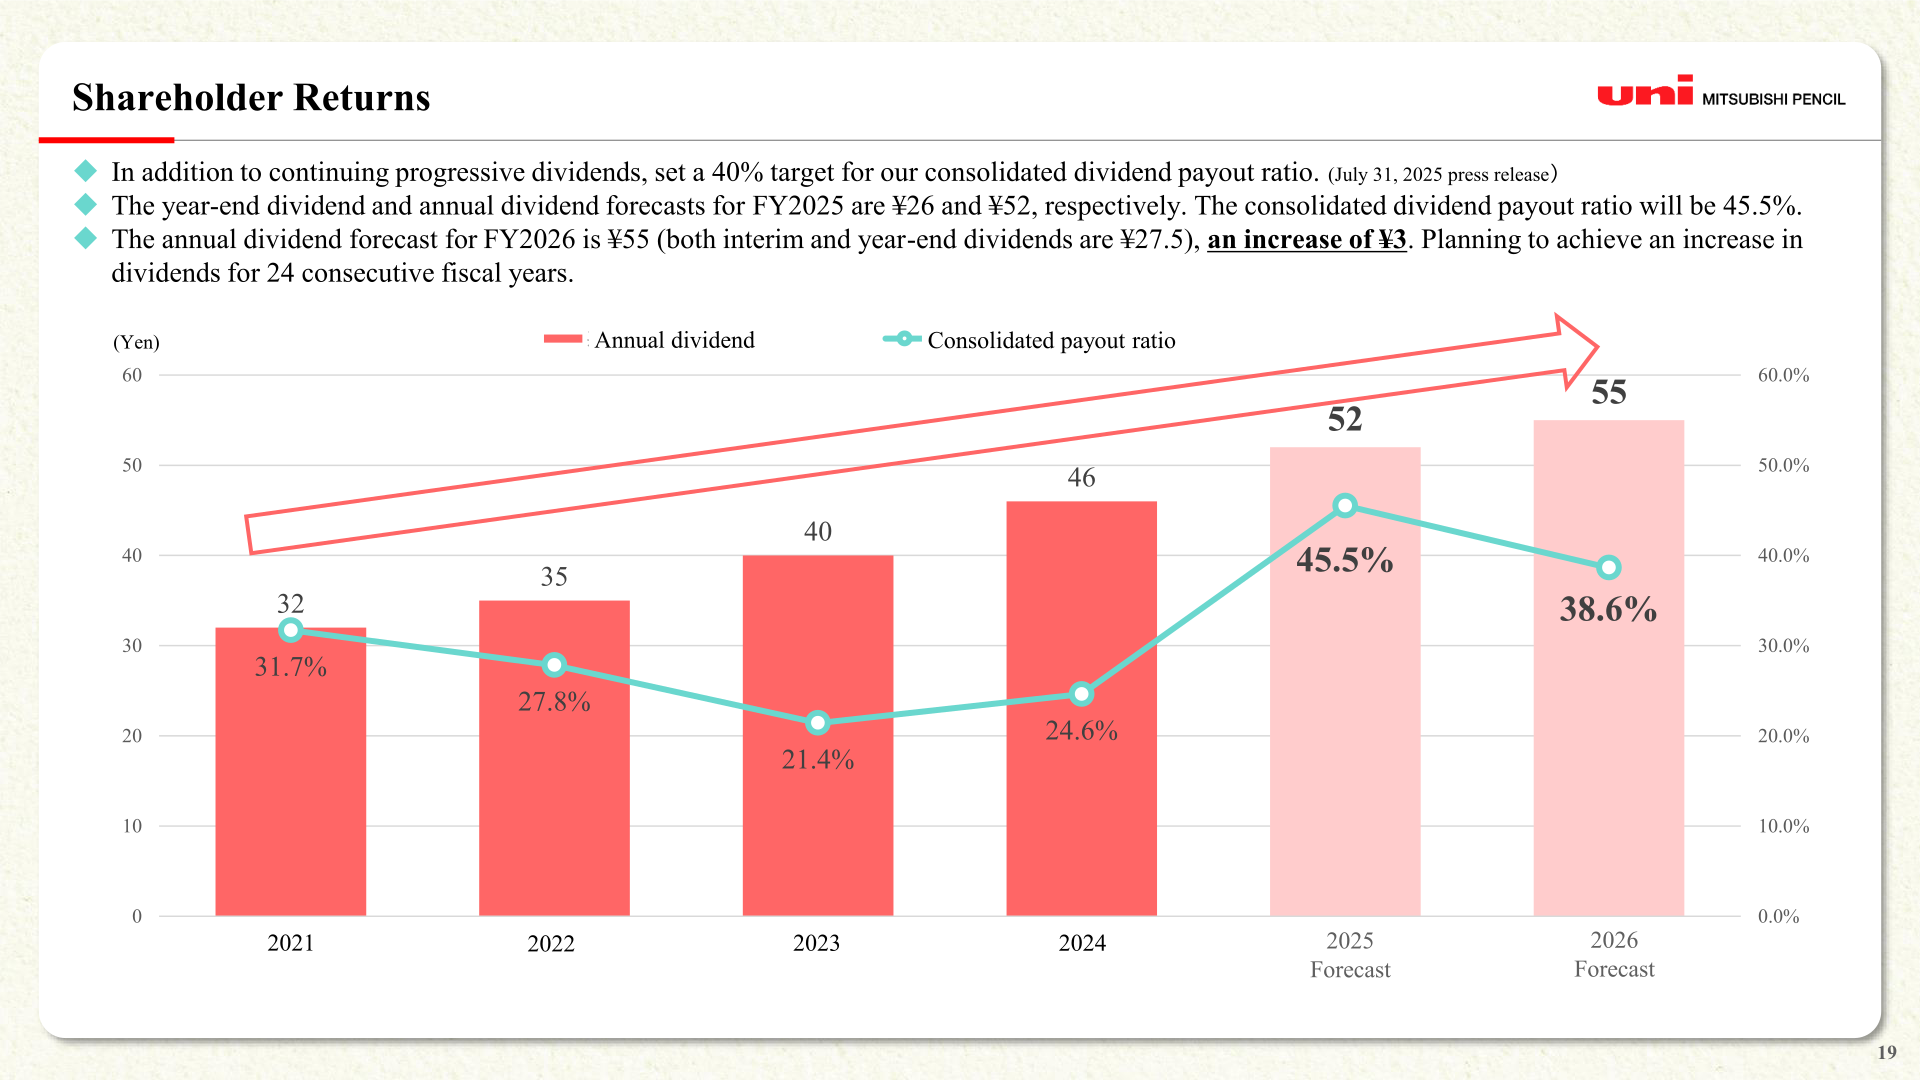
In addition to continuing progressive dividends, the company set a 40% target for its consolidated dividend payout ratio (July 31, 2025 press release). The year-end dividend and annual dividend forecasts for FY2025 are ¥26 and ¥52, respectively, and the consolidated dividend payout ratio will be 45.5%. The annual dividend forecast for FY2026 is ¥55 (both interim and year-end dividends are ¥27.5), an increase of ¥3, planning to achieve an increase in dividends for 24 consecutive fiscal years.
| Fiscal Year | Annual Dividend (Yen) | Consolidated Payout Ratio |
|---|---|---|
| 2021 | 32 | 31.7% |
| 2022 | 35 | 27.8% |
| 2023 | 40 | 21.4% |
| 2024 | 46 | 24.6% |
| 2025 (Forecast) | 52 | 45.5% |
| 2026 (Forecast) | 55 | 38.6% |
Medium-Term Plan / Capital Efficiency
Under the Medium-term Business Plan 2025-2027, positioned as the ‘Advance’ stage toward Vision 2036, the company targets consolidated net sales of ¥103.0 billion and an operating profit margin of 15% for FY2027, comprising ¥31.0 billion from the domestic writing instruments business, ¥63.0 billion from the overseas writing instruments business, and ¥9.0 billion from businesses other than writing instruments. Toward Vision 2036, the company targets net sales of ¥150.0 billion and an operating profit margin of 15%, comprising ¥30.0 billion from the domestic writing instruments business, ¥70.0 billion from the overseas writing instruments business, and ¥30.0–50.0 billion from businesses other than writing instruments, together with ROE of more than 8% and a PBR of more than 1x.
ROE was above the 8% target in 2023 and 2024 due to a one-time sale of fixed assets, but declined to 4.7% in 2025; PBR stood at 0.85x, still below 1x. For 2025, the company allocated ¥7.1 billion to growth and infrastructure investment (including R&D expenses of ¥4.2 billion) and ¥5.1 billion to shareholder returns, funded by operating cash flow of ¥2.4 billion together with cash on hand and external funding; operating cash flow lagged behind plan due to reduced profits and shortened payment terms. Over the three-year period from 2025 to 2027, the company plans operating cash flow of ¥32.0 billion or more, with continued R&D spending of ¥9.0 billion or more over the period.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















