
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
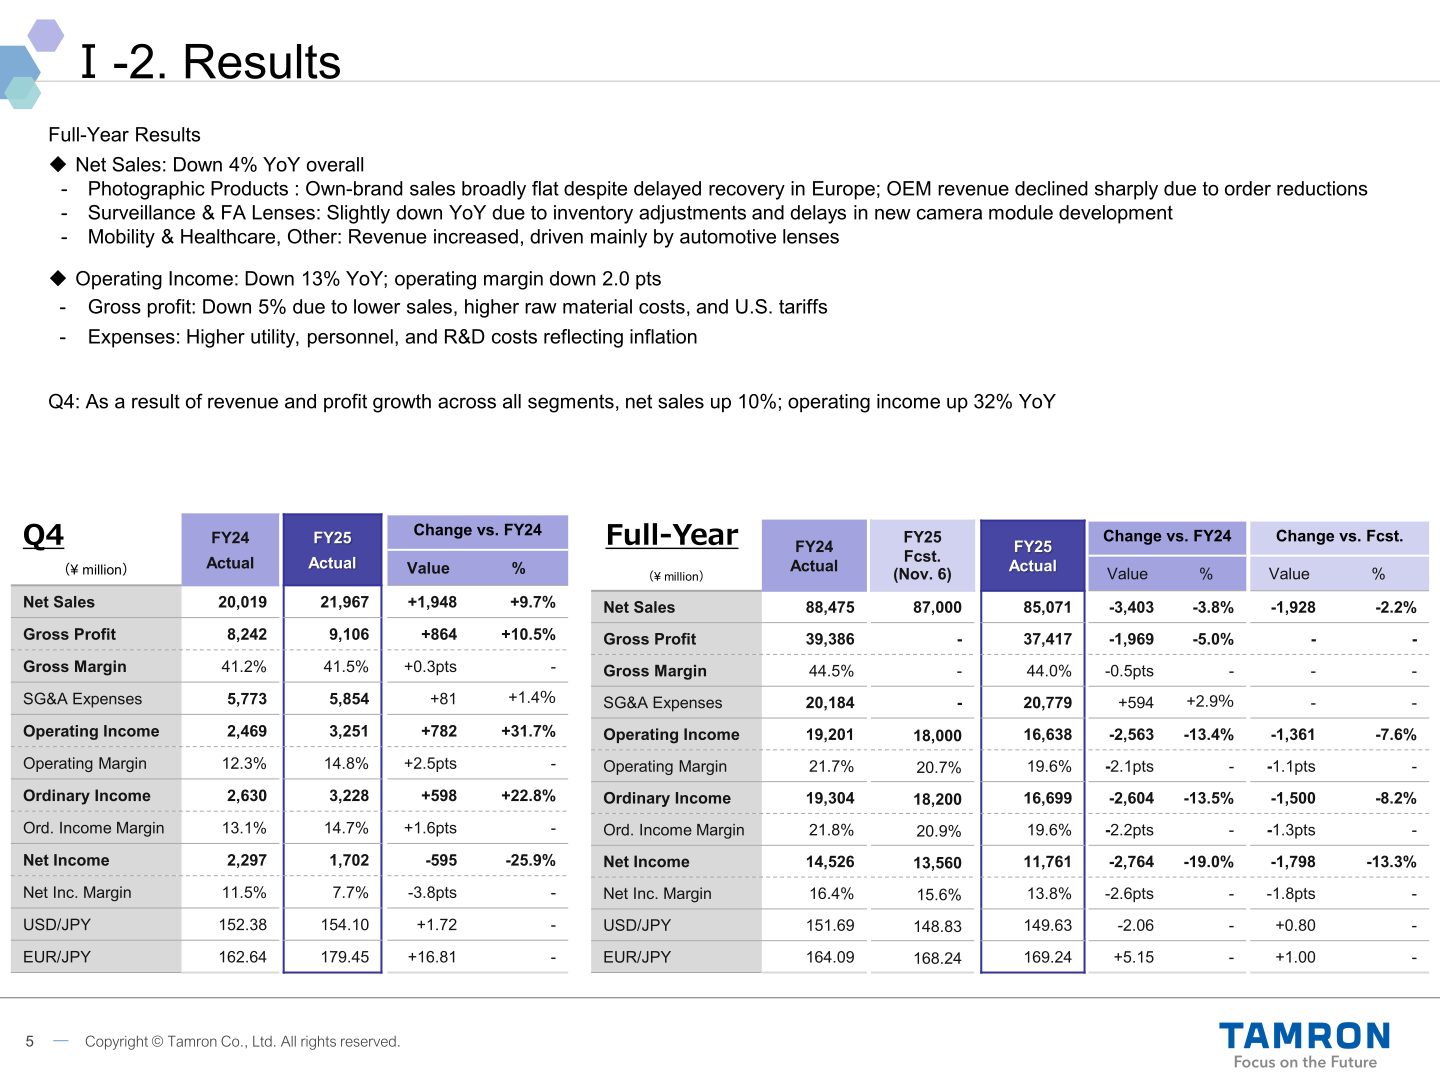
Tamron Co., Ltd. reported a decline in sales and profit for FY2025 (fiscal year ended December 31, 2025), with consolidated net sales down 3.8% year on year to 85,071 million yen and operating income down 13.4% to 16,638 million yen, primarily due to a sharp decline in photographic OEM shipments amid a stagnant interchangeable-lens market, only partly offset by growth in the Surveillance & FA Lenses and Mobility & Healthcare Products, Other segments. Net income fell 19.0% to 11,761 million yen. Despite the profit decline, the company raised its annual dividend to 36.25 yen per share (+1.25 yen year on year), resulting in a payout ratio of 49.8% and a total shareholder return ratio of approximately 80%. For FY2026, Tamron forecasts a rebound with net sales of 91,000 million yen (+7.0%) and operating income of 18,500 million yen (+11.2%), targeting net sales above 90.0 billion yen for the first time.
Consolidated Results (Full-Year Actual)
Full-year net sales declined 3.8% year on year: own-brand photographic sales were broadly flat despite a delayed recovery in Europe, while OEM revenue fell sharply on order reductions; Surveillance & FA Lenses sales were slightly down on inventory adjustments and camera-module development delays; Mobility & Healthcare Products, Other sales increased on higher automotive lens demand. Operating income fell 13.4% year on year, with operating margin down 2.1 points to 19.6%, as lower gross profit from the sales decline was compounded by higher raw material costs, U.S. tariff impact, and increased R&D and SG&A expenses. Both net sales and operating income came in below the November 6 revised forecast, by 2.2% and 7.6% respectively. Foreign exchange had a negative full-year impact of 450 million yen on net sales and 120 million yen on operating income (USD/JPY averaged 149.63 vs. 151.69 in FY2024; EUR/JPY averaged 169.24 vs. 164.09).
| Item | FY2024 | FY2025 | Y-on-Y (Amount) | Y-on-Y (%) | FY2025 Forecast (Nov. 6) | vs. Forecast (%) |
|---|---|---|---|---|---|---|
| Net Sales (¥ million) | 88,475 | 85,071 | -3,403 | -3.8% | 87,000 | -2.2% |
| Operating Income (¥ million) | 19,201 | 16,638 | -2,563 | -13.4% | 18,000 | -7.6% |
| Ordinary Income (¥ million) | 19,304 | 16,699 | -2,604 | -13.5% | 18,200 | -8.2% |
| Net Income (¥ million) | 14,526 | 11,761 | -2,764 | -19.0% | 13,560 | -13.3% |
Segment Results
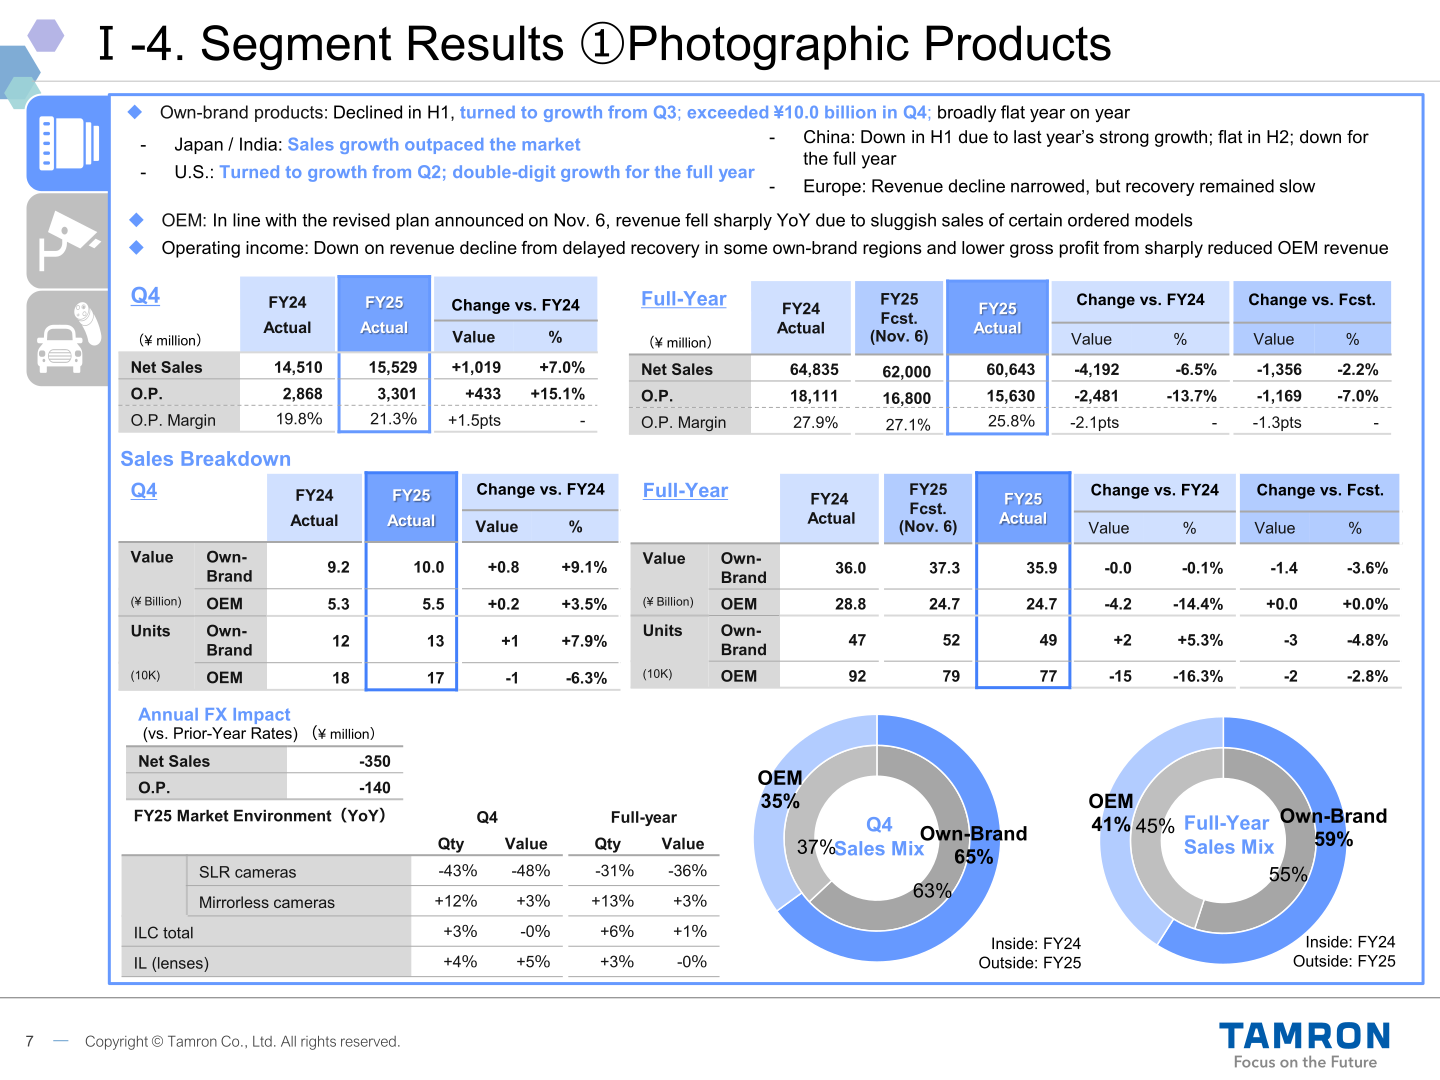
By segment, Photographic Products net sales fell 6.5% to 60,643 million yen and operating income fell 13.7% to 15,630 million yen, as own-brand value was roughly flat at 35.9 billion yen while OEM value fell 14.4% to 24.7 billion yen in line with the November 6 revised plan; by region, own-brand sales grew in Japan/India and the U.S. (double-digit growth for the full year) but declined in China and recovery remained slow in Europe. Surveillance & FA Lenses net sales fell 1.8% to 12,091 million yen but operating income rose 7.0% to 1,675 million yen (operating margin up 1.2pts to 13.9%) on improved gross margin and tighter SG&A control, as Surveillance revenue growth offset declines in FA (customer inventory adjustments) and Camera Modules (development delays). Mobility & Healthcare Products, Other net sales rose 8.9% to 12,336 million yen and operating income rose 9.0% to 2,699 million yen, driven by automotive lens revenue exceeding 10.0 billion yen on ADAS-related demand and healthcare component revenue growing approximately 1.5x to over 1.0 billion yen.
| Segment | Metric | FY2024 | FY2025 | Y-on-Y (Amount) | Y-on-Y (%) |
|---|---|---|---|---|---|
| Photographic Products | Net Sales (¥ million) | 64,835 | 60,643 | -4,192 | -6.5% |
| Photographic Products | Operating Income (¥ million) | 18,111 | 15,630 | -2,481 | -13.7% |
| Surveillance & FA Lenses | Net Sales (¥ million) | 12,313 | 12,091 | -222 | -1.8% |
| Surveillance & FA Lenses | Operating Income (¥ million) | 1,566 | 1,675 | 109 | 7.0% |
| Mobility & Healthcare Products, Other | Net Sales (¥ million) | 11,325 | 12,336 | 1,010 | 8.9% |
| Mobility & Healthcare Products, Other | Operating Income (¥ million) | 2,476 | 2,699 | 223 | 9.0% |
FY2026 Forecast
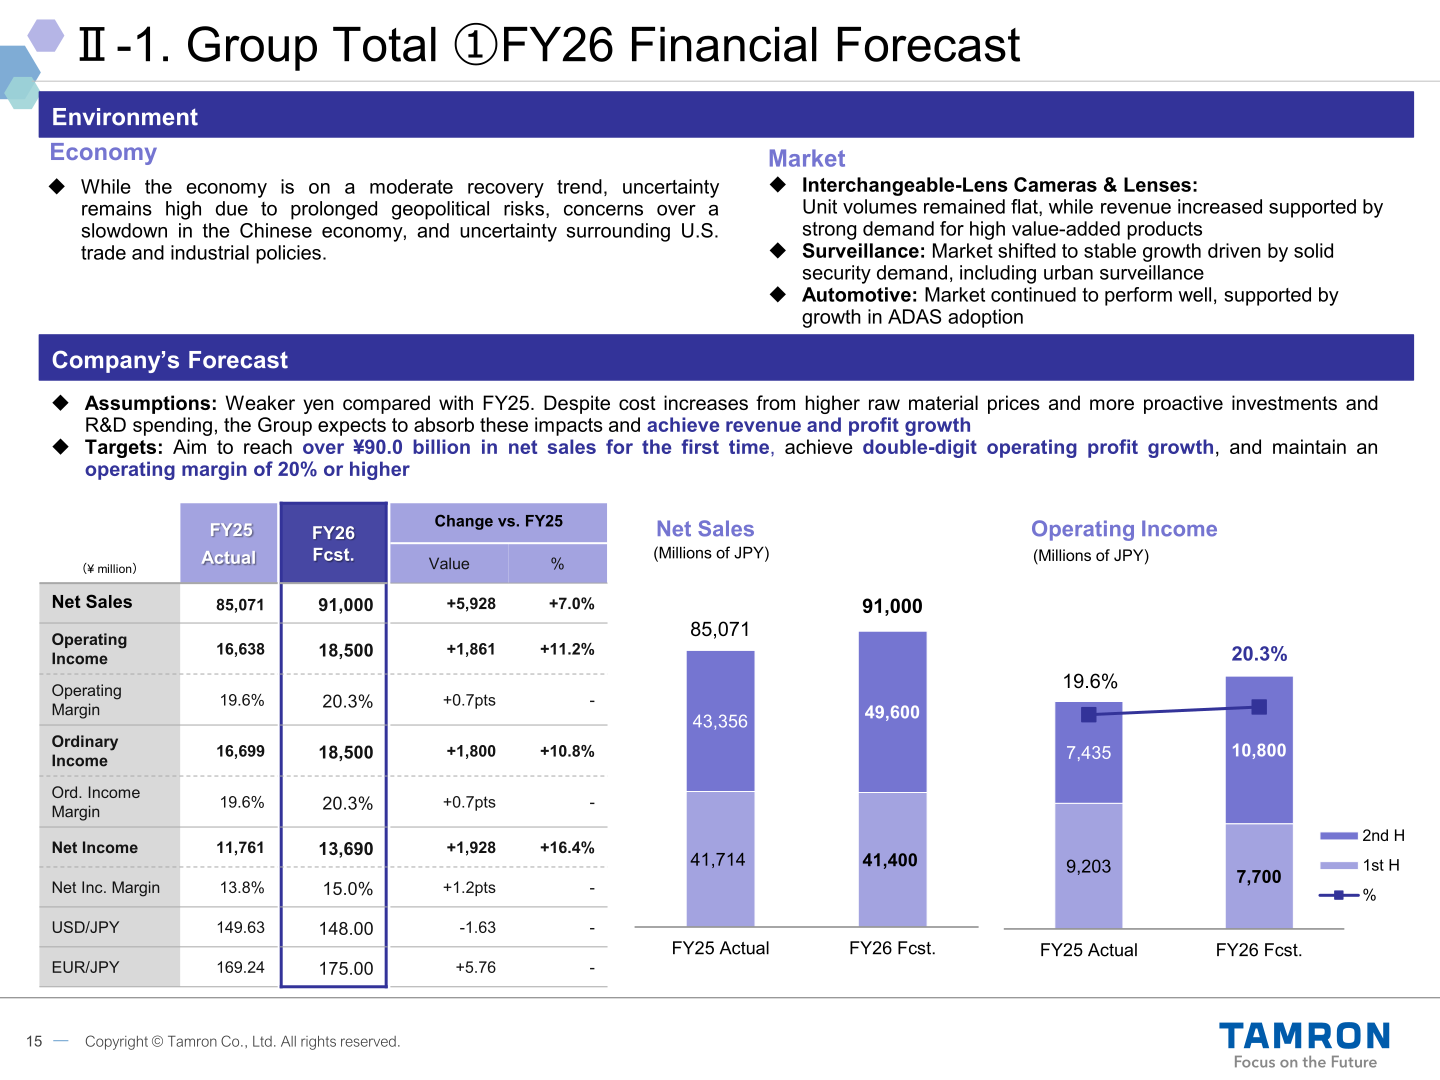
For FY2026, Tamron forecasts consolidated net sales of 91,000 million yen (+7.0% year on year) and operating income of 18,500 million yen (+11.2%), targeting net sales above 90.0 billion yen for the first time while raising operating margin 0.7pt to 20.3%. The forecast assumes a weaker yen than FY2025 (USD/JPY 148.00, EUR/JPY 175.00) and anticipates absorbing higher raw material costs and increased investment/R&D spending through revenue and profit growth. By segment, Photographic Products net sales are forecast to rise 3.9% to 63,000 million yen and operating income to rise 10.0% to 17,200 million yen, supported by 10 new own-brand model launches and a sales recovery in Europe and China, even as OEM revenue is adjusted down to reflect market conditions and recent order trends. Surveillance & FA Lenses net sales are forecast to rise 19.9% to 14,500 million yen with operating income up 13.4% to 1,900 million yen. Mobility & Healthcare Products, Other net sales are forecast to rise 9.4% to 13,500 million yen, but operating income is forecast to fall 7.4% to 2,500 million yen (margin down 3.4pts to 18.5%) on higher SG&A and continued investment despite revenue growth.
| Item | FY2025 (Actual) | FY2026 Forecast | Y-on-Y (Amount) | Y-on-Y (%) |
|---|---|---|---|---|
| Net Sales (¥ million) | 85,071 | 91,000 | 5,928 | 7.0% |
| Operating Income (¥ million) | 16,638 | 18,500 | 1,861 | 11.2% |
| Ordinary Income (¥ million) | 16,699 | 18,500 | 1,800 | 10.8% |
| Net Income (¥ million) | 11,761 | 13,690 | 1,928 | 16.4% |
Shareholder Returns
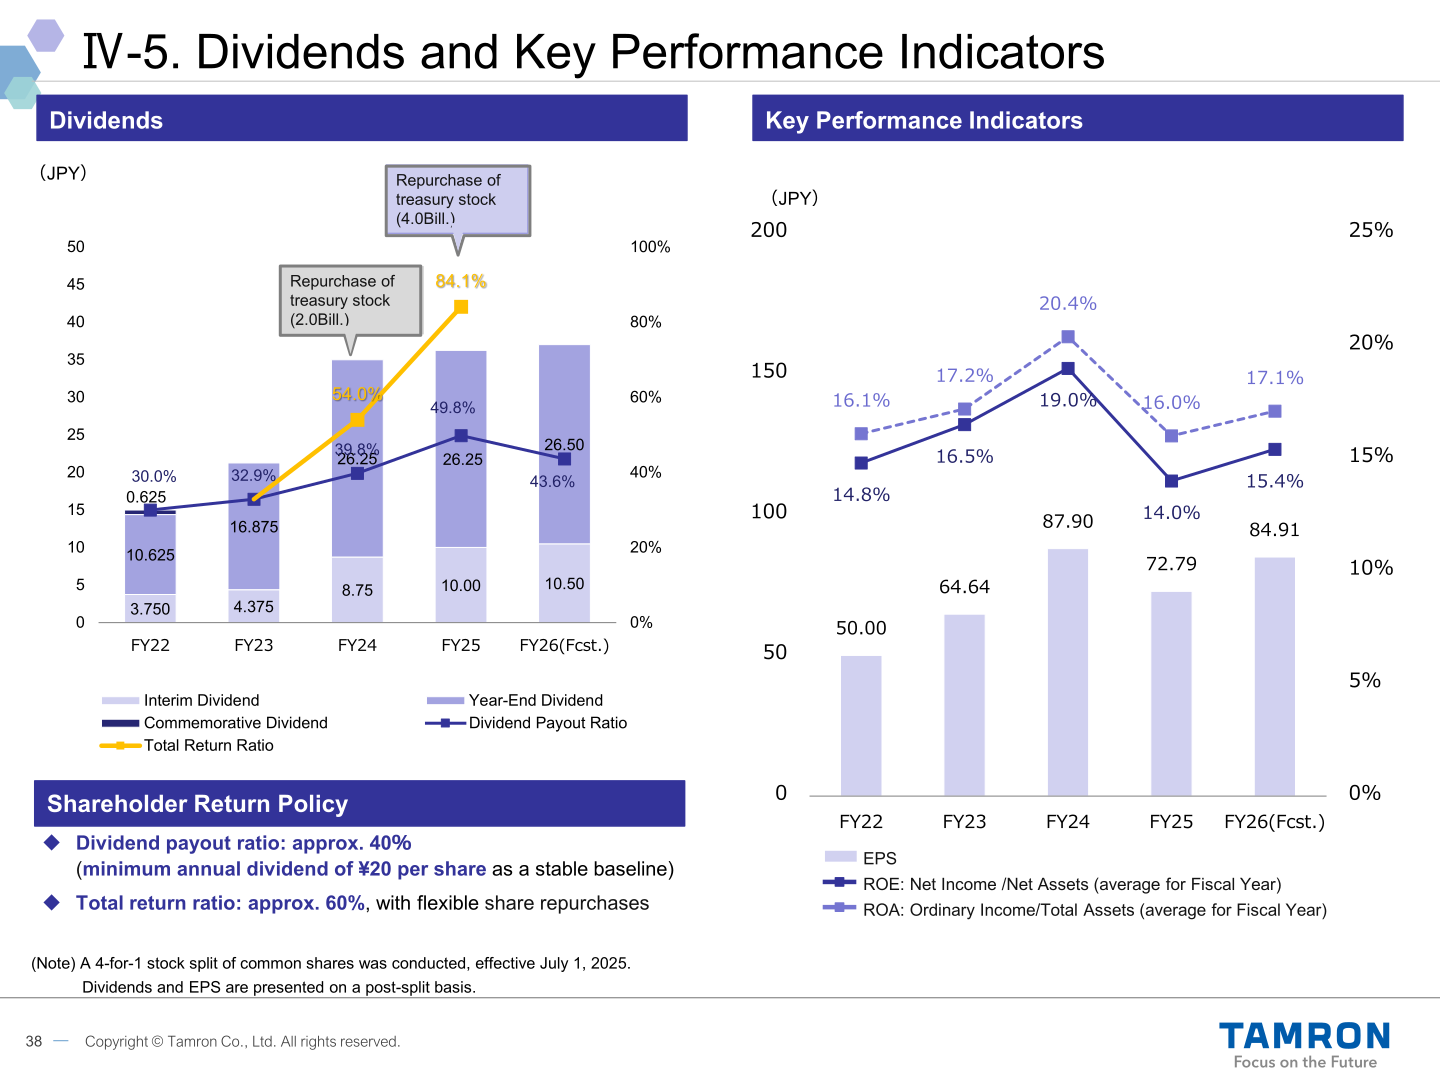
Despite the decline in profit, Tamron kept its year-end dividend unchanged from its initial forecast at 26.25 yen per share, resulting in an annual dividend of 36.25 yen per share for FY2025 (+1.25 yen year on year), a payout ratio of 49.8%, and a total shareholder return ratio of approximately 80%. In February the company repurchased 4.0 billion yen of treasury shares (double the 2.0 billion yen repurchased in FY2024), and in May it cancelled 3.3 million treasury shares, equivalent to 7.17% of issued shares before cancellation. The company’s shareholder return policy targets a dividend payout ratio of approximately 40% (with a minimum annual dividend of 20 yen per share as a stable baseline) and a total return ratio of approximately 60%, with flexible share repurchases. For FY2026, Tamron forecasts an interim dividend of 10.50 yen per share and a year-end dividend of 26.50 yen per share, with a payout ratio of 43.6%. The annual dividend total cannot be confirmed from the materials. Dividend and EPS figures in this article are presented on a post-split basis following a 4-for-1 stock split of common shares effective July 1, 2025.
| Item | FY2024 | FY2025 | FY2026 Forecast |
|---|---|---|---|
| Dividend per Share (¥, post-split) | This cannot be confirmed from the materials. | 36.25 | This cannot be confirmed from the materials. |
| Dividend Payout Ratio (consolidated) | 39.8% | 49.8% | 43.6% |
| Share Repurchase (¥ billion) | 2.0 | 4.0 | This cannot be confirmed from the materials. |
Medium-Term Plan / Topics
Under its ‘Value Creation 26 ver. 2.0’ medium-term management plan, announced after Tamron achieved all initial FY2026 targets in the first year (FY2024), the company has significantly raised its FY2026 targets versus the initial plan: net sales of 95.0 billion yen (vs. 83.0 billion yen initially, and 71.4 billion yen in FY2023), operating income of 20.5 billion yen (vs. 15.3 billion yen initially, and 13.6 billion yen in FY2023), an operating margin of 21.6% (vs. 18.4% initially, and 19.1% in FY2023), EBITDA margin of 24% or higher (vs. an initial target of 22%+ and a FY21-23 average in the 21% range), and ROE of 16% or higher (vs. an initial target of 14%+ and a FY21-23 average in the 13% range). The company targets more than 10 new own-brand model launches per year by FY2026, up from 6 launches in FY2025 and 7 in FY2024 (compared with approximately 5 per year before FY2023). Key events during FY2025 included the start of operations at a second factory in Vietnam in January, a partnership and equity stake acquisition with mapry in April, and six new own-brand model launches between July and November.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















