
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
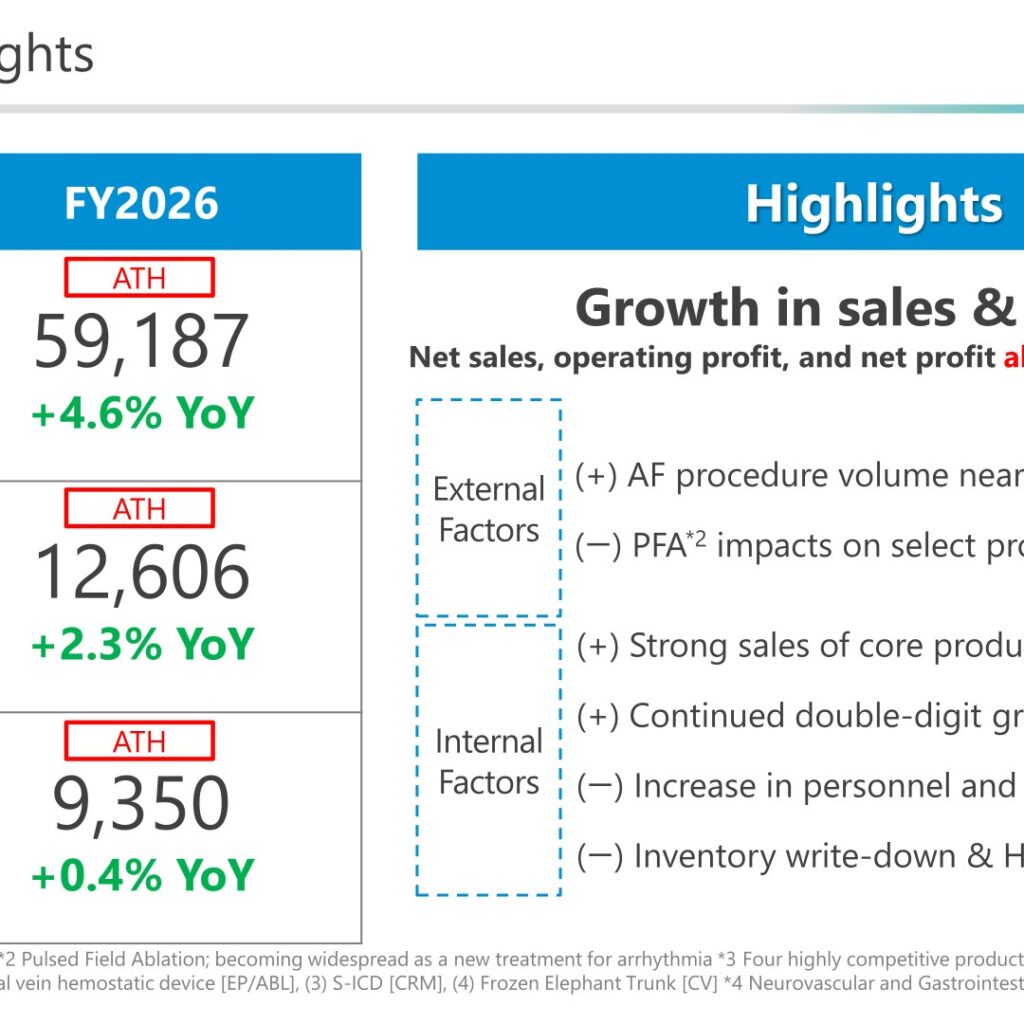
Japan Lifeline Co., Ltd., a cardiovascular-focused medical device company listed on the TSE Prime Market, reported record net sales, operating profit and net income for the fiscal year ended March 31, 2026. Net sales rose 4.6% year on year to ¥59,187mn, operating profit rose 2.3% to ¥12,606mn and net income rose 0.4% to ¥9,350mn, as strong sales of core products and continued double-digit growth in new therapeutic areas offset the impact of pulsed field ablation (PFA) on selected products and higher personnel and R&D expenses. For the current year, the company guides for record net sales of ¥63,200mn (+6.8%) but a 15.1% decline in operating profit, reflecting an acceleration of growth investments and one-time headquarters relocation costs.
Note: Japan Lifeline’s fiscal year ends on March 31, and the company labels the year ended March 31, 2026 as “FY2026” and the current year ending March 31, 2027 as “FY2027”. All figures, tables and labels below follow the company’s own year labels as presented in the materials.
Consolidated Results (Full-Year Actual)
The company describes the year as “Growth in sales & profit; net sales, OP, and NP reached record highs.” Gross profit rose 2.9% to ¥35,174mn, but the gross margin fell 100bps to 59.4% on a reimbursement price revision (two-month impact) and a deteriorating product mix. SG&A increased 3.2% to ¥22,567mn on higher personnel and R&D expenses. Net income was held to a 0.4% increase by inventory write-downs following withdrawal from the cholangioscope and HeartLight X3 businesses (non-operating ¥295mn), headquarters relocation costs (extraordinary losses ¥108mn), and the recognition of deferred tax assets in FY2025.
| Item (¥mn, except per share) | FY2026 | FY2025 | Change | % |
|---|---|---|---|---|
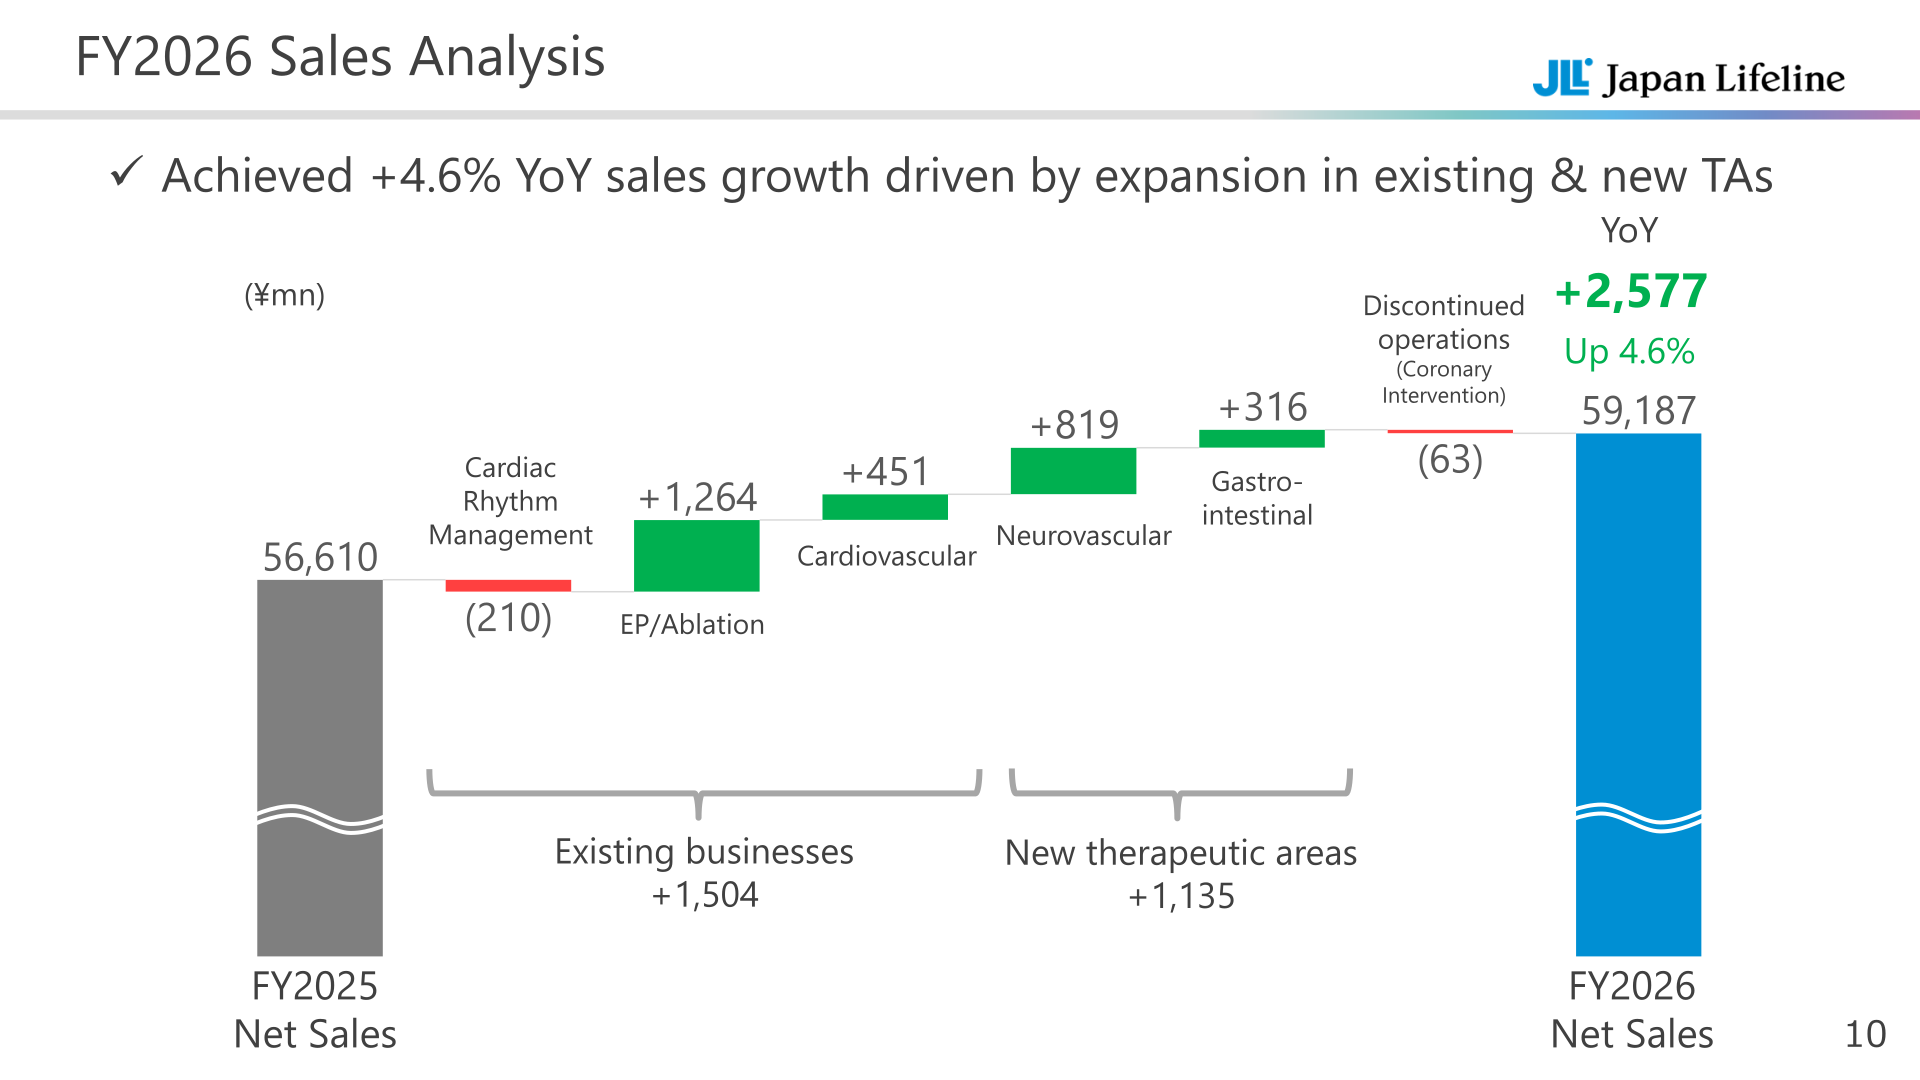
| Net sales | 59,187 | 56,610 | +2,577 | +4.6% |
| Gross profit | 35,174 | 34,191 | +983 | +2.9% |
| Gross margin | 59.4% | 60.4% | (100bps) | — |
| SG&A | 22,567 | 21,864 | +703 | +3.2% |
| Operating profit | 12,606 | 12,326 | +280 | +2.3% |
| Operating margin | 21.3% | 21.8% | (50bps) | — |
| Net income (profit attributable to owners of parent) | 9,350 | 9,317 | +32 | +0.4% |
| Net margin | 15.8% | 16.5% | (70bps) | — |
| Proprietary sales mix | 56.0% | 57.4% | (140bps) | — |
| International sales mix | 2.5% | 1.9% | +60bps | — |
| Basic EPS (¥) | 133.30 | 131.43 | +1.87 | +1.4% |
Against the initial full-year guidance, net sales came in at 99.8% and operating profit at 97.7%, while net income landed at 100.4%, aided by tax credits. In the operating profit bridge, sales and cost of goods sold factors contributed +¥983mn while SG&A-related factors were a ¥703mn drag; core products added ¥1,708mn (intracardiac defibrillation catheter BeeAT +¥888mn, hemostatic device +¥685mn, Frozen Elephant Trunk +¥128mn, S-ICD +¥6mn) and new therapeutic areas added ¥646mn (neurovascular +¥349mn, gastrointestinal +¥296mn, PFA impact (¥1,094mn)).
On the balance sheet, total assets increased ¥5,088mn to ¥80,211mn as of March 31, 2026, driven mainly by inventory (¥20,129mn versus ¥17,961mn) and production facility investment, while net assets rose to ¥65,897mn and the capital-to-asset ratio improved to 82.1% from 79.8%. Operating cash flow was +¥8,172mn, investing cash flow (¥2,048mn) and financing cash flow (¥4,581mn), lifting the cash balance by ¥1,479mn to ¥12,494mn.
Segment Results
Sales growth of 4.6% was driven by existing businesses (+¥1,504mn) and new therapeutic areas (+¥1,135mn). Existing businesses accounted for 92% of sales and new therapeutic areas 8% in FY2026. EP/Ablation grew 4.5% as atrial fibrillation procedure volume rose nearly 10% year on year, with the intracardiac defibrillation catheter up 7.6% (volume +8.6%, estimated 95% market share as of March 2026) and the femoral vein hemostatic device up 61.7%, offsetting a 47.6% decline in the esophageal temperature monitoring catheter as PFA penetration reached 65% of all AF cases. Cardiac Rhythm Management declined 1.6% as pacemaker-related sales fell 14.2% on competitor leadless devices, partly offset by S-ICD (+0.4%) and the newly launched lead extraction business.
| Segment | FY2026 (¥mn) | FY2025 (¥mn) | YoY |
|---|---|---|---|
| Cardiac Rhythm Management | 13,057 | 13,267 | (1.6%) |
| EP/Ablation | 29,109 | 27,845 | +4.5% |
| Cardiovascular | 12,657 | 12,206 | +3.7% |
| Neurovascular | 2,661 | 1,842 | +44.5% |
| Gastrointestinal | 1,661 | 1,345 | +23.5% |
Cardiovascular grew 3.7%, with Frozen Elephant Trunk up 3.9% (domestic market volume +3.1%, an estimated 90% market share as of March 2026) and vascular grafts up 4.6% on competitor product line exits, while EVAR fell 1.7% on intensified competition. Neurovascular grew 44.5%, with the aspiration catheter at 1.7x year on year (estimated 20% market share), embolic coils +19.6% and stent retrievers at 2.0x. Gastrointestinal grew 23.5% excluding the discontinued PCI business, led by bile-duct tube stents (+49.3%), ERCP guidewires (2.2x) and GI stents (+10.0%), against a 34.0% decline in the liver cancer ablation needle; on a reported basis including PCI, Gastrointestinal net sales were ¥1,448mn in FY2025 versus ¥1,701mn in FY2026 (+17.4% year on year).
FY2027 Guidance
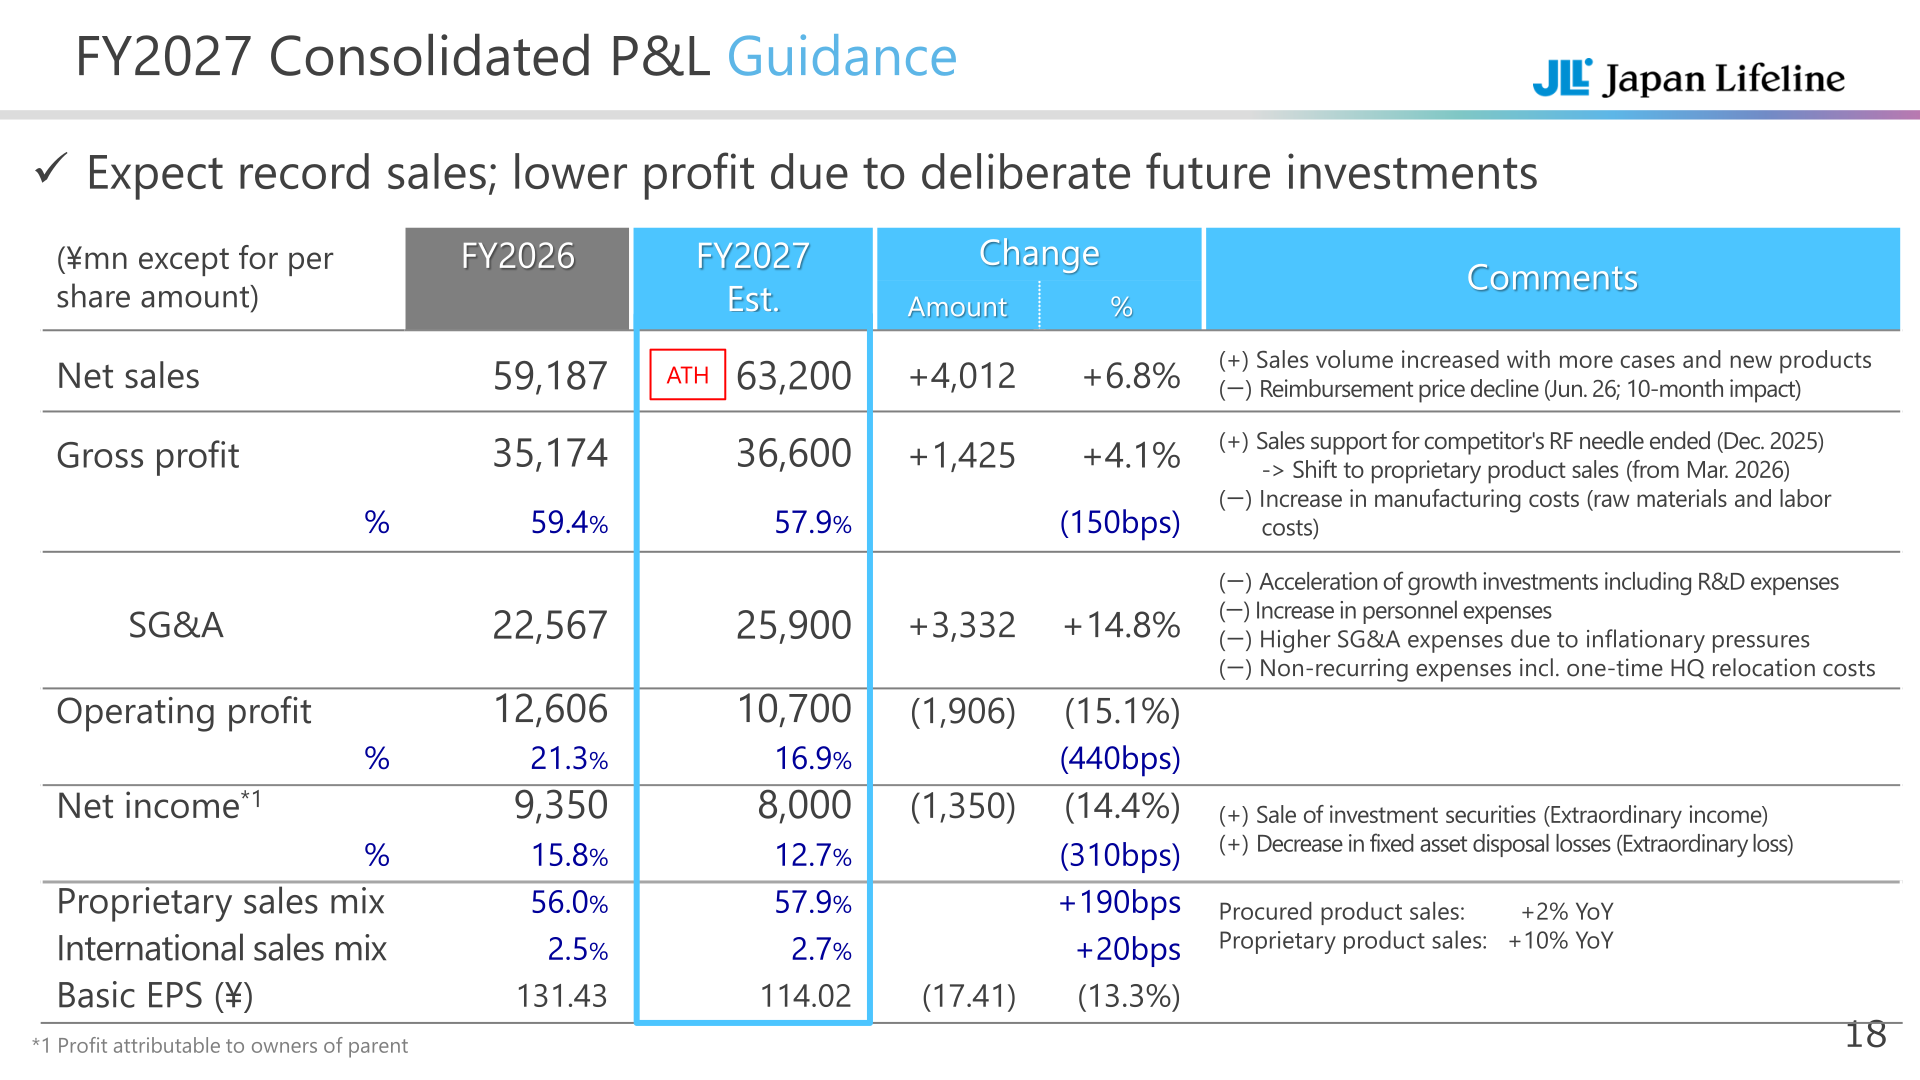
The company guides for record net sales of ¥63,200mn (+6.8%) but lower profits, summarising the year as “Solid sales drive topline growth, but profit declines due to HQ relocation and growth investments.” Positives cited are solid core product sales and AF procedure volume growth of 9% year on year; negatives are the acceleration of growth investments, headquarters relocation costs, a reimbursement price decline from June 2026, and higher manufacturing costs and SG&A due to inflation. Basic EPS is guided at ¥114.02.
| Item (¥mn) | FY2027 Guidance | FY2026 (Actual) | Change | % |
|---|---|---|---|---|
| Net sales | 63,200 | 59,187 | +4,012 | +6.8% |
| Gross profit | 36,600 | 35,174 | +1,425 | +4.1% |
| Gross margin | 57.9% | 59.4% | (150bps) | — |
| SG&A | 25,900 | 22,567 | +3,332 | +14.8% |
| Operating profit | 10,700 | 12,606 | (1,906) | (15.1%) |
| Operating margin | 16.9% | 21.3% | (440bps) | — |
| Net income | 8,000 | 9,350 | (1,350) | (14.4%) |
| Net margin | 12.7% | 15.8% | (310bps) | — |
| Proprietary sales mix | 57.9% | 56.0% | +190bps | — |
| International sales mix | 2.7% | 2.5% | +20bps | — |
In the FY2027 operating profit bridge, sales volume impact contributes +¥2,450mn (core products +¥2,520mn, including defibrillation catheter +¥1,200mn and RF wire +¥880mn; new therapeutic areas +¥420mn; other products (¥490mn)), while unit price and other factors are (¥1,025mn), growth investments (¥1,217mn) including R&D investment (¥1,040mn) and the Malaysia factory (¥260mn), SG&A increases (¥1,300mn) and one-off factors (¥814mn) including headquarters relocation (¥596mn). The June 2026 reimbursement price revision is expected to reduce net sales by ¥410mn in total, significantly lighter than the ¥1,030mn impact of the previous June 2024 revision.
| Segment | FY2027 Guidance (¥mn) | FY2026 (Actual, ¥mn) | YoY |
|---|---|---|---|
| Cardiac Rhythm Management | 13,070 | 13,057 | +0.1% |
| EP/Ablation | 31,870 | 29,109 | +9.5% |
| Cardiovascular | 13,180 | 12,657 | +4.1% |
| Neurovascular | 3,130 | 2,661 | +17.6% |
| Gastrointestinal | 1,950 | 1,661 | +17.4% |
Shareholder Returns
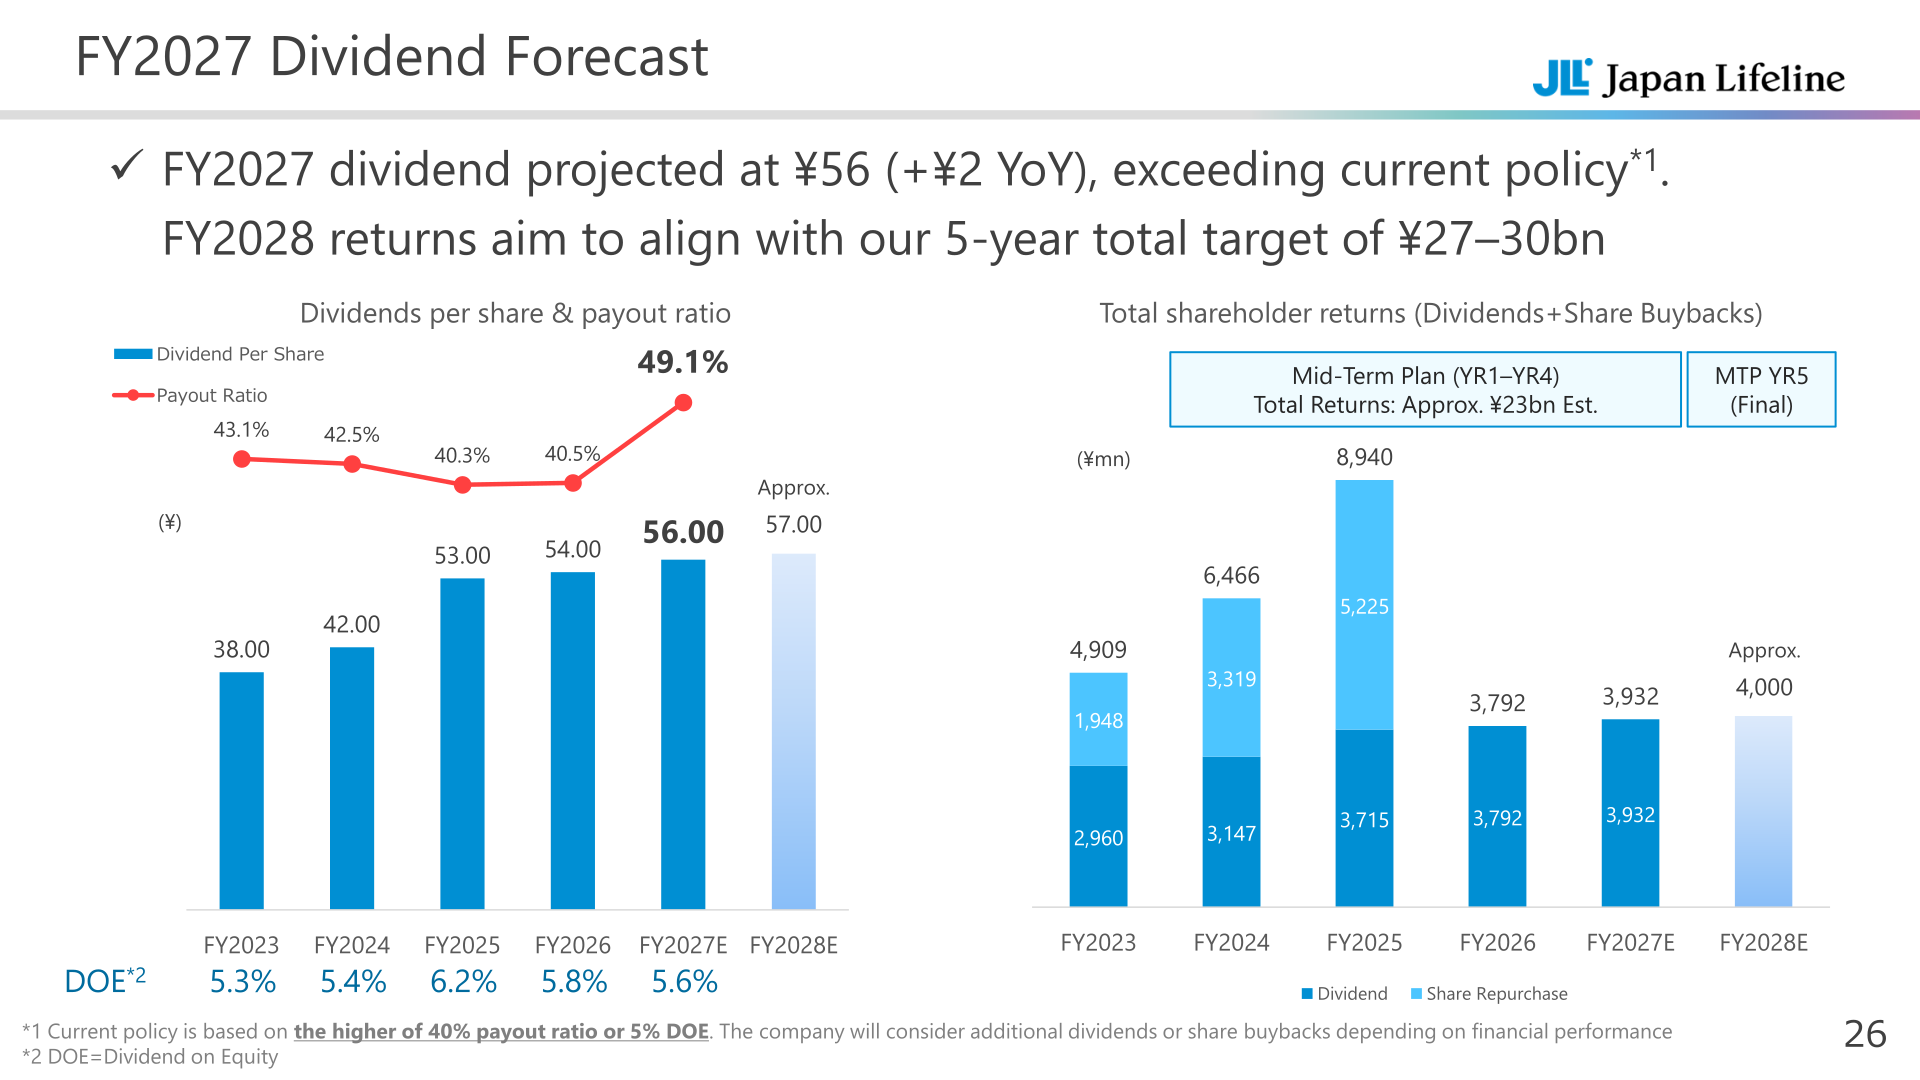
The FY2027 dividend is projected at ¥56 per share, up ¥2 year on year and, in the company’s words, exceeding the current policy. The current policy is based on the higher of a 40% payout ratio or 5% DOE (dividend on equity), with additional dividends or share buybacks to be considered depending on financial performance. Total shareholder returns over years one to four of the mid-term plan are estimated at approximately ¥23bn, and FY2028 returns are intended to align with the five-year total target of ¥27–30bn. Under the FY2026–FY2028 cash allocation policy, excess cash — defined as cash on hand exceeding ¥10.0bn, with approximately ¥3.0bn retained as a buffer — is to be actively considered for shareholder returns if no M&A opportunities arise.
| Item | FY2025 | FY2026 | FY2027 (Est.) | FY2028 (Est.) |
|---|---|---|---|---|
| Dividend per share (¥) | 53.00 | 54.00 | 56.00 | Approx. 57.00 |
| Payout ratio | 40.3% | 40.5% | 49.1% | — |
Medium-Term Plan and Topics
Through year three of the mid-term plan, net sales grew at a 4.6% CAGR and operating profit at a 5.2% CAGR. The company states that the FY2028 net sales target of ¥70bn remains intact despite TAVI-related launch delays, partially offset by projected growth in proprietary RF wire sales in EP/Ablation, but that sales are currently tracking slightly below plan and the FY2028 operating margin target of approximately 20% is currently tracking below plan. The FY2028 EPS target of ¥145 and ROIC target of 13% — against a cost of capital (WACC) of 8–9% — are also described as tracking below target due to margin compression, and the company is prioritising inventory optimisation, targeting roughly 250 inventory turnover days, to enhance capital efficiency.
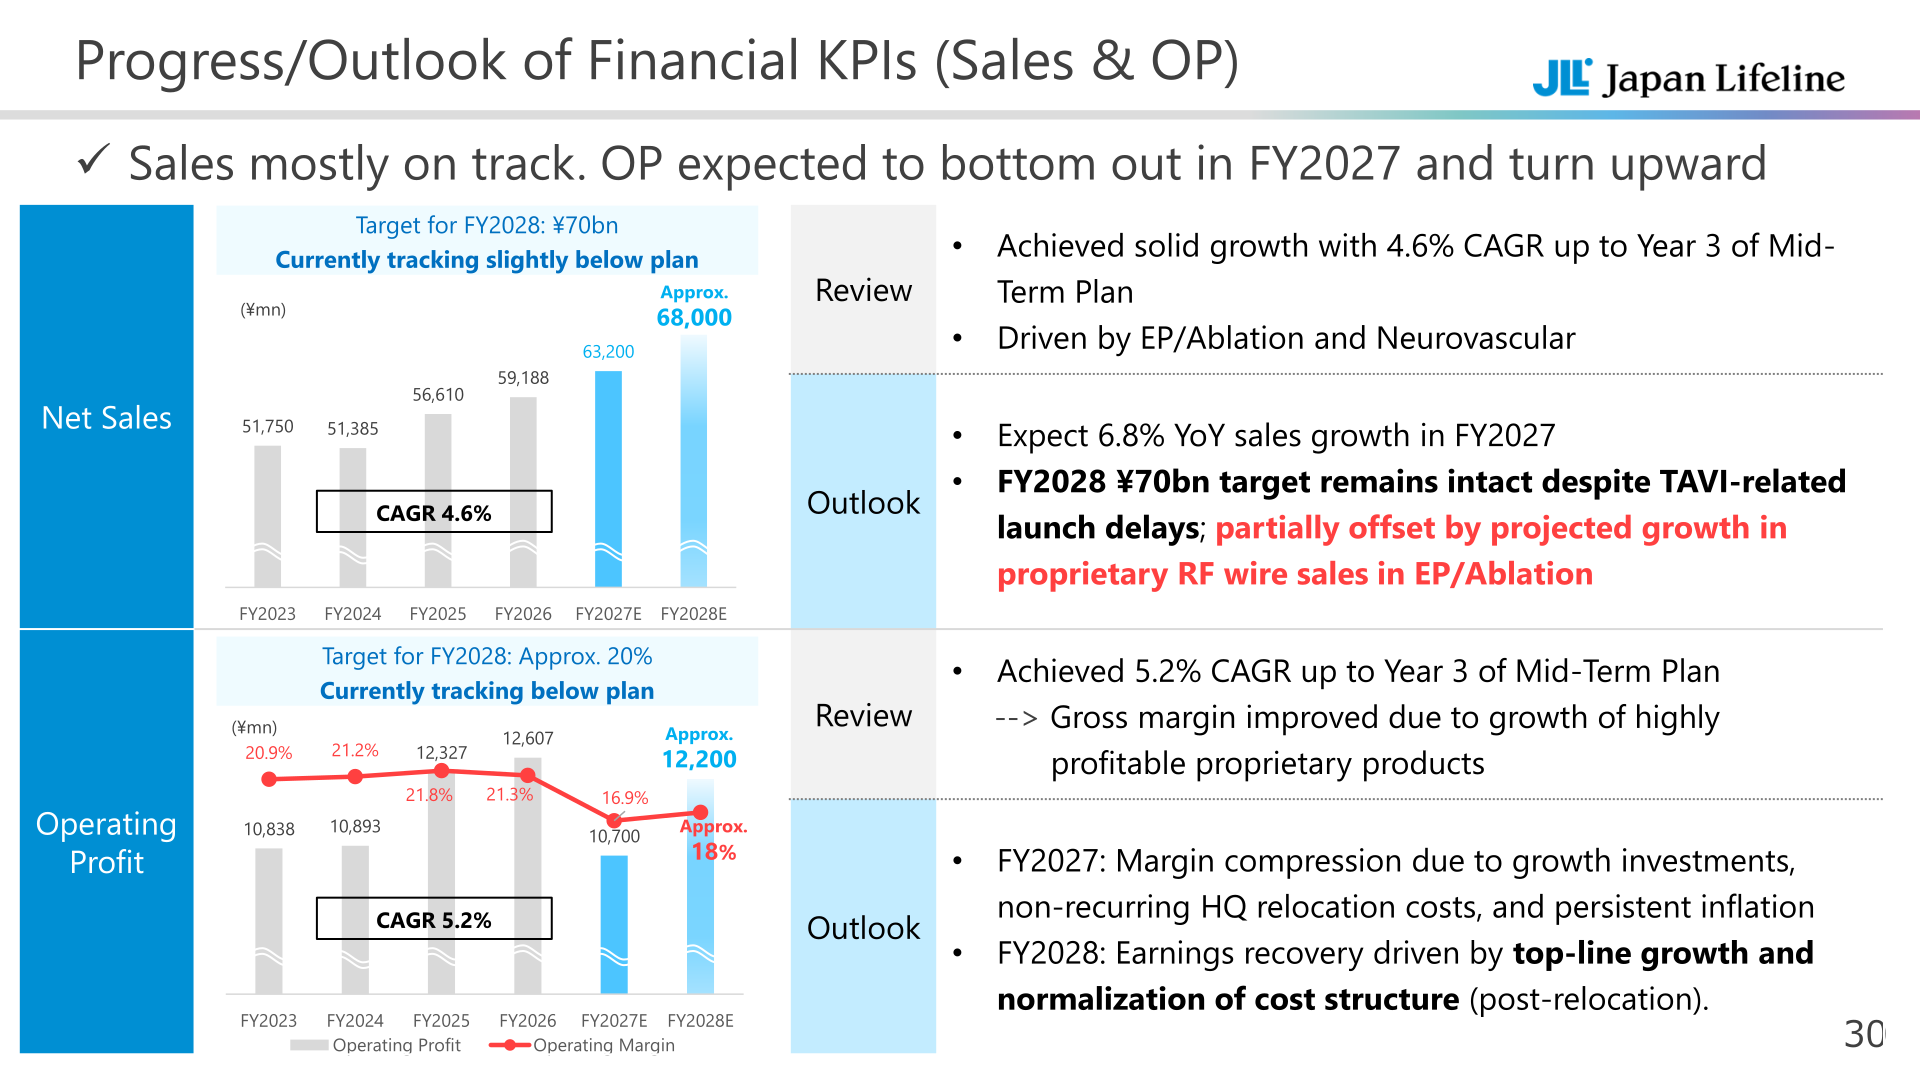
R&D investment is expected to peak in FY2027–FY2028 and normalise from FY2029, with the company aiming to maintain an R&D-to-proprietary-sales ratio of 8–10%. Within FY2027 R&D of ¥2,432mn, ¥750mn is allocated to EP/Ablation PFA catheters (co-development with CardioFocus plus in-house development, targeting an OEM supply around 2027 and a Japan launch around 2030), ¥450mn to EP/Ablation peripheral devices, ¥400mn to Cardiovascular, and ¥832mn to other areas including gastrointestinal and regenerative medicine.
Reviewing growth strategy progress as of March 2026, the company rates EP/Ablation as having exceeded plan (95% share maintained in defibrillation catheters and hemostatic device penetration above expectations), Cardiovascular, Neurovascular, the global rollout and OEM initiatives as on plan, Gastrointestinal as lagging (withdrawal from cholangioscopy amid competition from new Chinese entrants, with the business missing initial sales targets), and structural heart disease as delayed, with a significant launch delay expected while the regulatory strategy is reassessed.
On valuation, the shares closed at ¥1,369 as of March 31, 2026, with a P/E sustained in the low 10x range since FY2022 and a P/B of approximately 1.5x, against a peer group average P/E of 24.3x and P/B of 2.9x for ten globalised domestic medtech companies as of April 2026. The company targets a P/E of 15–18x and a P/B of 2–3x through FY2028, and above 20x and above 3x over the long term, alongside raising average daily trading volume from ¥260mn towards more than ¥300mn.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















