
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: SRS HOLDINGS CO., LTD.’s presentation labels the fiscal year ended March 31, 2026, as “FY3/26” and the prior fiscal year as “FY3/25.” This article follows japan-equity.com’s convention of referring to the most recently completed fiscal year as FY2025; tables and figures below retain the source presentation’s original “FY3/25″/”FY3/26” labels, and the following fiscal year is referred to as FY3/27 (the company’s own label) in body text and tables, matching the source.
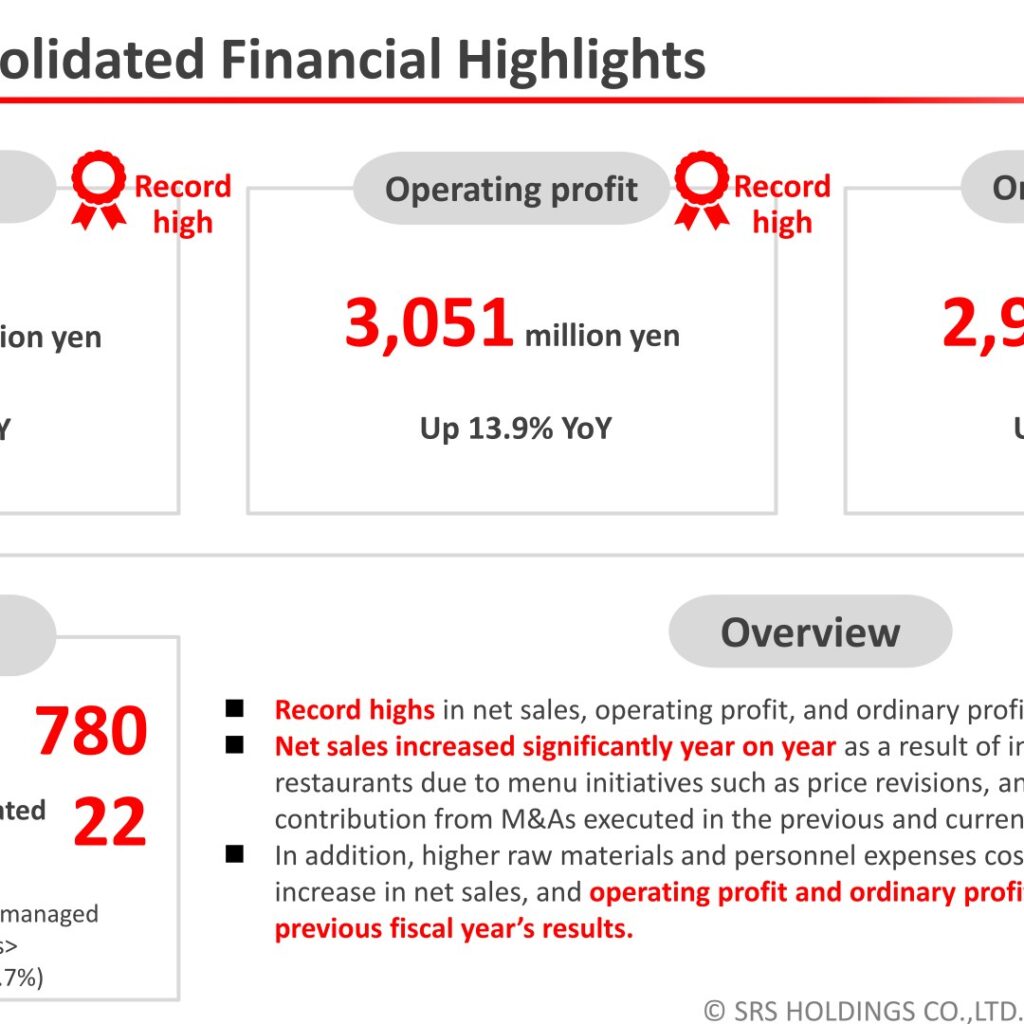
SRS HOLDINGS CO., LTD., which operates Japanese restaurant chains including Washoku Sato, Nigiri Chojiro and Umai Sushikan, reported record consolidated results for the fiscal year ended March 31, 2026: net sales of 76,421 million yen (up 13.3% year on year), operating profit of 3,051 million yen (up 13.9%), and ordinary profit of 2,994 million yen (up 17.9%), all record highs. Profit attributable to owners of parent rose 83.1% to 1,694 million yen. The company said net sales increased significantly year on year due to higher sales at existing restaurants from menu initiatives such as price revisions, and the consolidated contribution from M&As executed in the previous and current fiscal years; higher raw material and personnel expense costs were absorbed by the increase in net sales. The Group operated 780 restaurants at fiscal year-end, following 22 new company-operated restaurant openings against an annual target of 34 (a 64.7% progress rate).
Consolidated Results (Full-Year Actual)
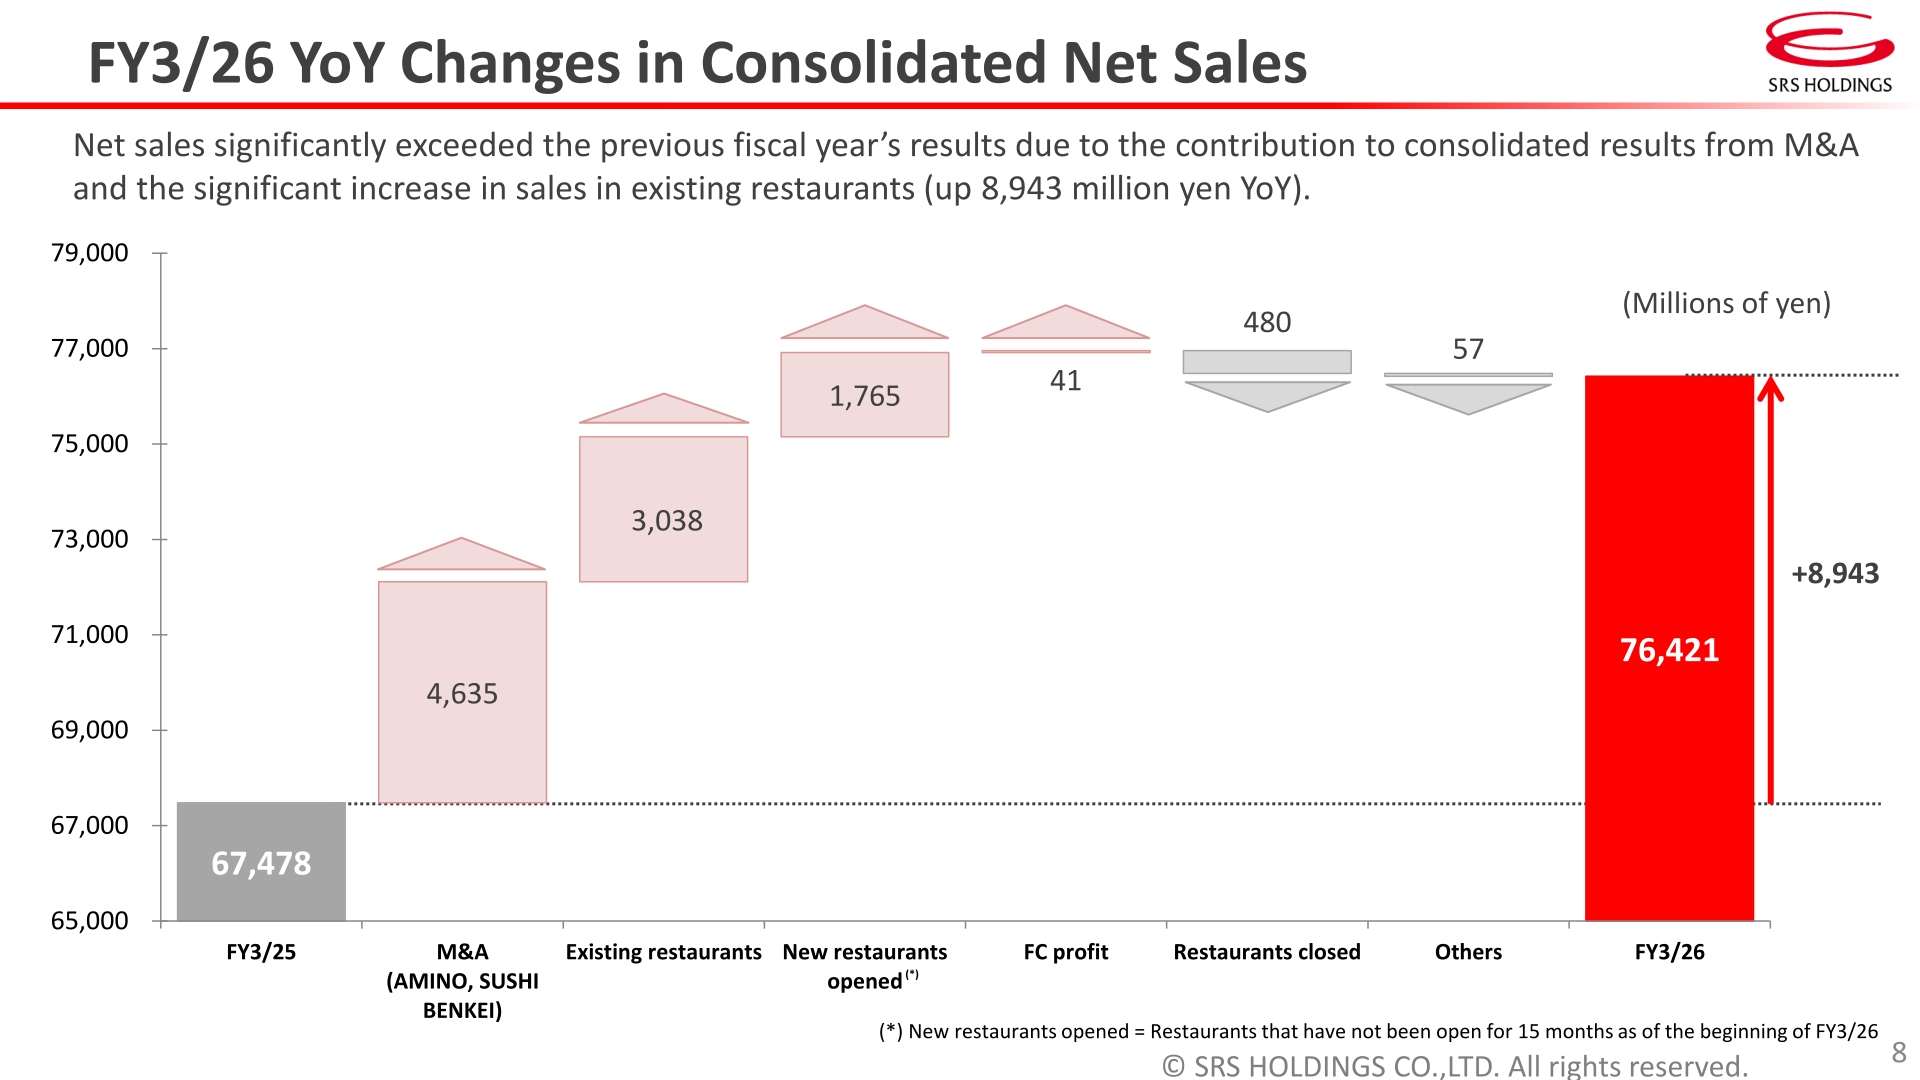
Net sales, operating profit and ordinary profit all exceeded the company’s full-year plan. Net sales increased by 8,943 million yen year on year, mainly due to a rise in average sales per customer from menu measures including price revisions, an increase in revenue from M&As, and contributions from new restaurant openings. Profit attributable to owners of parent increased by 768 million yen (up 83.1%) year on year due to the sales increase and a gain on sales of shares recorded in extraordinary income.
| Item | FY3/25 (Amount; % of Sales) | FY3/26 (Amount; % of Sales) | YoY Change (Amount) | YoY Change (%) | FY3/26 Full-Year Plan | Achievement Rate |
|---|---|---|---|---|---|---|
| Net sales | 67,478 | 76,421 | +8,943 | +13.3% | 76,000 | 100.6% |
| Cost of sales | 22,914 (34.0%) | 26,290 (34.4%) | +3,375 | +14.7% | – | – |
| Gross profit | 44,563 (66.0%) | 50,131 (65.6%) | +5,568 | +12.5% | – | – |
| SG&A | 41,884 (62.1%) | 47,080 (61.6%) | +5,195 | +12.4% | – | – |
| Operating profit | 2,678 (4.0%) | 3,051 (4.0%) | +372 | +13.9% | 3,000 | 101.7% |
| Ordinary profit | 2,539 (3.8%) | 2,994 (3.9%) | +454 | +17.9% | 2,800 | 106.9% |
| Extraordinary income | 2 (0.0%) | 568 (0.7%) | +566 | +22690.3% | – | – |
| Extraordinary losses | 928 (1.4%) | 641 (0.8%) | (287) | (30.9%) | – | – |
| Profit attributable to owners of parent | 925 (1.4%) | 1,694 (2.2%) | +768 | +83.1% | 1,600 | 105.9% |
(Unit: millions of yen, as reported.) On the balance sheet, total assets increased 1,201 million yen year on year to 47,145 million yen, mainly due to increases in current assets (cash and cash equivalents and accounts receivable – trade). Total liabilities decreased 218 million yen to 28,704 million yen, mainly due to a decrease in non-current liabilities (bonds payable). Total net assets rose 1,419 million yen to 18,441 million yen, mainly reflecting the increase in net assets from profit attributable to owners of parent, and the equity ratio improved to 37.8% from 35.9%. Net interest-bearing debt at the end of FY3/26 decreased by 1,241 million yen year on year, due to improved ability to generate operating cash flow through business growth, improved investment efficiency, and the sale of investment securities. Cash flows from operating activities were 4,871 million yen (up 1,193 million yen year on year), cash flows from investing activities were -2,759 million yen (an improvement of 7,701 million yen, mainly due to the absence of payments for the acquisition of new subsidiaries seen in the prior year and the sale of investment securities), and cash flows from financing activities were -1,397 million yen (a decrease of 8,376 million yen because of funding for M&A in the previous fiscal year).
| Item (Millions of yen) | FY3/25 | FY3/26 | Change |
|---|---|---|---|
| Total assets | 45,944 | 47,145 | +1,201 |
| Current assets | 18,090 | 19,319 | +1,228 |
| (Cash and cash equivalents) | 12,567 | 13,287 | +719 |
| Non-current assets | 27,743 | 27,742 | (1) |
| Total deferred assets | 109 | 83 | (25) |
| Total liabilities | 28,922 | 28,704 | (218) |
| (Interest-bearing debt) | 12,783 | 12,261 | (522) |
| Current liabilities | 11,184 | 12,060 | +875 |
| Non-current liabilities | 17,737 | 16,643 | (1,094) |
| Total net assets | 17,021 | 18,441 | +1,419 |
| Equity ratio | 35.9% | 37.8% | +1.9% |
Results by Business Format
SRS Holdings does not report profit by financial segment; instead, the presentation breaks down the year-on-year change in consolidated net sales by business format. Net sales exceeded the previous year’s results in all businesses. In addition to the full-year contribution to net sales from the Amino sushi business (acquired as a subsidiary in the previous fiscal year) and the start of consolidation of SUSHI BENKEI (which became a subsidiary in September 2025), net sales also increased in existing businesses such as Washoku Sato and Nigiri Chojiro.
| Business Format | YoY Change in Net Sales (Millions of yen) |
|---|---|
| Washoku Sato | +1,232 |
| Tendon Tempura Honpo Santen | +123 |
| Nigiri Chojiro | +813 |
| Kazokutei | +514 |
| Tokutoku | +350 |
| M&S Food Service Business (*1) | +960 |
| Katsuya, Karayama | +186 |
| Amino sushi business (*2) | +3,545 |
| Kaiten Sushi Hokkaido, Sushi Benkei | +1,080 |
| Others | +141 |
| Total (FY3/25: 67,478 → FY3/26: 76,421) | +8,943 |
(*1) M&S Food Service Business includes Miyamoto Munashi, Himawari, Popolamama, Mister Donut, Doutor Coffee, Oogamaya and Shinpachi Shokudo restaurants. (*2) Amino sushi business includes Umai Sushikan, Umai Sushikan Yutorogi, Umai Sushikan Bekkan Sushimasa, Ginza Sushimasa, Kaiten Sushi Marukuni and Hokkai Sanriku Sumibiyaki Marukan restaurants. As of March 31, 2026, the Group operated 780 restaurants in total (757 domestic and 23 overseas, in Thailand, Indonesia and Malaysia), and had 1,742 regular employees and 16,423 part-time workers.
FY2026 Forecast
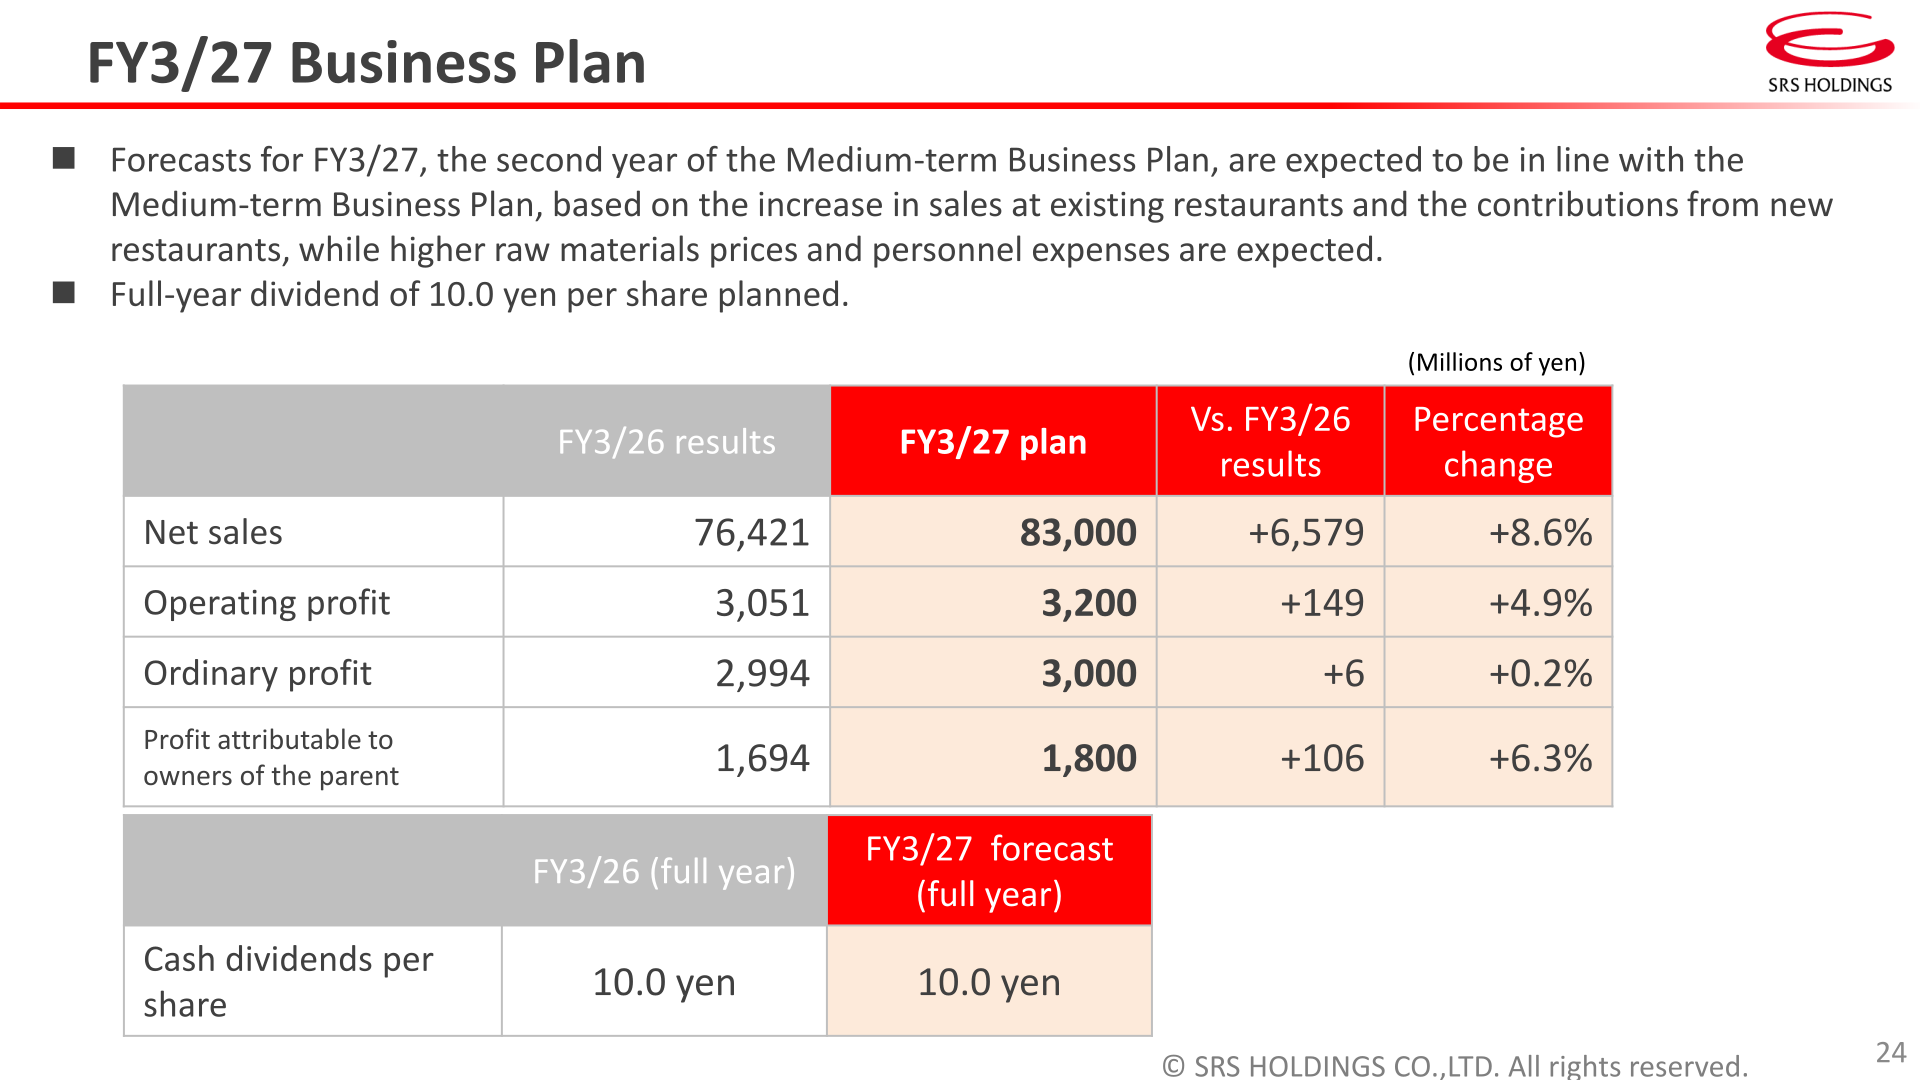
For FY3/27 (the second year of the Medium-term Business Plan), the company expects results in line with the Medium-term Business Plan, based on the increase in sales at existing restaurants and contributions from new restaurants, while higher raw materials prices and personnel expenses are expected. The company plans a total of 40 restaurant openings (37 directly-managed, 3 franchise) in its domestic restaurant businesses for FY3/27, versus 22 in FY3/26.
| Item (Millions of yen) | FY3/26 Results | FY3/27 Plan | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 76,421 | 83,000 | +6,579 | +8.6% |
| Operating profit | 3,051 | 3,200 | +149 | +4.9% |
| Ordinary profit | 2,994 | 3,000 | +6 | +0.2% |
| Profit attributable to owners of the parent | 1,694 | 1,800 | +106 | +6.3% |
Shareholder Returns
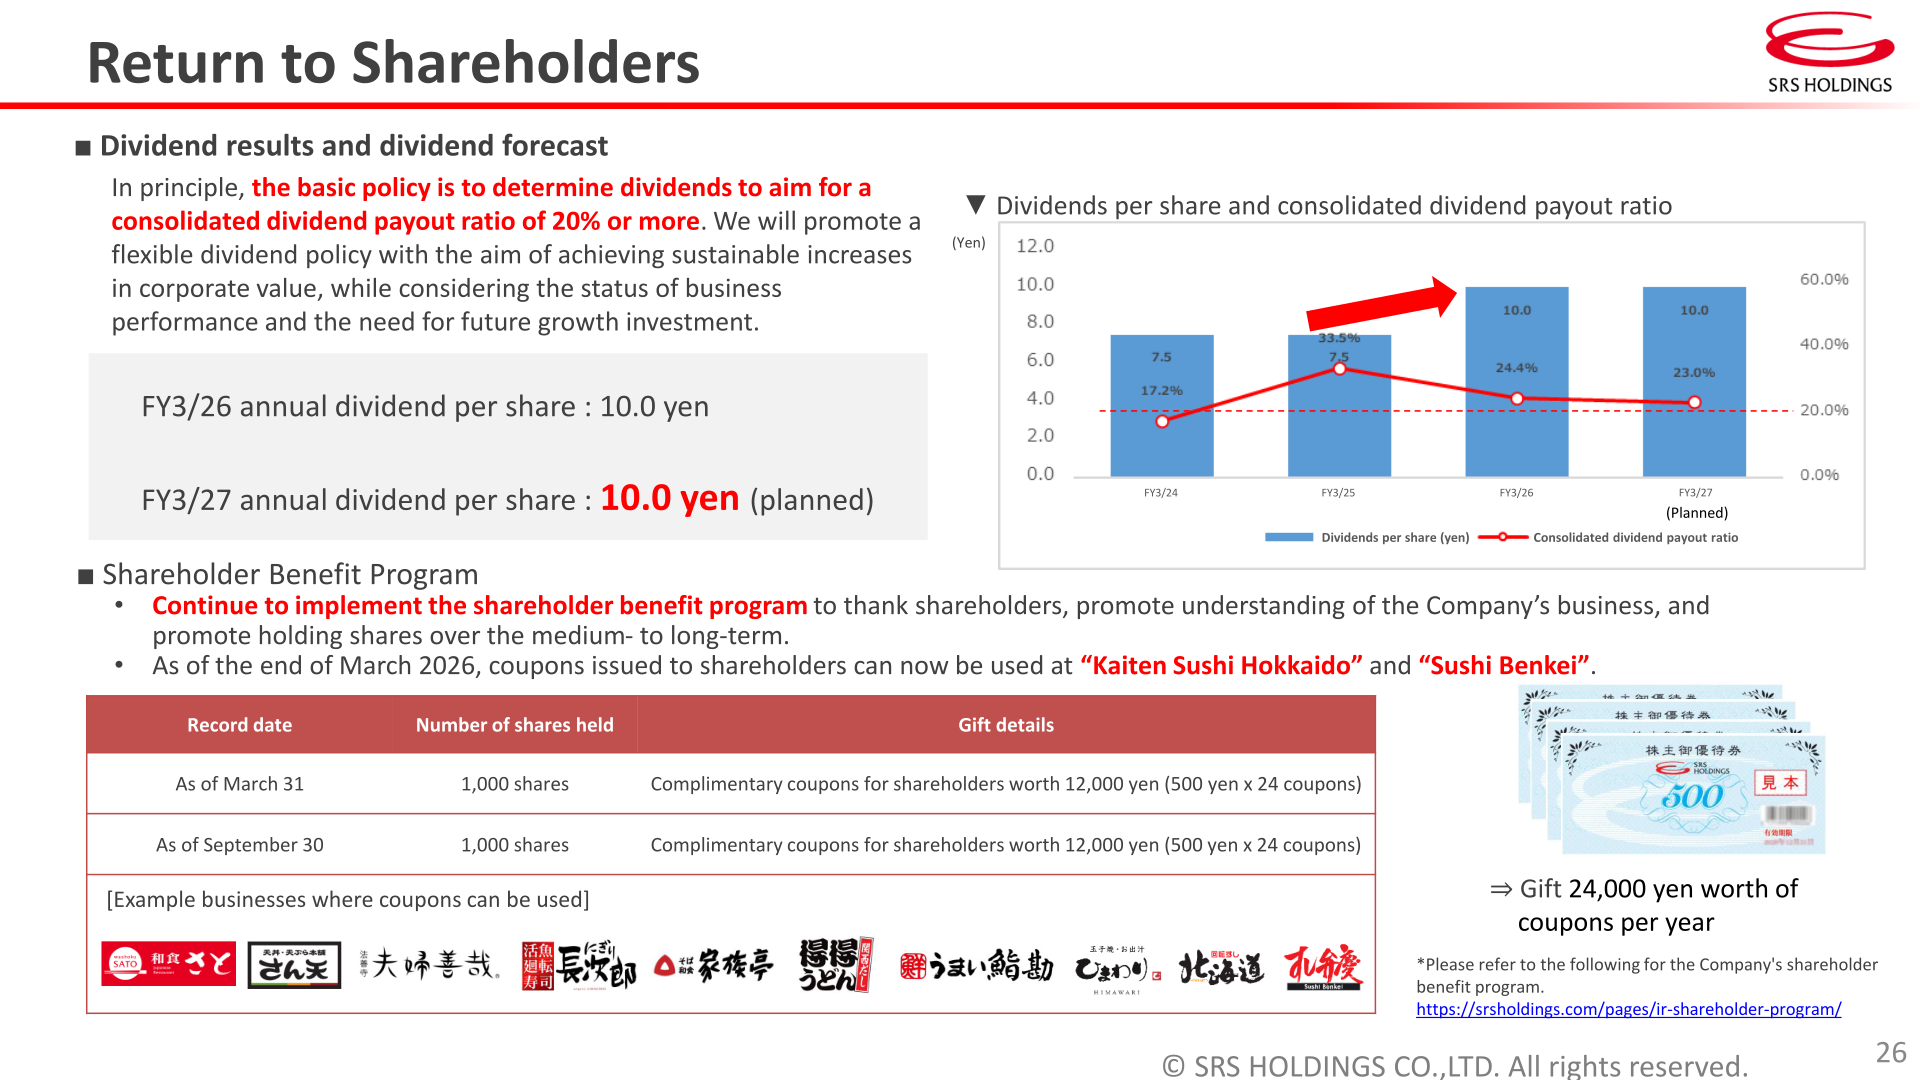
The company’s basic dividend policy, in principle, is to determine dividends aiming for a consolidated dividend payout ratio of 20% or more, while promoting a flexible dividend policy with the aim of achieving sustainable increases in corporate value. The FY3/26 annual dividend per share was 10.0 yen, and the FY3/27 annual dividend per share is planned at 10.0 yen. The company also continues its shareholder benefit program: as of the end of March 2026, coupons issued to shareholders can now be used at Kaiten Sushi Hokkaido and Sushi Benkei restaurants in addition to other Group brands; shareholders of record with 1,000 shares as of March 31 and September 30 each receive complimentary coupons worth 12,000 yen (500 yen x 24 coupons per record date), for a total of 24,000 yen worth of coupons per year.
| Fiscal Year | Dividend per Share (yen) | Consolidated Dividend Payout Ratio |
|---|---|---|
| FY3/24 | 7.5 | 17.2% |
| FY3/25 | 7.5 | 33.5% |
| FY3/26 | 10.0 | 24.4% |
| FY3/27 (Planned) | 10.0 | 23.0% |
Medium-Term Plan / Topics
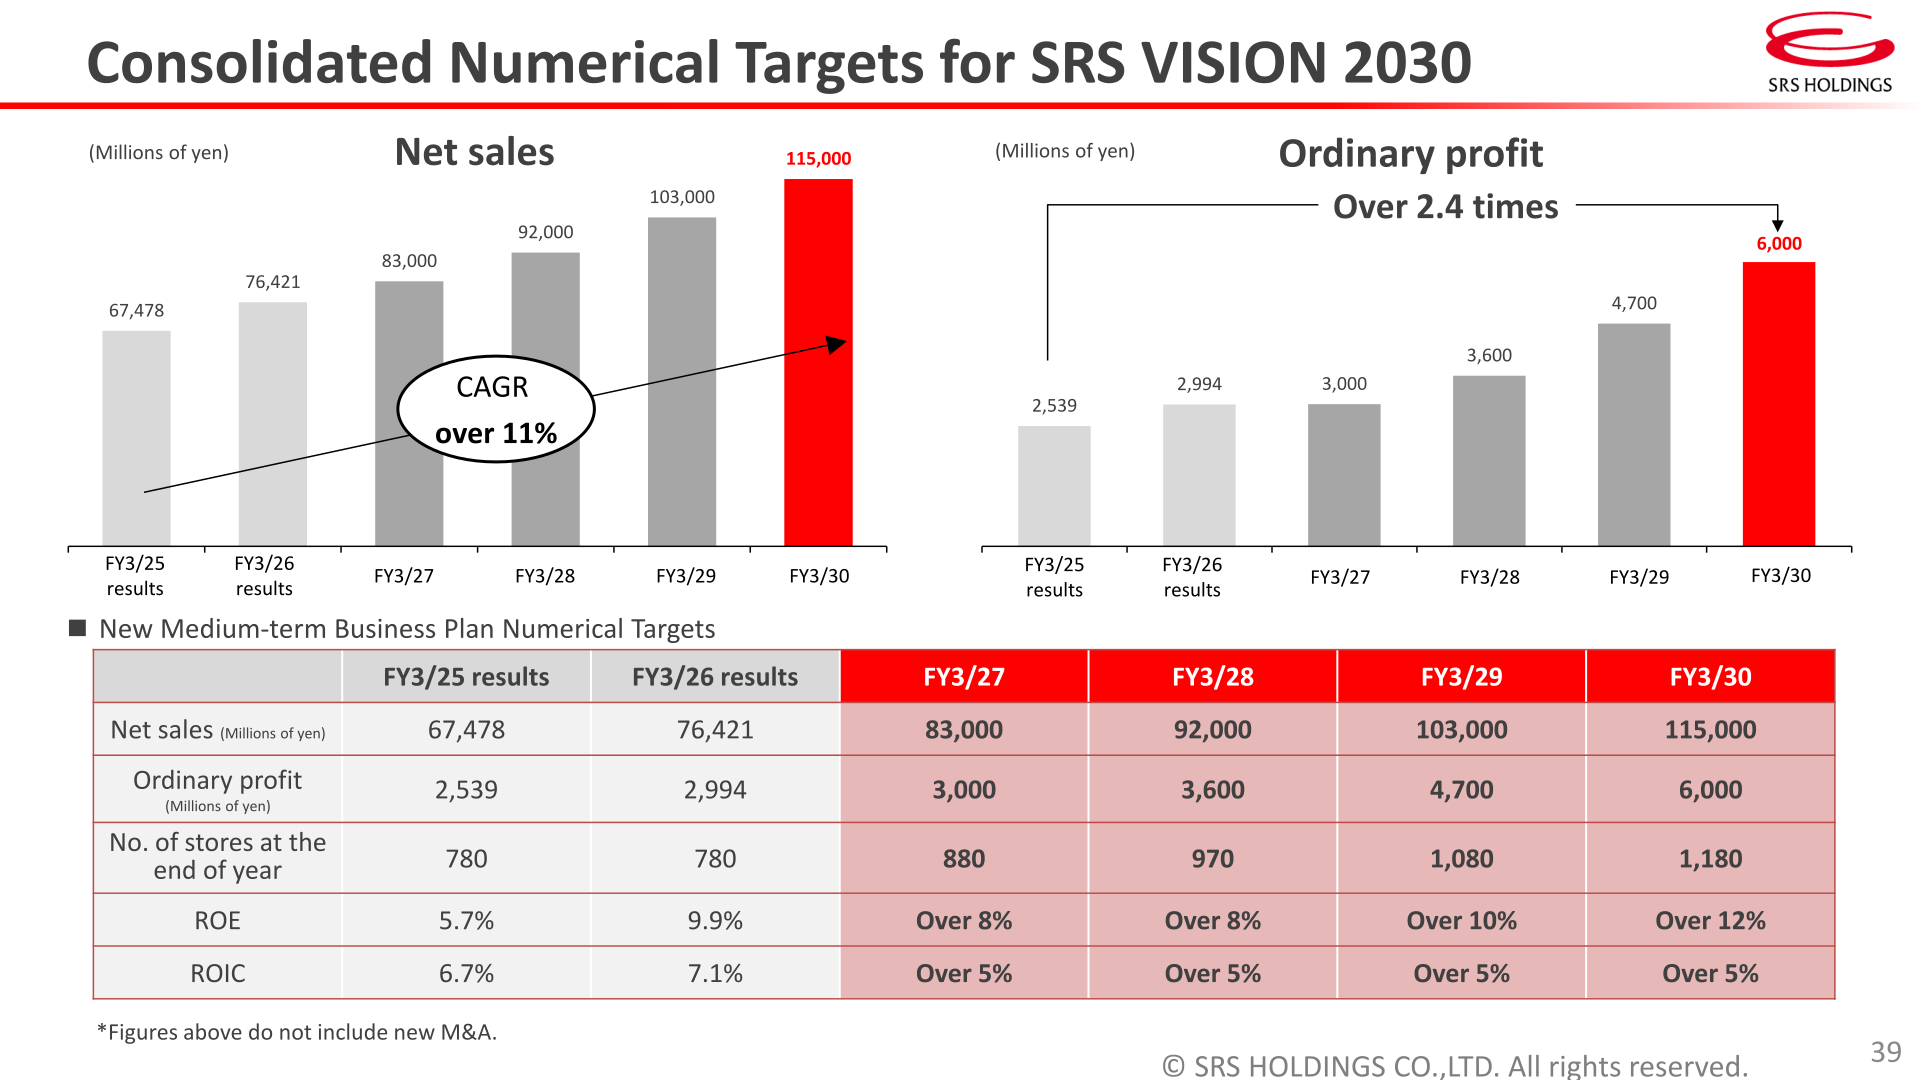
SRS Holdings is pursuing “SRS VISION 2030,” a medium-term business plan whose basic policy is to dramatically develop existing businesses and establish a new earnings base to become the unrivaled No. 1 Japanese restaurant chain, through four key strategies: establishing Washoku Sato as a national brand; achieving the overwhelming No. 1 position in the gourmet sushi chain segment with Nigiri Chojiro and Umai Sushikan; establishing businesses as the third and fourth pillars of earnings; and strengthening group functions and promoting sustainable management to support net sales of more than 100 billion yen. Under the plan (excluding new M&A), the company targets net sales of 115,000 million yen and ordinary profit of 6,000 million yen by FY3/30 (a CAGR of over 11% for net sales and over 2.4 times for ordinary profit versus FY3/25), with the number of Group stores growing from 780 to 1,180 and ROE improving to over 12.0% from 5.7% in FY3/25.
| Metric | FY3/25 Results | FY3/26 Results | FY3/27 | FY3/28 | FY3/29 | FY3/30 |
|---|---|---|---|---|---|---|
| Net sales (Millions of yen) | 67,478 | 76,421 | 83,000 | 92,000 | 103,000 | 115,000 |
| Ordinary profit (Millions of yen) | 2,539 | 2,994 | 3,000 | 3,600 | 4,700 | 6,000 |
| No. of stores at the end of year | 780 | 780 | 880 | 970 | 1,080 | 1,180 |
| ROE | 5.7% | 9.9% | Over 8% | Over 8% | Over 10% | Over 12% |
| ROIC | 6.7% | 7.1% | Over 5% | Over 5% | Over 5% | Over 5% |
(Figures above do not include new M&A.) Under Key Strategy I, the three Washoku Sato restaurants opened in Okayama prefecture (a new business area) in FY3/26 recorded average sales 42% above the average for new restaurants opened in the past three years; the company plans to open 5 Washoku Sato restaurants in FY3/27 and a cumulative 35 restaurants over the four years to FY3/30, expanding beyond the Chugoku and Shikoku regions. Under Key Strategy II, the Nigiri Chojiro Wakayama Hirai restaurant (opened March 2026, the first of a new restaurant design) recorded sales 110% above the average at existing restaurants, and two new Umai Sushikan Yutorogi restaurants recorded sales 26% and 22% above the average at existing Yutorogi restaurants. The company estimates the gourmet sushi market at approximately 150 billion yen, with the SRS Group holding approximately a 16% share, and plans to grow the number of gourmet sushi chain restaurants in the Group from 109 (as of the end of FY3/26) to more than 150 by the end of FY3/30, including growth from 73 to 101 restaurants for Nigiri Chojiro, 26 to 41 for Umai Sushikan (which includes Umai Sushikan Yutorogi, Umai Sushikan Bekkan Sushimasa, and Ginza Sushimasa), 6 to 10 for Kaiten Sushi Hokkaido and Sushi Benkei, and 4 to 6 for Marukuni.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















