
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
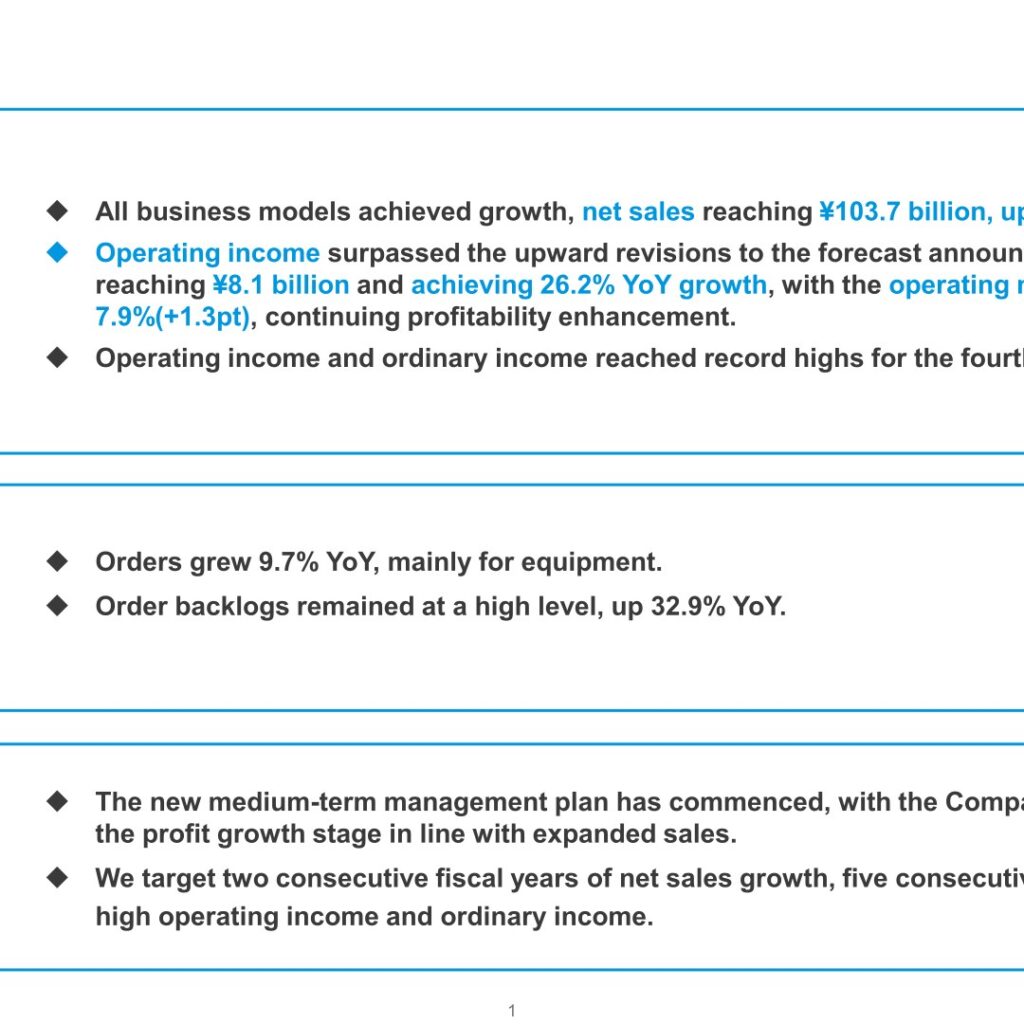
Tsuzuki Denki Co., Ltd. (TSE: 8157), an information and communication services company, reported consolidated net sales of ¥103,728 million for the fiscal year ended March 31, 2026 (FY03/26), up 5.6% year on year, with growth across all of its business models. Operating profit rose 26.2% to ¥8,178 million and ordinary profit rose to ¥8,320 million (126.1% of the previous year), both marking record highs for the fourth consecutive fiscal year; profit attributable to owners of parent increased to ¥6,472 million (135.9% of the previous year). Orders grew 9.7% year on year and the order backlog rose 32.9%, remaining at a high level. For the fiscal year ending March 31, 2027 (FY03/27), the Company has launched a new medium-term management plan, “Trust & Challenge 2029,” and forecasts continued growth in net sales, operating profit and ordinary profit.
Note: Tsuzuki Denki refers to the fiscal year ended March 31, 2026 as “FY03/26” in its disclosures; this is treated as FY2025 in this article’s title and site categorization, while the tables and figures below retain the Company’s own FY03/25–FY03/27 fiscal-year labels as presented in its materials.
Consolidated Results (FY03/26 Actual)
In the fiscal year ended March 31, 2026, all three of Tsuzuki Denki’s business models — Equipment, Development & Construction, and Service — achieved growth, driving net sales up 5.6% year on year. Gross profit increased to ¥24,965 million (110.2% of the previous year), with the gross margin improving to 24.1% from 23.1%. Operating profit rose 26.2% to ¥8,178 million, with the operating margin improving 1.3 points to 7.9%, and profit attributable to owners of parent rose to ¥6,472 million (135.9% of the previous year).
| Item | FY03/25 | FY03/26 | YoY Change |
|---|---|---|---|
| Net sales | 98,263 | 103,728 | +5,464 (105.6%) |
| Gross profit | 22,665 (23.1%) | 24,965 (24.1%) | +2,300 (110.2%) |
| SG&A expenses | 16,183 (16.5%) | 16,787 (16.2%) | +604 (103.7%) |
| Operating profit | 6,481 (6.6%) | 8,178 (7.9%) | +1,696 (126.2%) |
| Ordinary profit | 6,596 (6.7%) | 8,320 (8.0%) | +1,724 (126.1%) |
| Profit attributable to owners of parent | 4,764 (4.8%) | 6,472 (6.2%) | +1,708 (135.9%) |
(Millions of yen; figures in parentheses in the FY03/25 and FY03/26 columns show composition ratio to net sales.)
Net Sales by Business Model
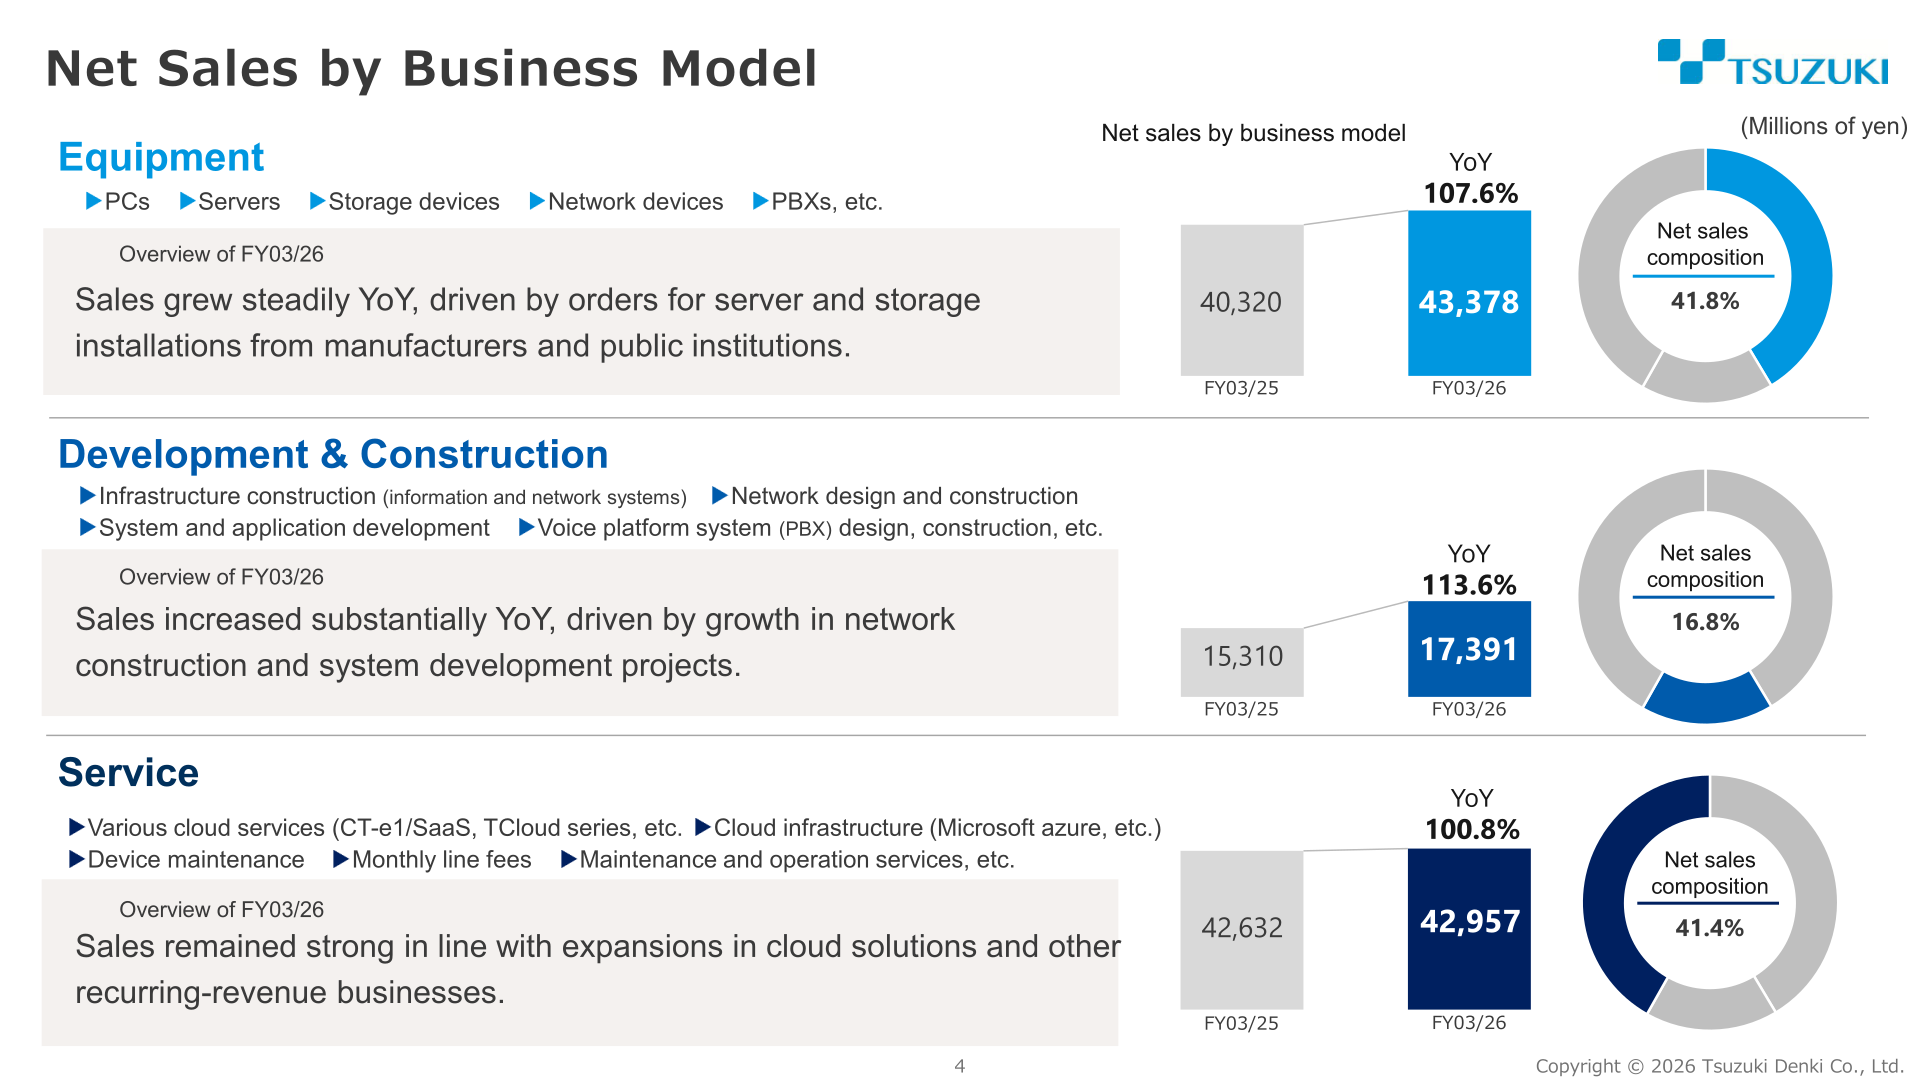
Equipment net sales increased to ¥43,378 million (107.6% of the previous year), driven by orders for server and storage installations from manufacturers and public institutions. Development & Construction net sales rose to ¥17,391 million (113.6% of the previous year) on growth in network construction and system development projects. Service net sales advanced to ¥42,957 million (100.8% of the previous year), supported by continued expansion in cloud solutions and other recurring-revenue businesses. Company-wide orders grew 9.7% year on year to ¥110,384 million and the order backlog rose 32.9% to ¥26,902 million; by business model, Equipment orders totaled ¥49,891 million (124.3% of the previous year) with its order backlog at ¥16,904 million (162.7% of the previous year), Development & Construction orders totaled ¥17,055 million (104.8% of the previous year) while its order backlog was ¥4,115 million (92.4% of the previous year) as sales were fulfilled, and Service orders totaled ¥43,437 million (98.3% of the previous year) following the conclusion of a large deal in FY03/25, though its order backlog was ¥5,883 million (108.9% of the previous year) and remained at a high level.
| Business Model | FY03/25 Net Sales | FY03/26 Net Sales | YoY |
|---|---|---|---|
| Equipment | 40,320 | 43,378 | 107.6% |
| Development & Construction | 15,310 | 17,391 | 113.6% |
| Service | 42,632 | 42,957 | 100.8% |
FY2026 Forecast
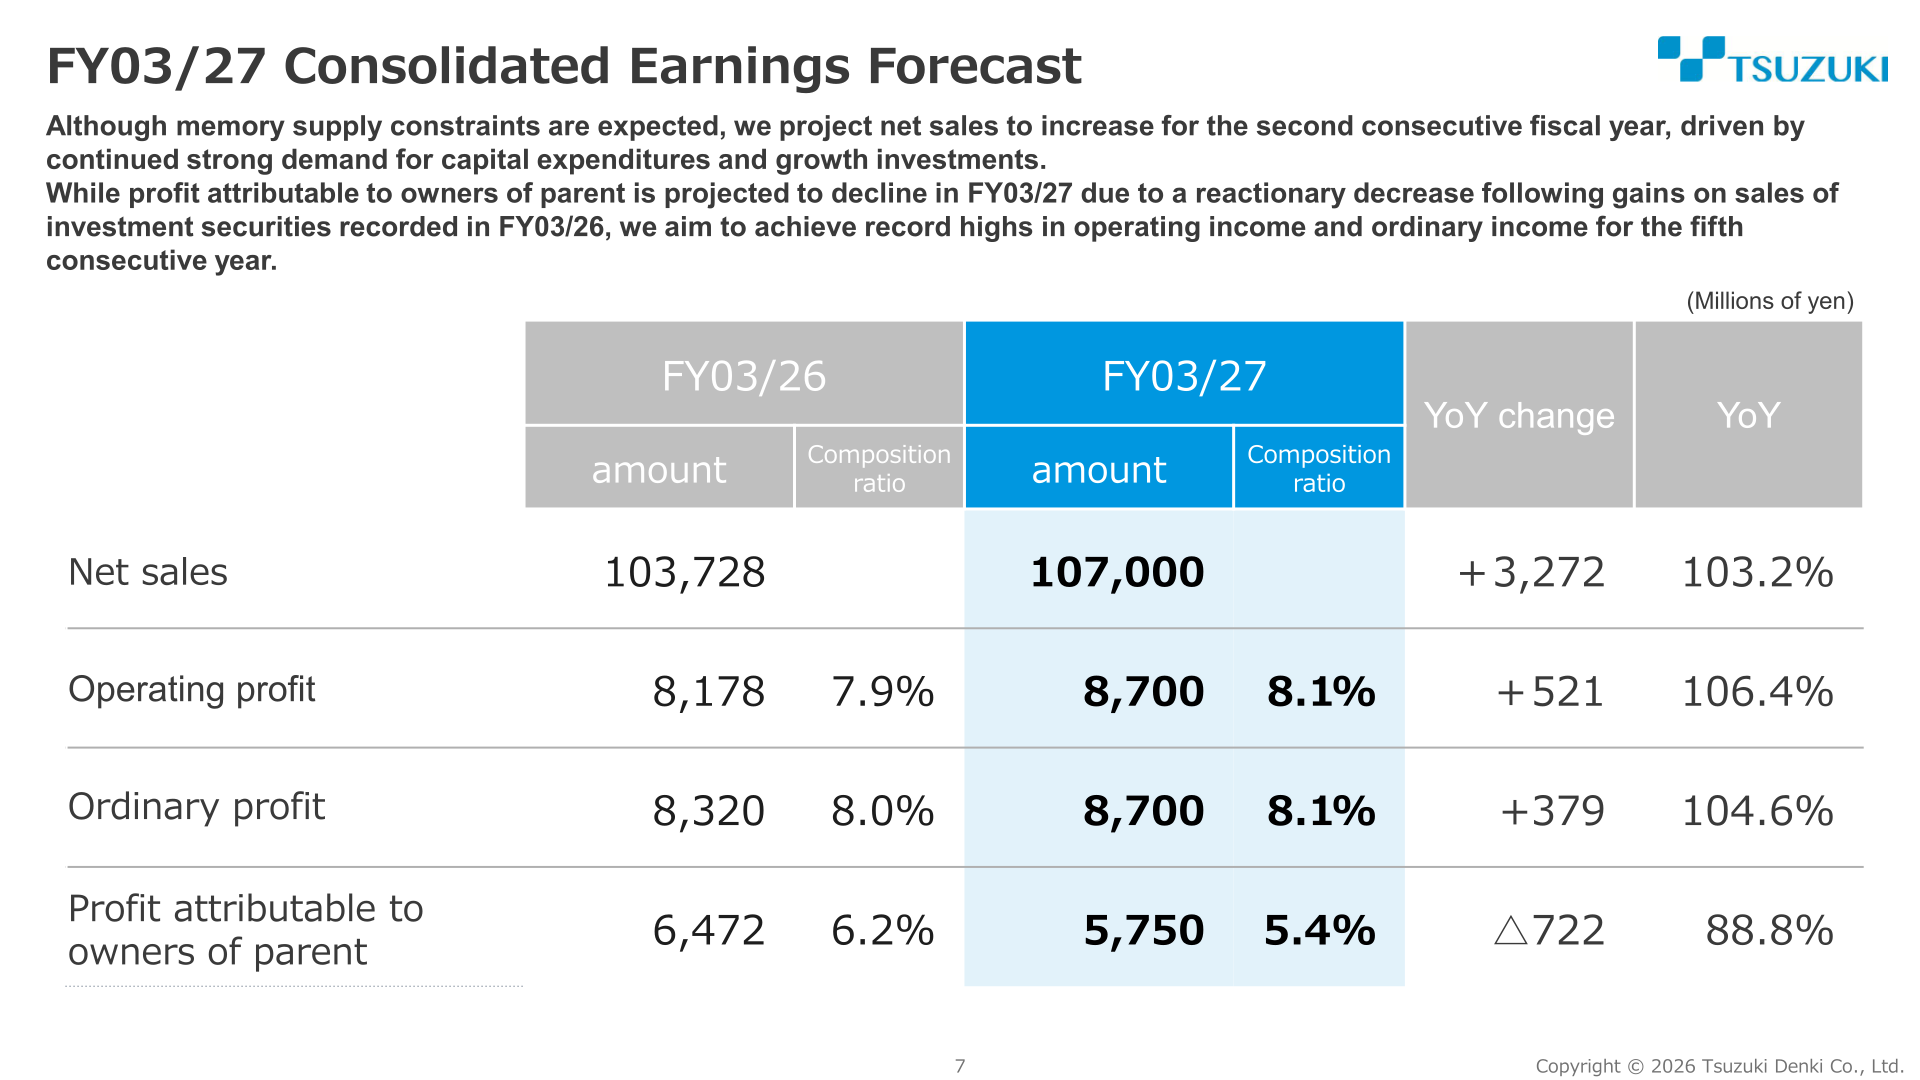
For the fiscal year ending March 31, 2027 (labeled FY03/27 in the Company’s materials), Tsuzuki Denki forecasts net sales of ¥107,000 million (103.2% of FY03/26), supported by continued strong demand for capital expenditures and growth investments despite expected memory supply constraints. Operating profit is forecast at ¥8,700 million (106.4% of FY03/26) and ordinary profit at ¥8,700 million (104.6% of FY03/26), both aiming for record highs for a fifth consecutive fiscal year. Profit attributable to owners of parent is forecast to decline to ¥5,750 million (88.8% of the previous year), reflecting a reactionary decrease following gains on sales of investment securities recorded in FY03/26.
| Item | FY03/26 (Actual) | FY03/27 (Forecast) | YoY |
|---|---|---|---|
| Net sales | 103,728 | 107,000 | 103.2% |
| Operating profit | 8,178 (7.9%) | 8,700 (8.1%) | 106.4% |
| Ordinary profit | 8,320 (8.0%) | 8,700 (8.1%) | 104.6% |
| Profit attributable to owners of parent | 6,472 (6.2%) | 5,750 (5.4%) | 88.8% |
Shareholder Returns
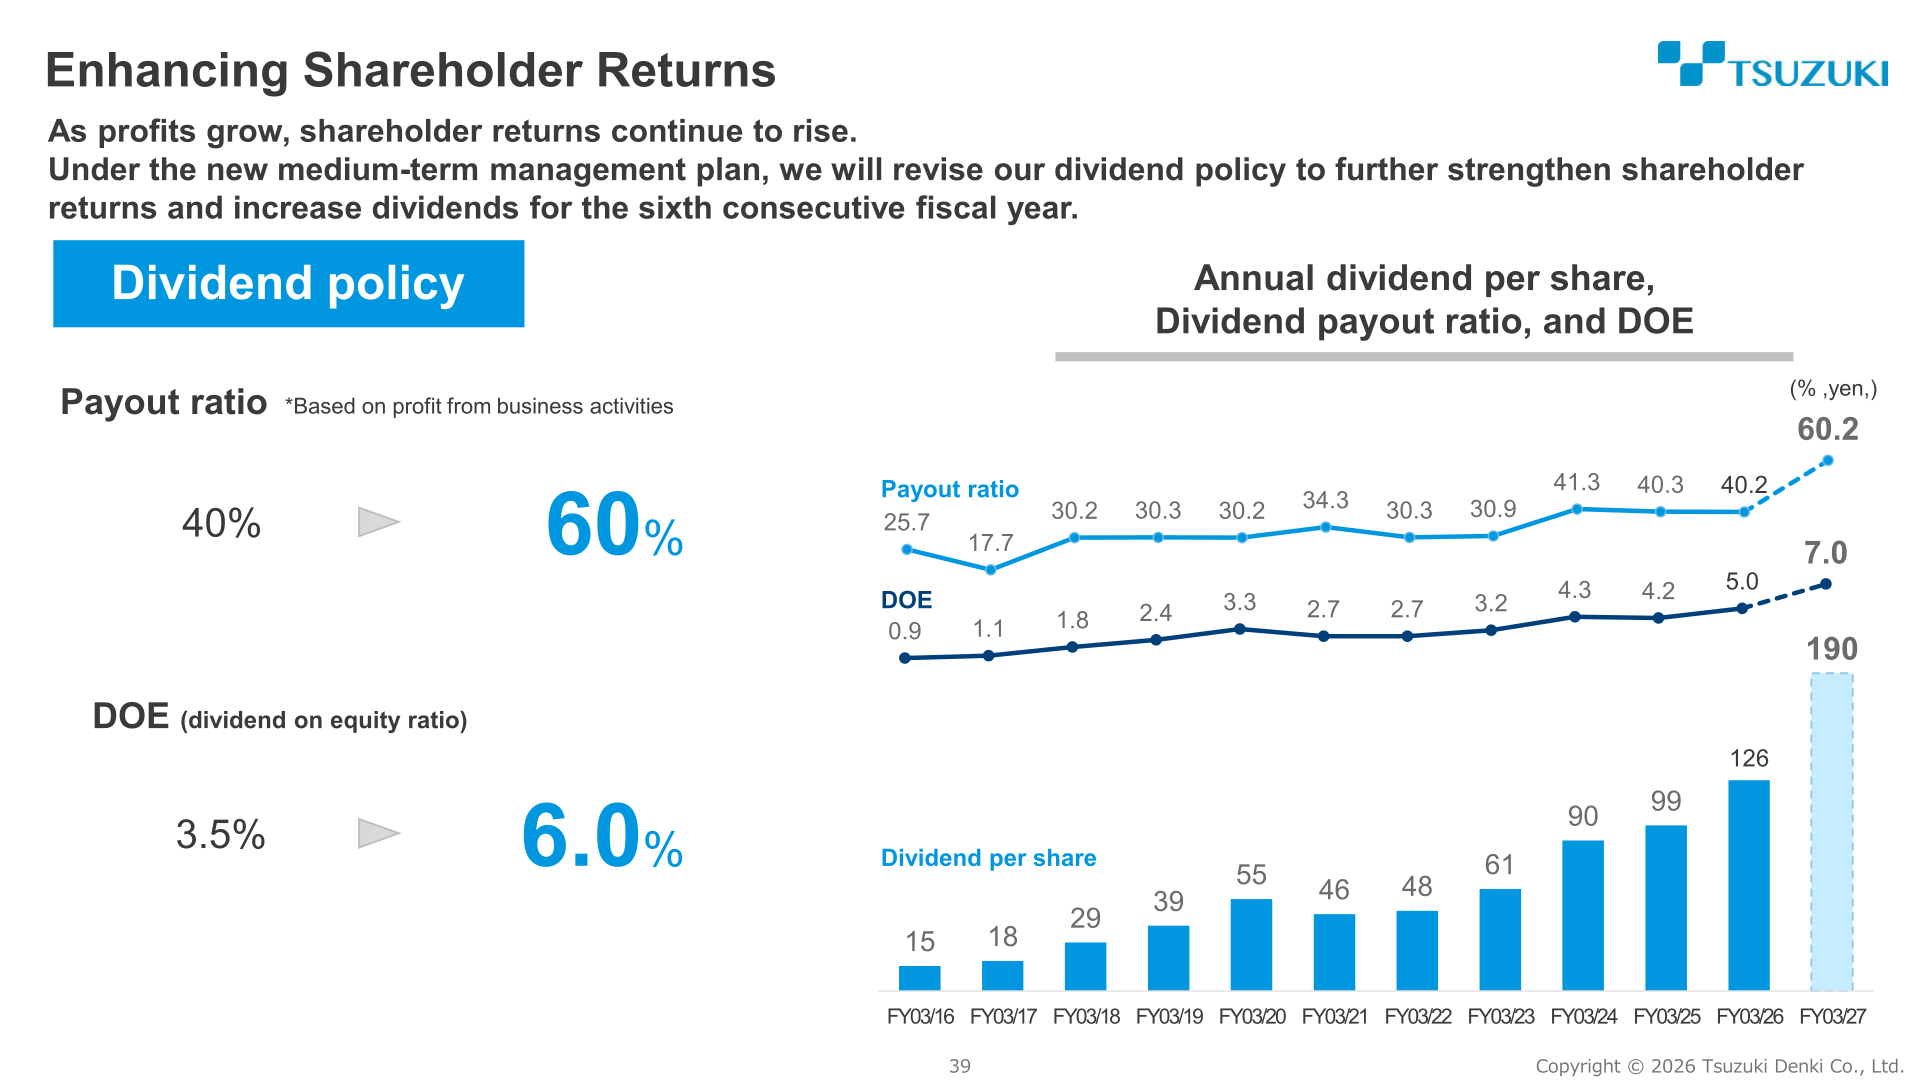
As profits have grown, Tsuzuki Denki’s shareholder returns have continued to rise, with the annual dividend per share reaching ¥126 in FY03/26 (payout ratio 40.2%, DOE 5.0%, based on profit from business activities), up from a target payout ratio of 40% and minimum DOE of 3.5% under the Company’s prior dividend policy. Under the new medium-term management plan, the Company has revised its dividend policy, raising the target payout ratio to 60% and the minimum DOE to 6.0%, and plans to increase dividends for the sixth consecutive fiscal year: the FY03/27 annual dividend is forecast at ¥190 per share, with a payout ratio of 60.2% and DOE of 7.0%.
| Item | FY03/26 (Actual) | FY03/27 (Forecast) |
|---|---|---|
| Annual dividend per share (yen) | 126 | 190 |
| Payout ratio* (%) | 40.2 | 60.2 |
| DOE (dividend on equity)* (%) | 5.0 | 7.0 |
*Based on profit from business activities, per the Company’s presentation materials.
Medium-Term Plan / Topics
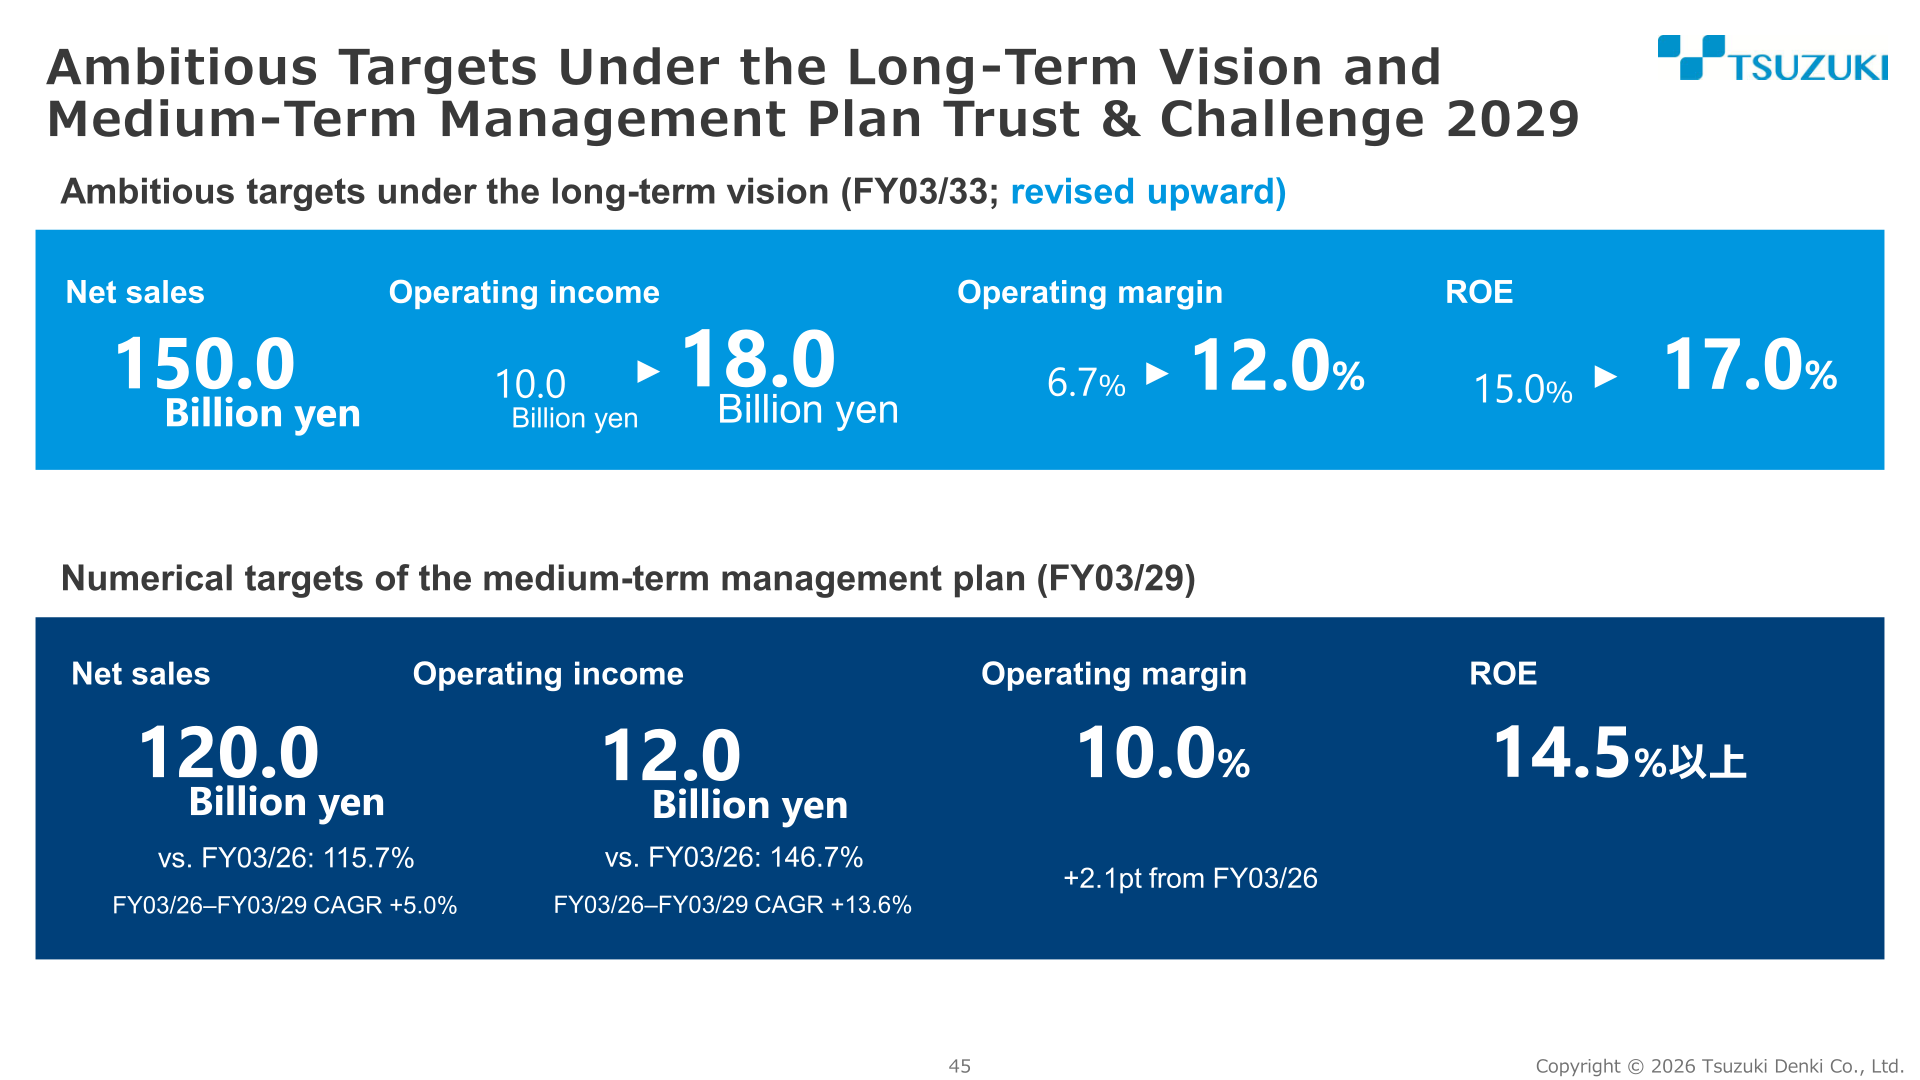
Tsuzuki Denki has launched a new three-year medium-term management plan, “Trust & Challenge 2029” (FY03/27–FY03/29), succeeding the previous plan “Transformation 2026,” under which the Company achieved all of its financial targets: net sales of ¥103.7 billion versus a target of ¥102.2 billion, and ROE of 14.0% versus a target of 10% or above. Under Trust & Challenge 2029, the Company aims to transform into a professional services company, enhance corporate value through a virtuous cycle of growth and shareholder returns, and transition to a human resource portfolio that accelerates value creation. For FY03/29, the plan targets net sales of ¥120.0 billion (a 3-year CAGR of +5.0%, and 115.7% versus FY03/26), operating profit of ¥12.0 billion (3-year CAGR of +13.6%, and 146.7% versus FY03/26), an operating margin of 10.0%, and ROE of 14.5% or above. The plan also allocates a growth investment scale of ¥7.0 billion and a strategic investment scale of ¥40.0 billion (including borrowings) toward inorganic growth.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















