
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
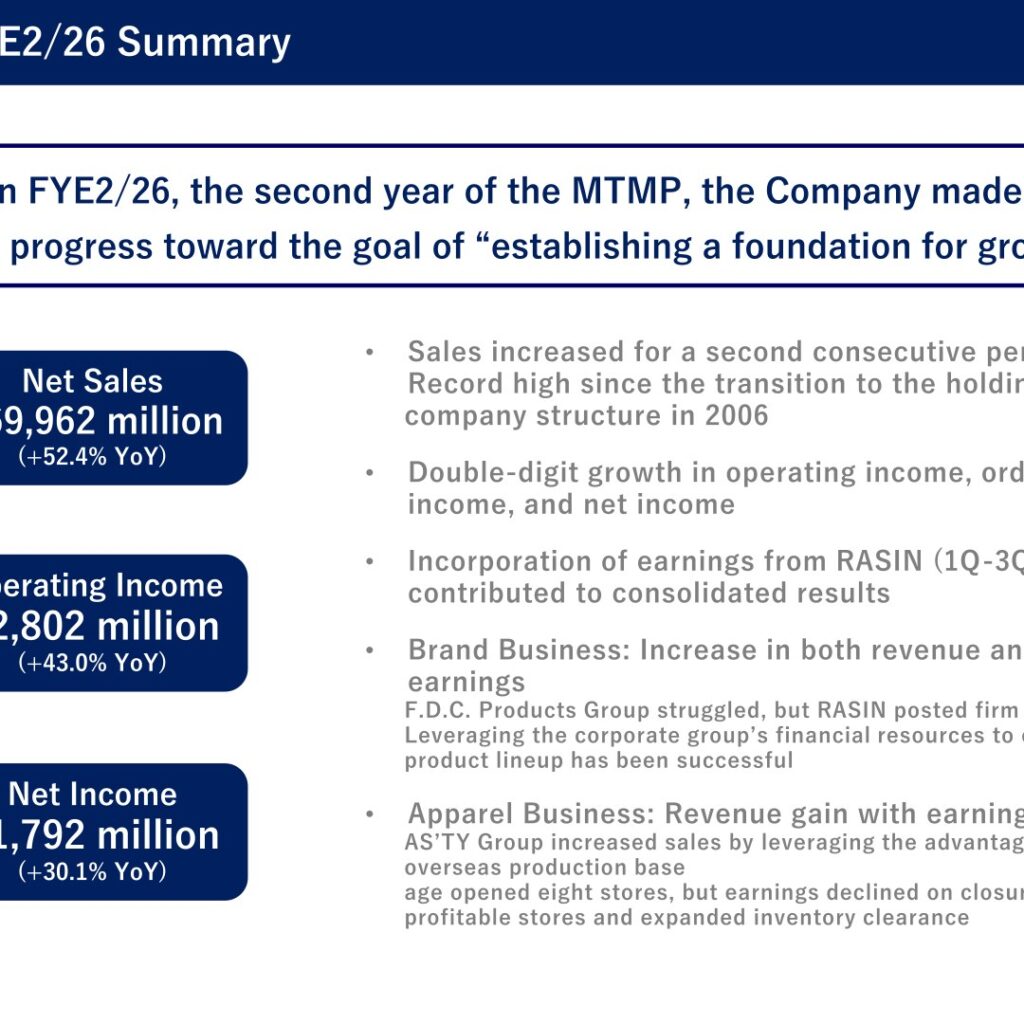
YONDOSHI HOLDINGS INC. (TSE Prime: 8008), the holding company for the “4°C” jewelry and apparel group, reported consolidated net sales of ¥69,962 million for the fiscal year ended February 28, 2026 (FYE2/26), up 52.4% year on year and a record high since the Company’s transition to a holding company structure in 2006. Operating income rose 43.0% to ¥2,802 million, ordinary income rose 34.6% to ¥3,164 million, and net income rose 30.1% to ¥1,792 million, with double-digit growth achieved at every profit level. Note: the presentation’s cover page labels this period “Results for the Fiscal 2025” (the fiscal year ended February 28, 2026), while its internal tables refer to the same period as “FYE2/26”; this article follows the source deck’s internal table notation (FYE2/26 = actual results just reported, FYE2/27 = the forecast for the year now underway).
Consolidated Results (Full-Year Actual)
Growth was driven by the incorporation of earnings from RASIN, the Group’s luxury-brand-watch reuse business, for the first three quarters (1Q–3Q) of the fiscal year, as well as an increase in both revenue and earnings at the Brand Business overall. Gross profit rose 16.6% to ¥23,249 million, though gross profit margin declined 10.2 points to 33.2% on the change in business mix following RASIN’s consolidation. SG&A expenses rose 13.7% to ¥20,446 million, while amortization of goodwill rose 83.4% to ¥1,256 million. All reported figures exceeded the Company’s own full-year forecasts (Net sales +6.0pt vs. plan, Net income +12.0pt vs. plan).
| Item | FYE2/25 (Actual) | FYE2/26 (Actual) | YoY (%) |
|---|---|---|---|
| Net sales | 45,902 | 69,962 | +52.4 |
| Gross profit | 19,942 | 23,249 | +16.6 |
| Gross profit margin (%) | 43.4 | 33.2 | -10.2 pt |
| SG&A expenses | 17,982 | 20,446 | +13.7 |
| Amortization of goodwill | 685 | 1,256 | +83.4 |
| Operating income | 1,960 | 2,802 | +43.0 |
| Ordinary income | 2,351 | 3,164 | +34.6 |
| Net income | 1,377 | 1,792 | +30.1 |
| Operating income before amortization of goodwill | 2,645 | 4,059 | +53.5 |
| Net income before amortization of goodwill | 2,062 | 3,048 | +47.8 |
On the balance sheet, total assets increased ¥2,341 million to ¥68,836 million and total net assets increased ¥2,131 million to ¥41,067 million as of February 28, 2026, with the equity ratio rising 1.1 points to 59.6%. Operating cash flow decreased ¥1,921 million year on year to ¥1,102 million due to an increase in inventory assets, while free cash flow increased ¥10,882 million year on year to ¥3,369 million, and investing cash flow swung to a positive ¥2,266 million (from ¥-10,536 million a year earlier).
Segment Results
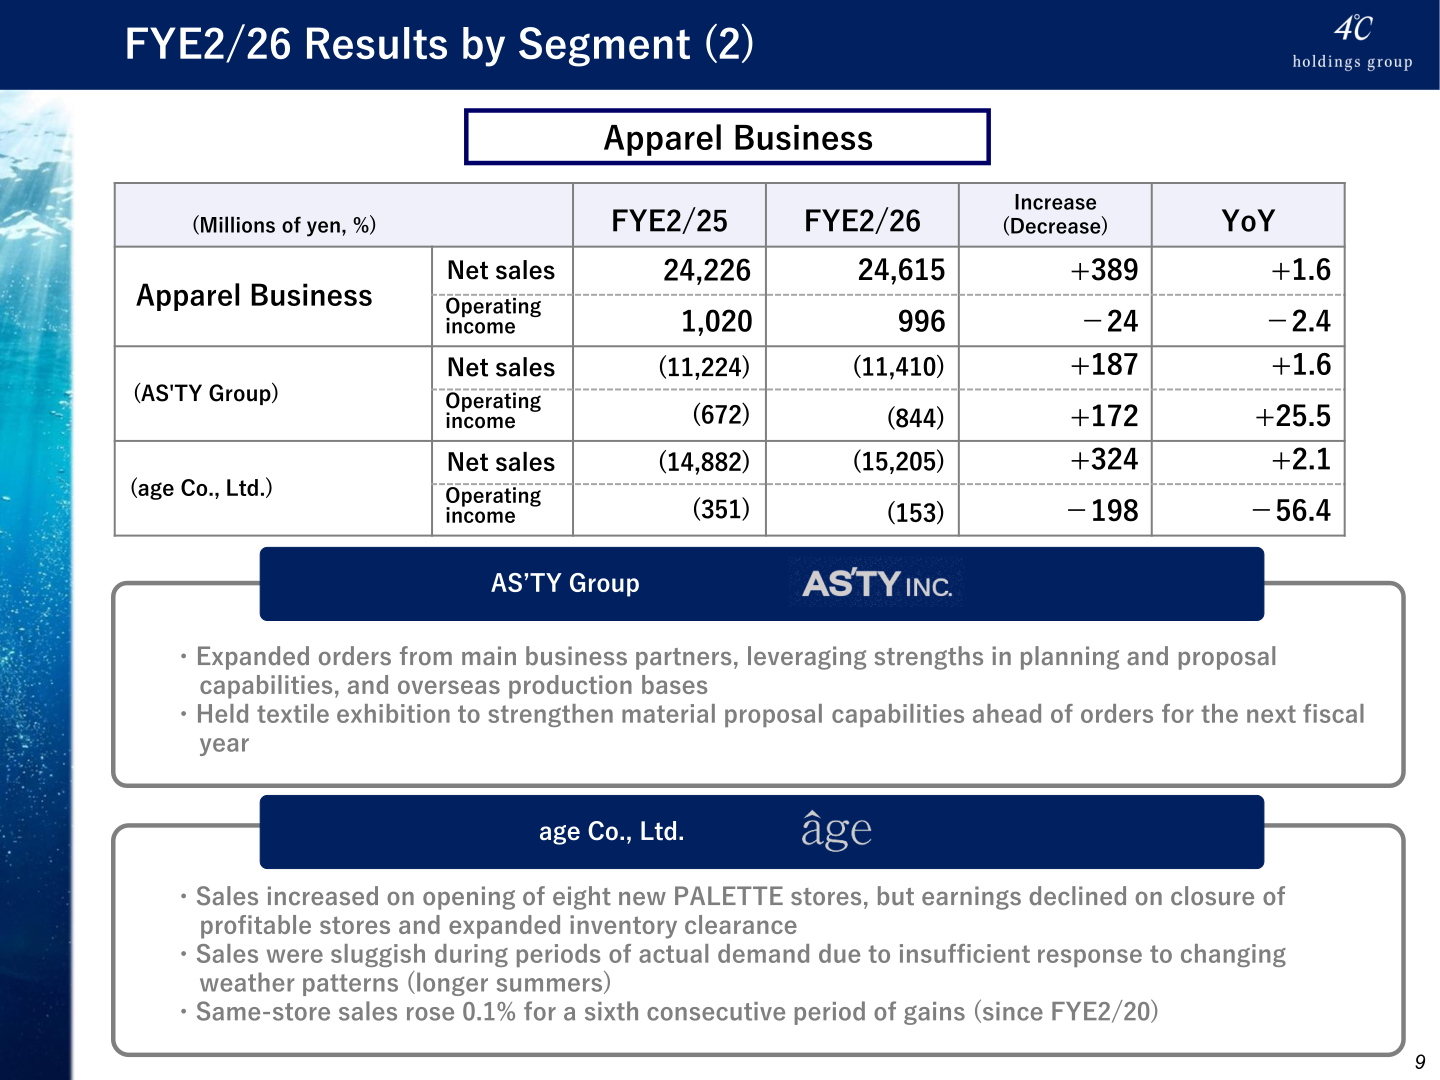
The Group operates four business portfolios under two reportable segments: the Brand Business (jewelry planning, production and sales, and the RASIN luxury watch reuse business) and the Apparel Business (AS’TY Group’s apparel OEM/ODM operations and age Co., Ltd.’s PALETTE fashion retail chain). In the Brand Business, net sales more than doubled (+109.2%) and operating income rose 89.5%, primarily on RASIN’s contribution, while the F.D.C. Products Group (the core 4°C jewelry business) saw sales and operating income decline as it worked through disruption from a new core IT system and customer reaction to April price revisions, before recovering in the second half. In the Apparel Business, net sales edged up 1.6% while operating income fell 2.4%, as growth at the AS’TY Group was offset by an earnings decline at age Co., Ltd. following the closure of profitable stores and expanded inventory clearance, despite the opening of eight new PALETTE stores. Segment figures are presented before internal offset.
| Segment / Company | Metric | FYE2/25 (Actual) | FYE2/26 (Actual) | YoY (%) |
|---|---|---|---|---|
| Brand Business | Net sales | 21,676 | 45,346 | +109.2 |
| Brand Business | Operating income | 1,509 | 2,859 | +89.5 |
| (F.D.C. Products Group) | Net sales | 15,276 | 14,187 | -7.1 |
| (F.D.C. Products Group) | Operating income | 1,070 | 433 | -59.4 |
| (RASIN) | Net sales | 6,400 | 31,159 | +386.9 |
| (RASIN) | Operating income | 453 | 2,481 | +447.7 |
| Apparel Business | Net sales | 24,226 | 24,615 | +1.6 |
| Apparel Business | Operating income | 1,020 | 996 | -2.4 |
| (AS’TY Group) | Net sales | 11,224 | 11,410 | +1.6 |
| (AS’TY Group) | Operating income | 672 | 844 | +25.5 |
| (age Co., Ltd.) | Net sales | 14,882 | 15,205 | +2.1 |
| (age Co., Ltd.) | Operating income | 351 | 153 | -56.4 |
FYE2/27 Forecast
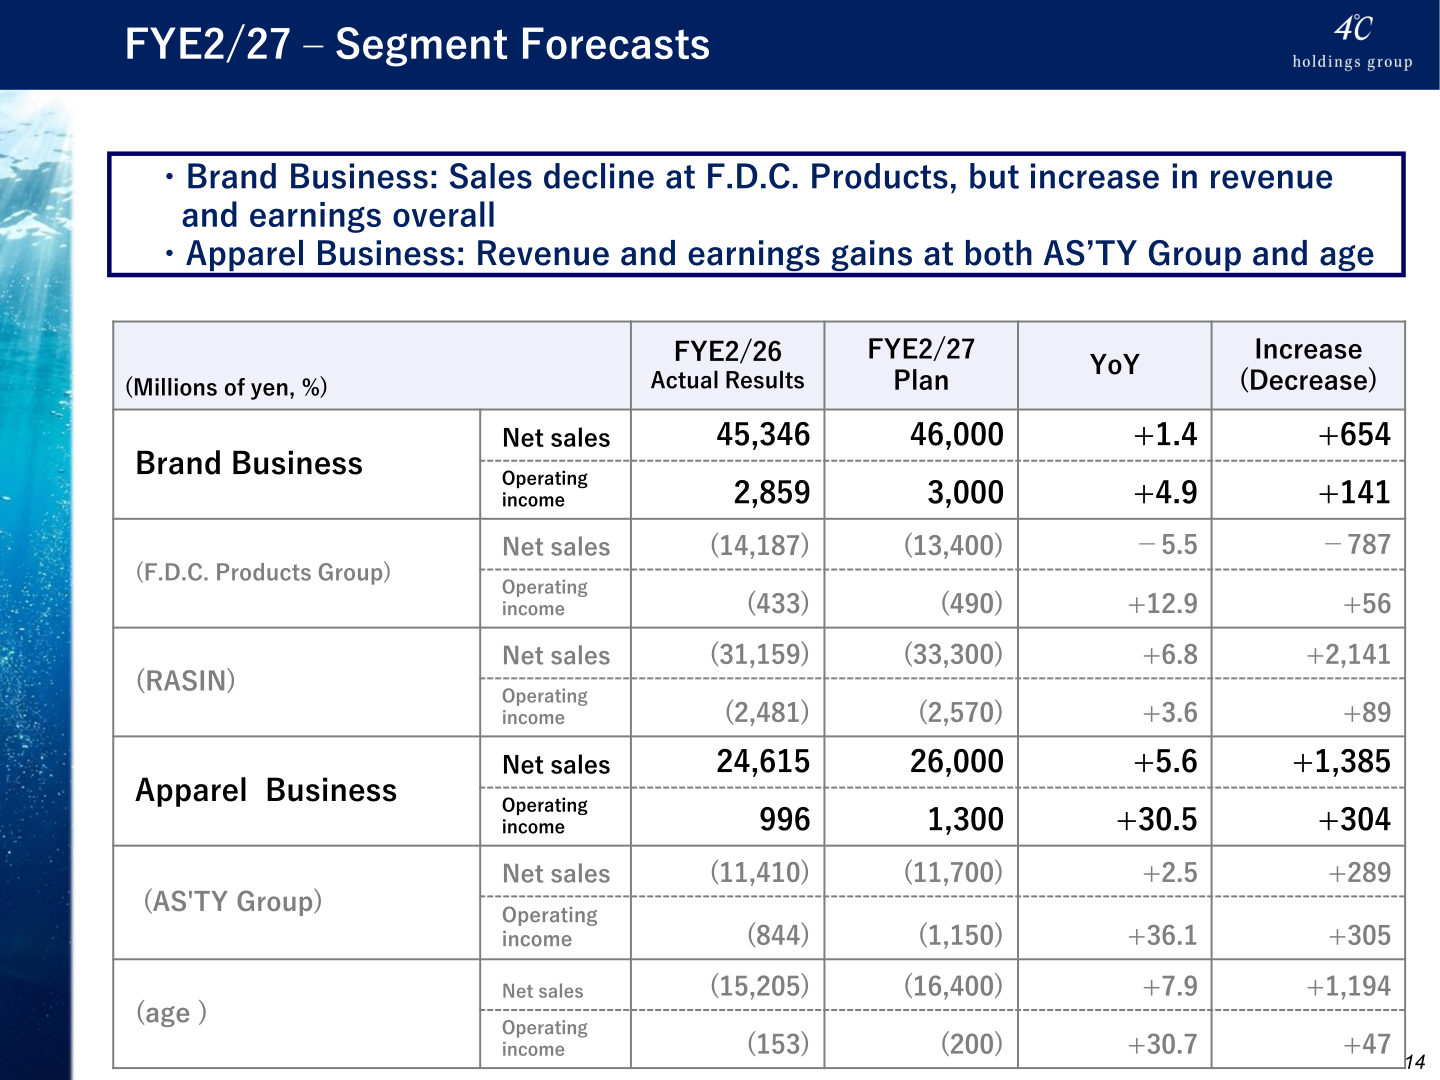
For FYE2/27, the Company forecasts continued growth in both revenue and earnings: net sales of ¥72,000 million (+2.9%), operating income of ¥3,600 million (+28.4%), ordinary income of ¥3,900 million (+23.2%) and net income of ¥2,300 million (+28.3%). Amortization of goodwill is expected to decrease ¥250 million to ¥1,006 million. By segment, the Brand Business plan calls for net sales of ¥46,000 million (+1.4%) and operating income of ¥3,000 million (+4.9%), with RASIN net sales planned at ¥33,300 million (+6.8%); the Apparel Business plan calls for net sales of ¥26,000 million (+5.6%) and operating income of ¥1,300 million (+30.5%), with both the AS’TY Group and age Co., Ltd. expected to post gains in revenue and earnings.
| Item | FYE2/26 (Actual) | FYE2/27 (Plan) | YoY (%) |
|---|---|---|---|
| Net sales | 69,962 | 72,000 | +2.9 |
| Gross profit | 23,249 | 23,600 | +1.5 |
| SG&A expenses | 20,446 | 20,000 | -2.2 |
| Amortization of goodwill | 1,256 | 1,006 | -19.9 |
| Operating income | 2,802 | 3,600 | +28.4 |
| Ordinary income | 3,164 | 3,900 | +23.2 |
| Net income | 1,792 | 2,300 | +28.3 |
| Operating income before amortization of goodwill | 4,059 | 4,606 | +13.5 |
| Net income before amortization of goodwill | 3,048 | 3,306 | +8.5 |
Shareholder Returns
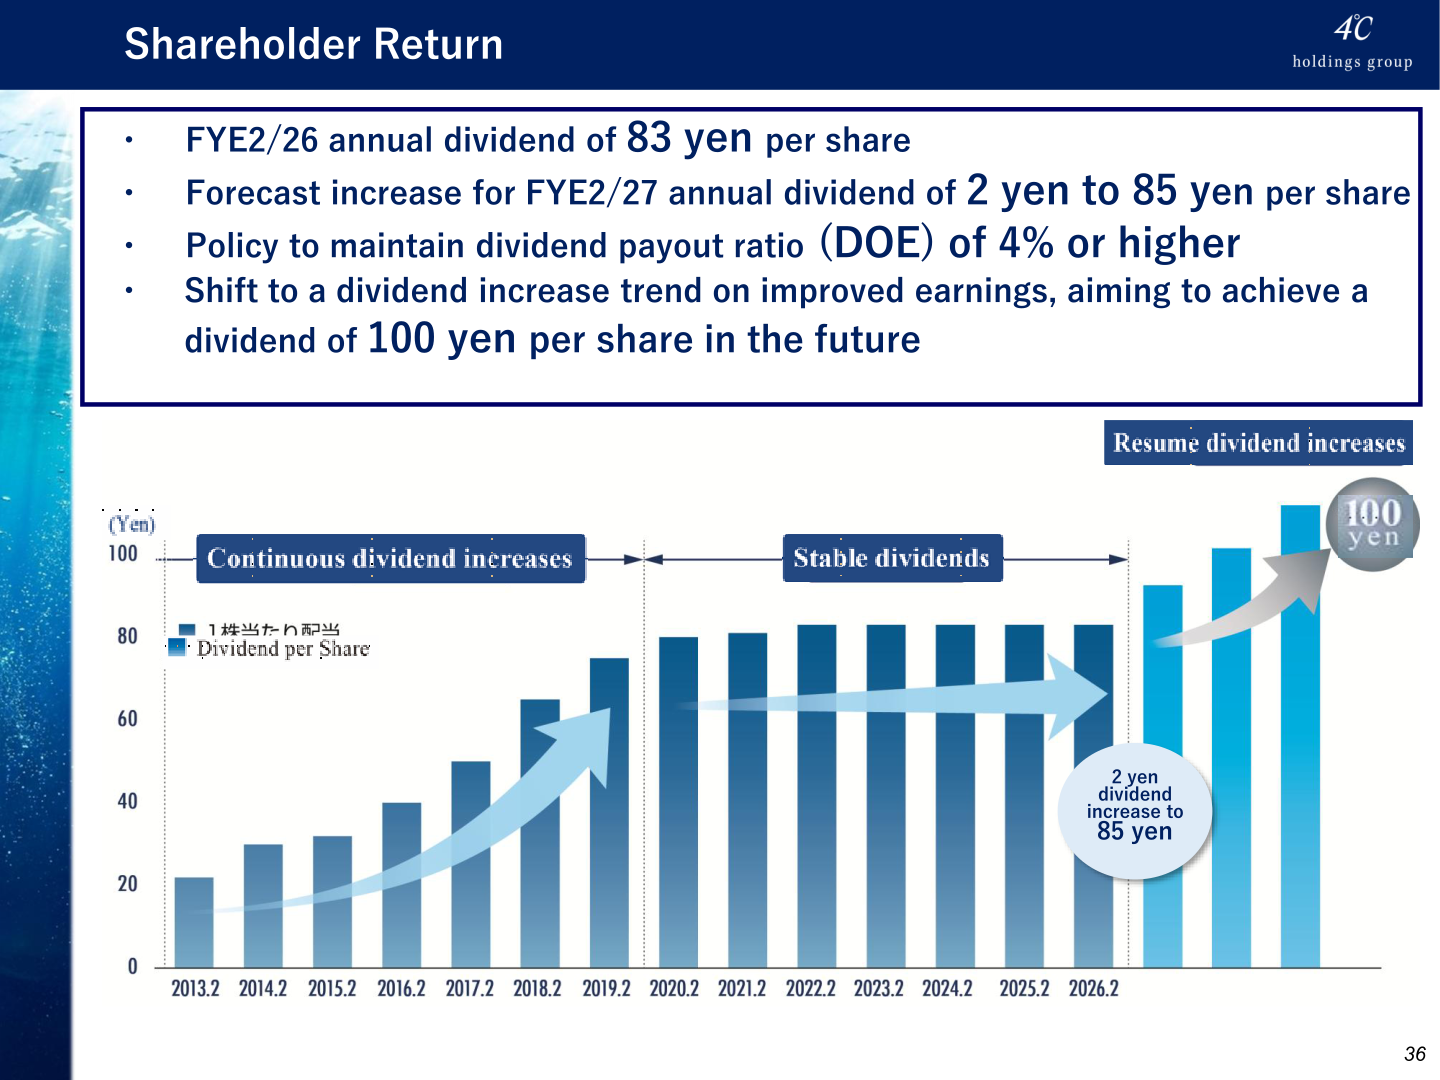
The annual dividend per share for FYE2/26 was ¥83, and the Company forecasts a further increase of ¥2 to ¥85 per share for FYE2/27. The Company’s policy is to maintain a dividend on equity (DOE) ratio of 4% or higher, and it states it is shifting to a dividend-increase trend on improved earnings, aiming to achieve a dividend of ¥100 per share in the future. As a proactive measure to improve shareholder returns, the Company also states it will continue to consider flexible share buybacks.
| Item | FYE2/26 | FYE2/27 (Forecast) |
|---|---|---|
| Annual dividend per share | ¥83 | ¥85 |
| Dividend policy | DOE 4.0% or higher | DOE 4.0% or higher |
Medium-Term Plan / Topics
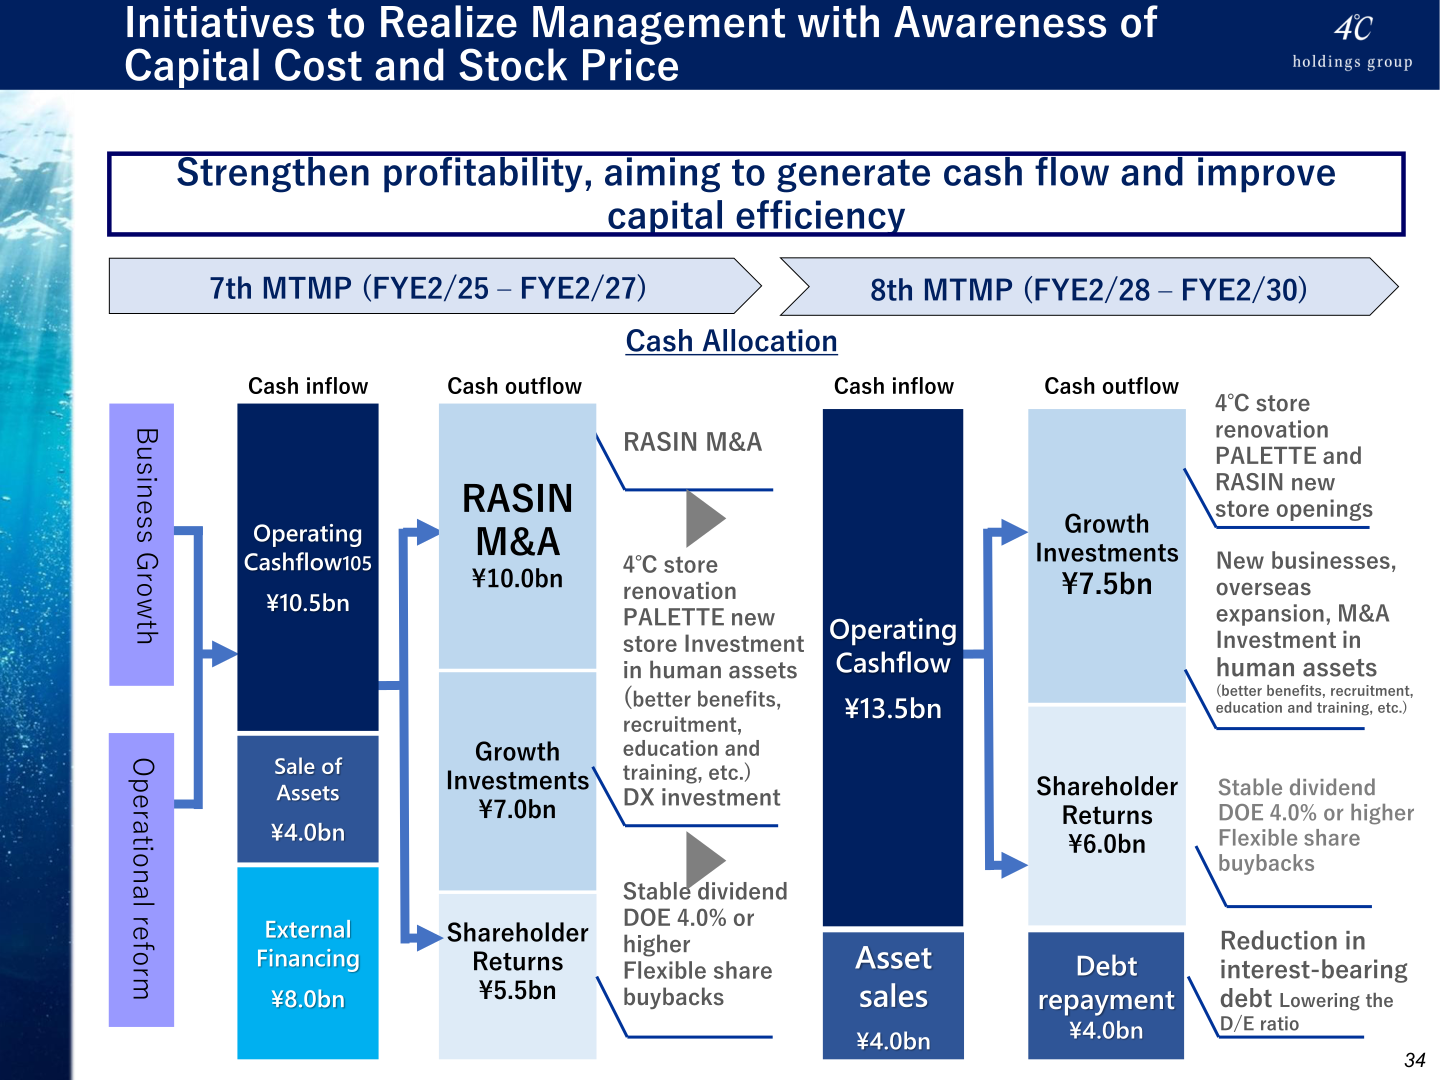
Under the 7th Medium-Term Management Plan (MTMP, FYE2/25–FYE2/27), operating income is expected to increase 71.7% over the three years of the plan, and the Company expects to achieve its 2030 Vision target of 8% or higher ROE before amortization of goodwill one year ahead of schedule, in FYE2/27 (revised upward from the plan announced in April 2025). ROE before amortization of goodwill rose from 5.3% in FYE2/25 to 7.6% in FYE2/26, with an 8.0% plan for FYE2/27, and the Company’s longer-term Vision 2030 target is 10% or higher. The Company financed the RASIN M&A in part through ¥10 billion in borrowings from financial institutions, which reduced its equity ratio from 76.2% at the end of FYE2/24 to 59.6% at the end of FYE2/26, while ROE before amortization of goodwill improved over the same period from 4.7% to 7.6% through the use of financial leverage. Under its cash allocation plan for the 7th MTMP, the Company allocated ¥10.5 billion in operating cash flow, ¥4.0 billion from asset sales and ¥8.0 billion in external financing toward ¥10.0 billion for the RASIN M&A, ¥7.0 billion in growth investments and ¥5.5 billion in shareholder returns; for the 8th MTMP (FYE2/28–FYE2/30) it plans ¥13.5 billion in operating cash flow and ¥4.0 billion from asset sales toward ¥7.5 billion in growth investments, ¥6.0 billion in shareholder returns and ¥4.0 billion in debt repayment to reduce interest-bearing debt.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















