
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: France Bed Holdings’ results presentation labels the fiscal year ended March 31, 2026 as “FY2026” (with the prior fiscal year ended March 31, 2025 labeled “FY2025”); this article follows japan-equity.com’s site convention of classifying the most recently completed fiscal year as FY2025 in the title and slug, while all tables, figures and fiscal-year labels in the body below retain the company’s own FY2025/FY2026 labeling exactly as presented in the source materials.
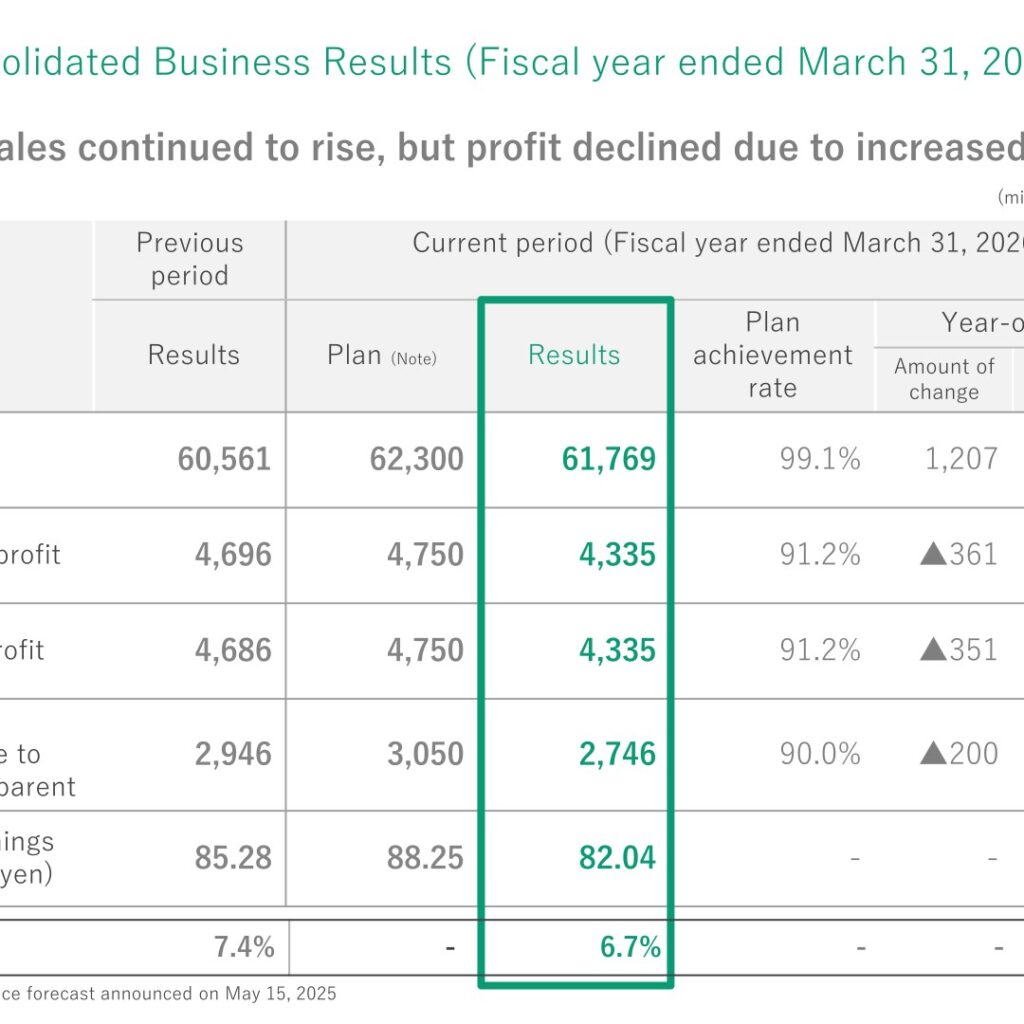
FRANCE BED HOLDINGS CO., LTD. reported consolidated net sales of ¥61,769 million for the fiscal year ended March 31, 2026, up 1.9% year on year, but operating profit fell 7.7% to ¥4,335 million, ordinary profit fell 7.4% to ¥4,335 million and profit attributable to owners of parent fell 6.8% to ¥2,746 million, as an increase in SG&A expenses (personnel and fare costs) of ¥1,119 million outweighed a ¥757 million increase in gross profit. Both reportable segments, Medical Services Business and Home Furnishings and Health Business, saw ordinary profit decline year on year. For the fiscal year ending March 31, 2027 the company plans a return to profit growth, forecasting net sales of ¥63,400 million (+2.6%) and operating profit of ¥4,600 million (+6.1%), and plans to raise its year-end dividend to ¥42 per share from ¥41.
Consolidated Results (Full-Year Actual)
Against a plan of ¥62,300 million announced on May 15, 2025, net sales achieved a 99.1% plan achievement rate at ¥61,769 million. Operating profit, ordinary profit and profit attributable to owners of parent each achieved a 91.2%, 91.2% and 90.0% plan achievement rate respectively, all below plan. Basic earnings per share were ¥82.04 against ¥85.28 in the previous period, and ROE was 6.7%, down 0.7pt year on year from 7.4%.
| Item | FY2025 Results | FY2026 Plan | FY2026 Results | Plan Achievement Rate | YoY Amount of Change | YoY Percentage Change |
|---|---|---|---|---|---|---|
| Net sales (millions of yen) | 60,561 | 62,300 | 61,769 | 99.1% | 1,207 | 1.9% |
| Operating profit (millions of yen) | 4,696 | 4,750 | 4,335 | 91.2% | ▲361 | ▲7.7% |
| Ordinary profit (millions of yen) | 4,686 | 4,750 | 4,335 | 91.2% | ▲351 | ▲7.4% |
| Profit attributable to owners of parent (millions of yen) | 2,946 | 3,050 | 2,746 | 90.0% | ▲200 | ▲6.8% |
| Basic earnings per share (yen) | 85.28 | 88.25 | 82.04 | – | – | – |
| ROE | 7.4% | – | 6.7% | – | – | ▲0.7pt |
On the balance sheet, total assets fell to ¥67,747 million as of March 31, 2026 from ¥70,888 million a year earlier, with cash and deposits/short-term securities down ¥2,367 million to ¥14,855 million and inventories down ¥1,231 million to ¥8,056 million. The equity-to-asset ratio improved 2.0pt to 59.2%. Cash flows from operating activities were ¥6,333 million (down ¥1,115 million year on year, reflecting ¥2,555 million of income taxes paid versus ¥900 million a year earlier), cash flows from investing activities were ▲¥4,323 million (of which purchase of non-current assets was ▲¥5,422 million), and cash flows from financing activities were ▲¥2,876 million, including ▲¥1,503 million for purchase of treasury shares and ▲¥1,359 million in dividends paid. Cash and cash equivalents at the end of the period were ¥12,355 million.
Segment Results
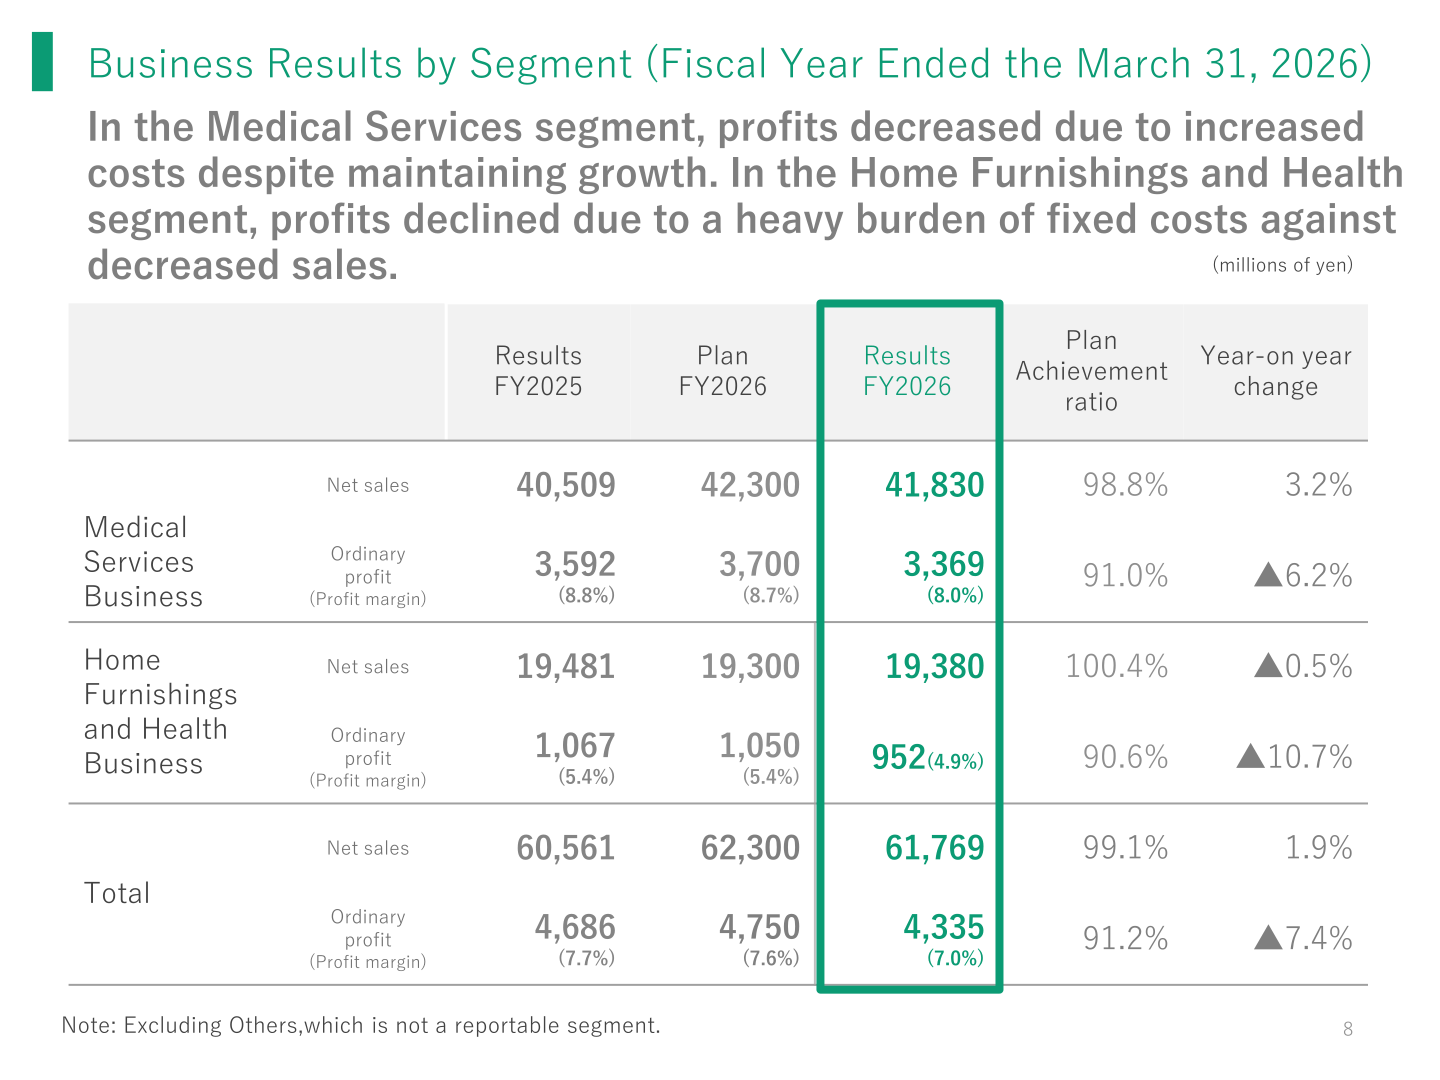
In the Medical Services Business, net sales grew 3.2% to ¥41,830 million (98.8% of the ¥42,300 million plan) but ordinary profit fell 6.2% to ¥3,369 million (8.0% margin, 91.0% of plan) due to increased costs despite maintaining growth. Within this segment, consolidated net sales rose across all major transaction categories except other sales transactions: transactions related to rental of assistive products rose 7.0% to ¥24,976 million, transactions for hospitals and facilities rose 1.4% to ¥5,501 million, and linen supply transactions rose 4.1% to ¥3,348 million, while other sales transactions fell 1.3% to ¥8,003 million. The presentation attributes the segment’s profit decline to an increase in fixed costs such as investment in personnel and logistics associated with growth, as well as a restriction on supply capacity in the linen supply business; excluding two months of HCSY (Home Care Service Yamato) results included in the prior-year period, ordinary profit was ¥3,519 million in the prior year versus ¥3,369 million in the current year, a decrease of ¥149 million (▲4.2%). In the Home Furnishings and Health Business, net sales fell 0.5% to ¥19,380 million (100.4% of the ¥19,300 million plan) and ordinary profit fell 10.7% to ¥952 million (4.9% margin, 90.6% of plan), as a decline and downsizing of furniture retailers and sluggish demand for durable consumer goods amid ongoing inflation led to a higher fixed cost burden against lower sales; within the segment, transactions for furniture retailers fell 2.5% to ¥17,135 million while transactions for hotels rose 18.5% to ¥2,245 million.
| Segment | Metric | FY2025 Results | FY2026 Plan | FY2026 Results | Plan Achievement Rate | YoY Change |
|---|---|---|---|---|---|---|
| Medical Services Business | Net sales (millions of yen) | 40,509 | 42,300 | 41,830 | 98.8% | 3.2% |
| Medical Services Business | Ordinary profit (profit margin) | 3,592 (8.8%) | 3,700 (8.7%) | 3,369 (8.0%) | 91.0% | ▲6.2% |
| Home Furnishings and Health Business | Net sales (millions of yen) | 19,481 | 19,300 | 19,380 | 100.4% | ▲0.5% |
| Home Furnishings and Health Business | Ordinary profit (profit margin) | 1,067 (5.4%) | 1,050 (5.4%) | 952 (4.9%) | 90.6% | ▲10.7% |
| Total | Net sales (millions of yen) | 60,561 | 62,300 | 61,769 | 99.1% | 1.9% |
| Total | Ordinary profit (profit margin) | 4,686 (7.7%) | 4,750 (7.6%) | 4,335 (7.0%) | 91.2% | ▲7.4% |
FY2027 Forecast
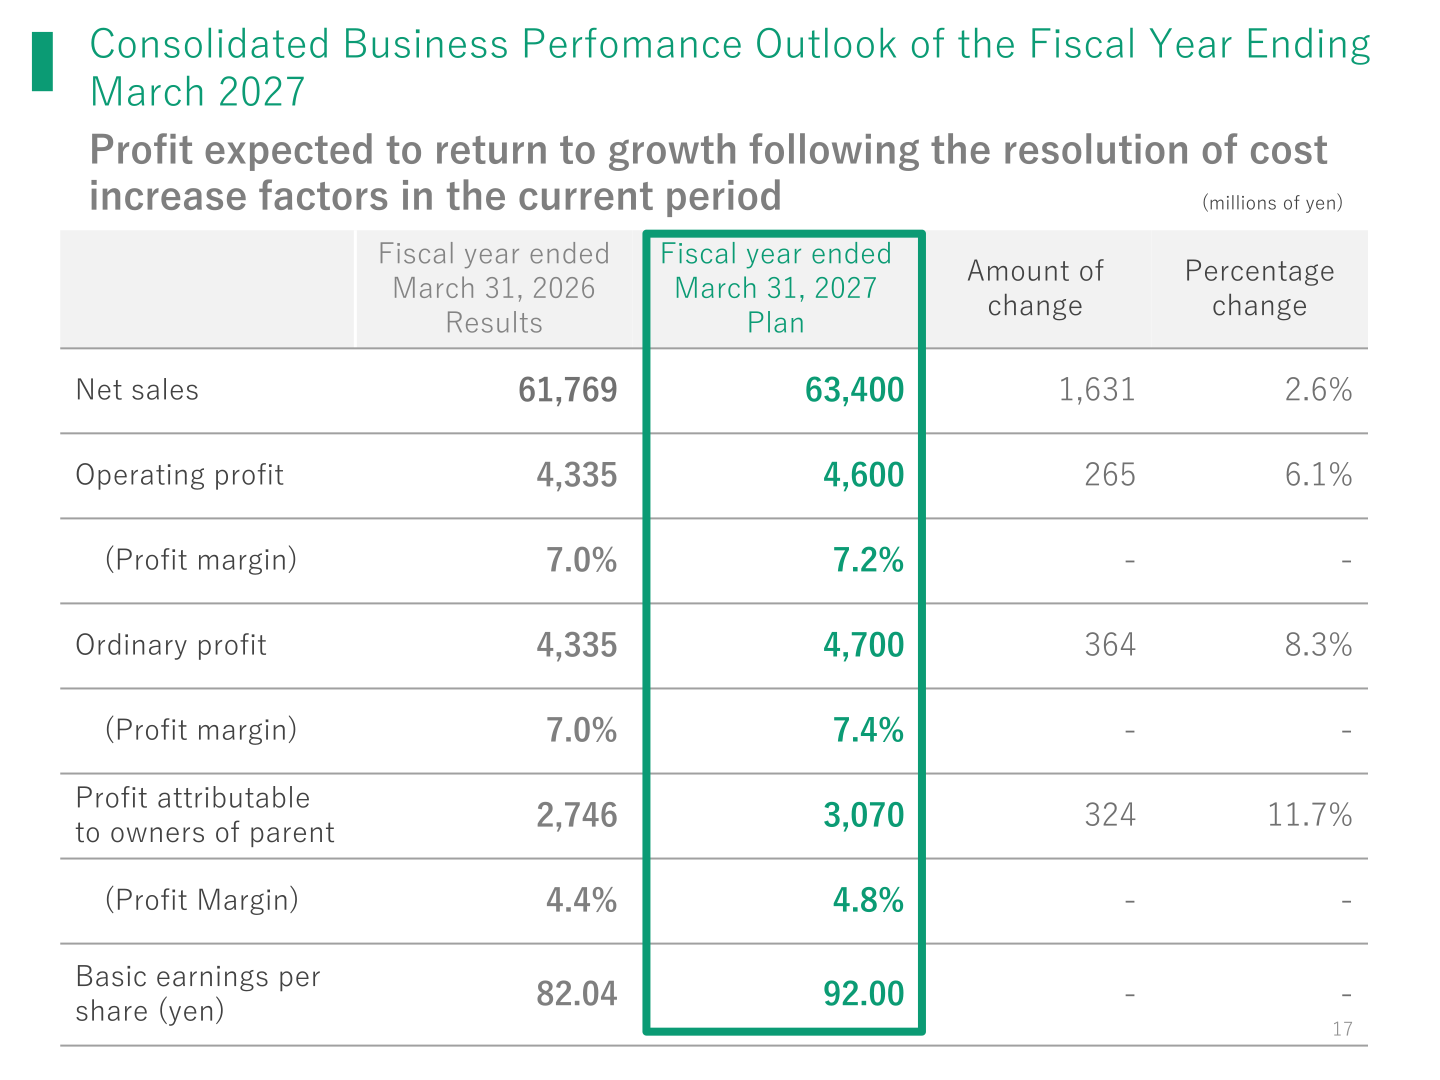
For the fiscal year ending March 31, 2027, the company forecasts consolidated net sales of ¥63,400 million (+2.6%), operating profit of ¥4,600 million (+6.1%, 7.2% margin), ordinary profit of ¥4,700 million (+8.3%, 7.4% margin), profit attributable to owners of parent of ¥3,070 million (+11.7%, 4.8% margin) and basic earnings per share of ¥92.00, with the presentation attributing the expected profit growth to the resolution of the cost-increase factors seen in the current period. By segment, the Medical Services Business is planned to post net sales of ¥43,700 million (+4.4%) and ordinary profit of ¥3,700 million (+9.8%, 8.4% margin), targeted through strengthening the revenue base via rental expansion in urban areas and customer acquisition, improving cost efficiency through enhanced service center functions and business process reforms, and enhancing productivity through digitization of contract documents. The Home Furnishings and Health Business is planned to post net sales of ¥19,400 million (+0.1%) and ordinary profit of ¥1,000 million (+5.0%, 5.1% margin), targeted through reducing manufacturing and logistics costs via structural reforms including factory reorganization, tighter control of inventory losses, and enhanced proposals of high-value-added products for the hotel segment. The “Other” category is planned at net sales of ¥300 million, down 46.1% from ¥557 million. Capital investment is planned at ¥4,850 million (of which ¥3,800 million for rental assets and ¥315 million for service centers) against ¥4,995 million in the current period, with depreciation of ¥5,015 million planned versus ¥5,033 million in the current period, as the company controls new rental investments while improving profitability through higher asset turnover and enhanced service center functions.
| Item | FY2026 Results | FY2027 Plan | Amount of Change | Percentage Change |
|---|---|---|---|---|
| Net sales (millions of yen) | 61,769 | 63,400 | 1,631 | 2.6% |
| Operating profit (millions of yen; profit margin) | 4,335 (7.0%) | 4,600 (7.2%) | 265 | 6.1% |
| Ordinary profit (millions of yen; profit margin) | 4,335 (7.0%) | 4,700 (7.4%) | 364 | 8.3% |
| Profit attributable to owners of parent (millions of yen; profit margin) | 2,746 (4.4%) | 3,070 (4.8%) | 324 | 11.7% |
| Basic earnings per share (yen) | 82.04 | 92.00 | – | – |
Topics and Key Future Initiatives
On February 6, 2026 the company announced a revision of its full-year earnings forecasts for the fiscal year ended March 2026 and a withdrawal of the performance targets set forth in its medium-term management plan for the fiscal year ending March 2027. On March 27, 2026 it announced its consolidated earnings forecast and dividend forecast for the fiscal year ending March 2027, including the year-end dividend forecast of ¥42, up ¥1 year on year. Under its basic policy of stabilizing and growing its profit structure through a shift to a rental-based business, the group targets raising the ratio of rental sales (including sales of linen supply) to consolidated net sales to 50% by the fiscal year ending March 2029, a level the presentation notes was temporarily achieved in April 2026. Key initiatives in the Medical Services Business include strengthening the nursing care robotics and ICT segment (including a bed with a monitoring sensor, “M-Sleep Bio”), expanding rental services such as furniture, home appliances and hearing aids, and improving operational efficiency through digitization of contracts and invoicing, automation of business processes, and use of generative AI. Key initiatives in the Home Furnishings and Health Business include reducing manufacturing and logistics costs through structural reforms such as consolidating woodworking plants from two to one and closing unprofitable showrooms, changing from order production to planned production, and strengthening hotel rental and e-commerce channels, including expansion of the rental products lineup for hotels and expansion of down quilt sales.
Shareholder Returns
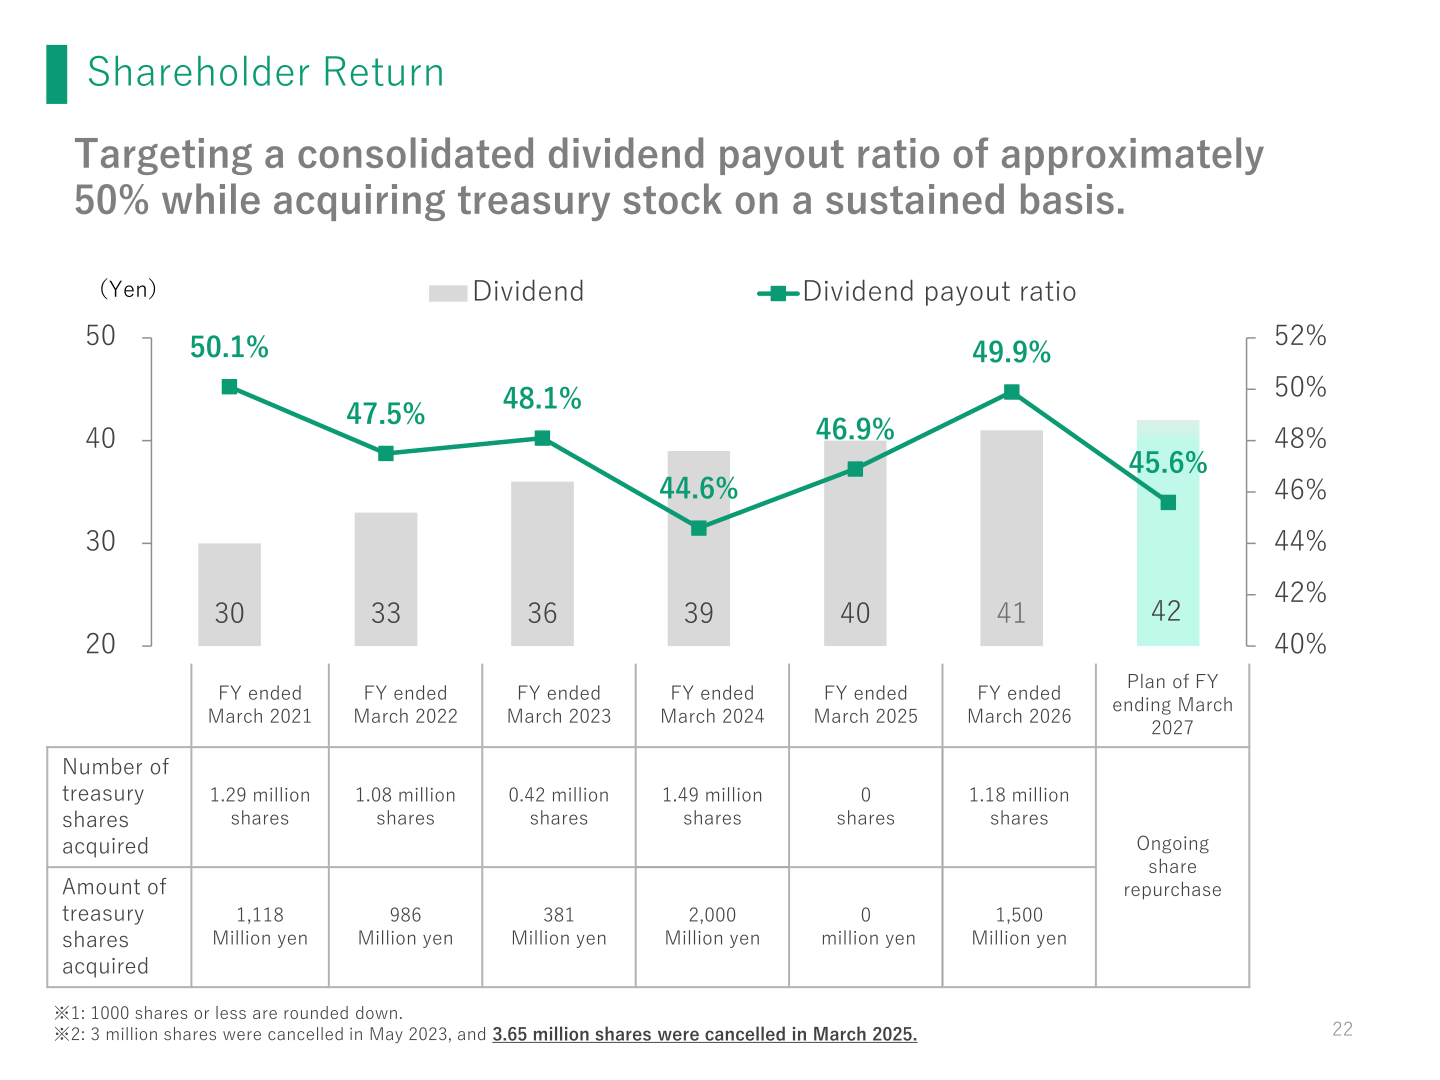
The company targets a consolidated dividend payout ratio of approximately 50% while acquiring treasury stock on a sustained basis. The dividend per share has risen each year since the fiscal year ended March 2021 (¥30), reaching ¥41 for the fiscal year ended March 2026 (49.9% payout ratio), and the company plans a dividend of ¥42 for the fiscal year ending March 2027 (45.6% payout ratio). Treasury share acquisitions were ¥1,500 million (1.18 million shares) in the fiscal year ended March 2026, following ¥0 in the prior fiscal year, and the company plans an ongoing share repurchase for the fiscal year ending March 2027. The notes to the chart state that 3 million shares were cancelled in May 2023 and 3.65 million shares were cancelled in March 2025.
| Fiscal Year | Dividend per Share (yen) | Dividend Payout Ratio | Treasury Shares Acquired (millions of yen) |
|---|---|---|---|
| FY ended March 2021 | 30 | 50.1% | 1,118 |
| FY ended March 2022 | 33 | 47.5% | 986 |
| FY ended March 2023 | 36 | 48.1% | 381 |
| FY ended March 2024 | 39 | 44.6% | 2,000 |
| FY ended March 2025 | 40 | 46.9% | 0 |
| FY ended March 2026 | 41 | 49.9% | 1,500 |
| Plan of FY ending March 2027 | 42 | 45.6% | Ongoing share repurchase |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















