
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
MANI, INC. (7730) reported higher revenue but lower profit for the fiscal year ended August 31, 2025 (FY2025), as a voluntary recall of “MANI DIA-BURS” dental rotary instruments in China weighed on results. Consolidated net sales rose 5.1% year on year to ¥29,968 million, while operating income declined 2.4% to ¥8,193 million and net income fell 26.1% to ¥4,643 million. The Surgical and Eyeless Needle segments continued to grow, while the Dental segment’s sales and profit declined mainly due to the China recall and an impairment of non-current assets at the company’s German subsidiary, MANI MEDICAL GERMANY (MMG). This presentation is labeled by the company as a “Revised version” dated October 8, 2025.
Consolidated Results (Full-Year Actual)
Net sales increased 5.1% year on year to ¥29,968 million against a FY2025 revised forecast of ¥29,600 million (progress rate 101.2%). Operating income decreased 2.4% to ¥8,193 million (103.7% of the revised forecast), ordinary income decreased 2.3% to ¥8,271 million (106.0% of the revised forecast), and net income decreased 26.1% to ¥4,643 million (85.2% of the revised forecast). The company attributed the profit decline mainly to the temporary impact of the voluntary recall of dia-burs in China, together with an impairment of non-current assets at Germany’s MMG (¥1,190 million recorded in extraordinary loss) and inventory disposal of long-stagnant products (¥98 million recorded in cost of sales).
| Item | FY2024 Results (A) | FY2025 Results (B) | Change (B-A) | Change % | FY2025 Revised Forecast (D) | Progress Rate (B/D) |
|---|---|---|---|---|---|---|
| Net sales | 28,513 | 29,968 | +1,454 | +5.1% | 29,600 | 101.2% |
| Cost of sales [%] | 10,616 (37.2%) | 10,650 (35.5%) | +33 | +0.3% | 10,800 (36.5%) | 98.6% |
| SG&A expenses [%] | 9,505 (33.3%) | 11,124 (37.1%) | +1,619 | +17.0% | 10,900 (36.8%) | 102.1% |
| Operating income [%] | 8,392 (29.4%) | 8,193 (27.3%) | (198) | (2.4%) | 7,900 (26.7%) | 103.7% |
| Ordinary income | 8,464 | 8,271 | (192) | (2.3%) | 7,800 | 106.0% |
| Net income | 6,286 | 4,643 | (1,643) | (26.1%) | 5,450 | 85.2% |
Segment Results
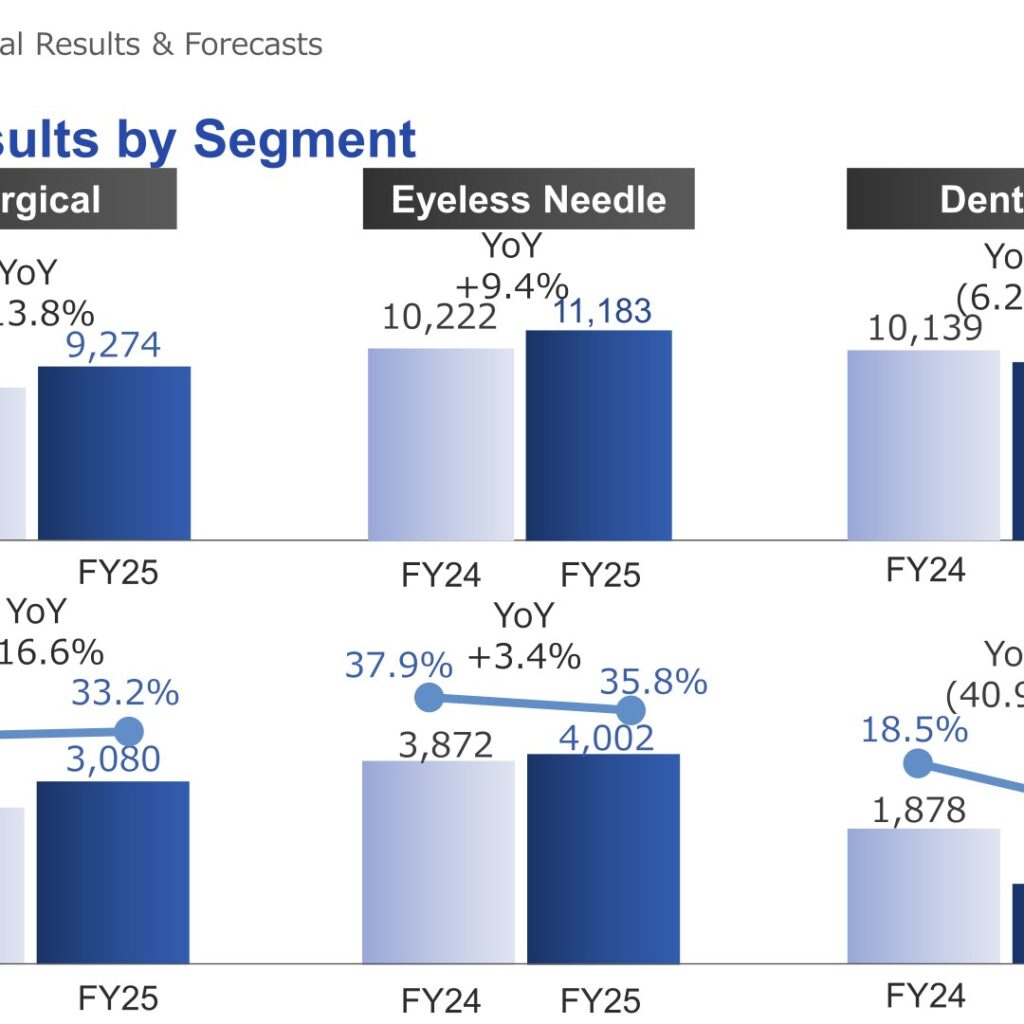
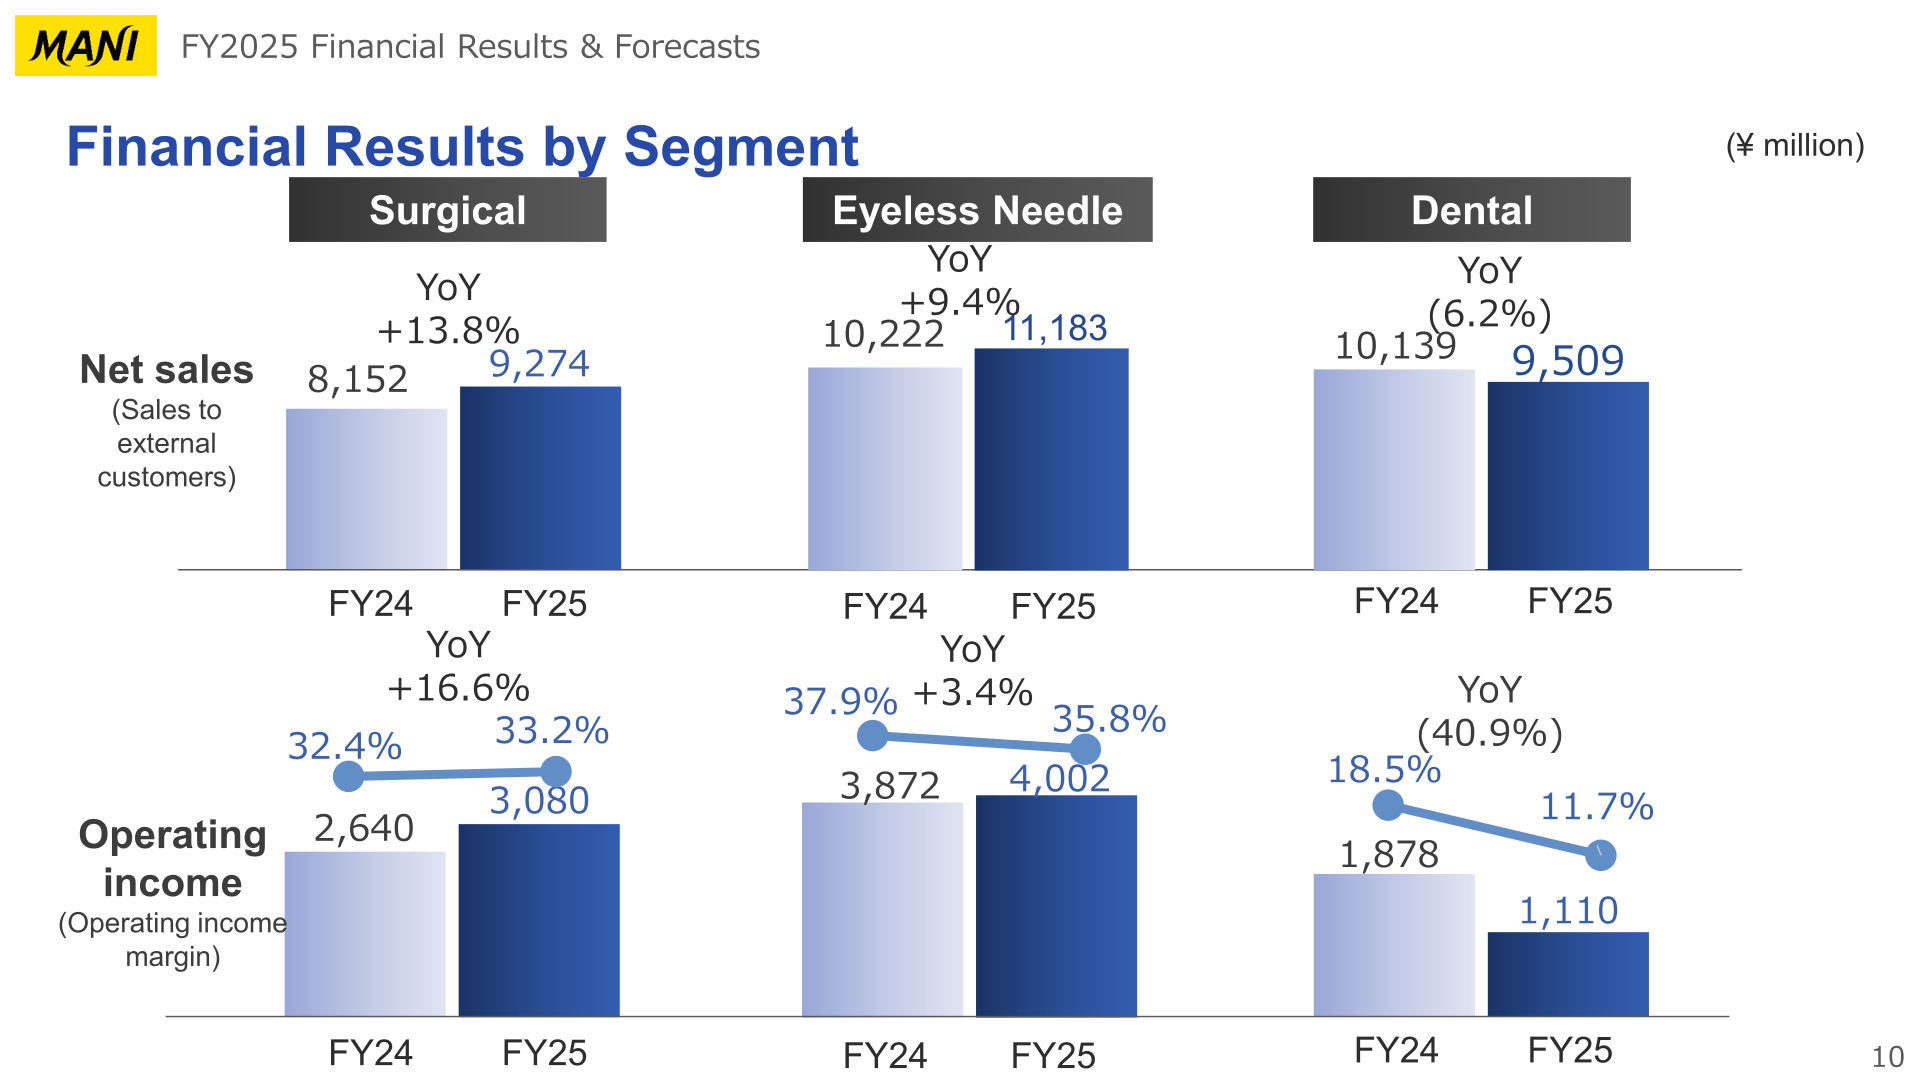
Net sales in the Surgical Products segment grew 13.8% year on year to ¥9,274 million, with operating income up 16.6% to ¥3,080 million (operating income margin 33.2%), driven by sales growth in ophthalmic knives in Europe, Asia (mainly China), Japan and North America. In the Eyeless Needle Products segment, net sales grew 9.4% to ¥11,183 million and operating income rose 3.4% to ¥4,002 million (margin 35.8%), led by growth in China supported by strategic partnerships and GPO orders. In the Dental Products segment, net sales fell 6.2% to ¥9,509 million and operating income fell 40.9% to ¥1,110 million (margin 11.7%), reflecting the significant impact of the voluntary recall of dia-burs in China, while other regions such as Russia and Japan grew more than 20% year on year. MMG posted FY2025 sales of ¥1.9 billion and a loss of ¥320 million and is undergoing structural reforms for profitability.
| Segment | Net Sales FY2024 | Net Sales FY2025 | Net Sales Change | Operating Income FY2024 | Operating Income FY2025 | Operating Income Margin FY2025 |
|---|---|---|---|---|---|---|
| Surgical Products | 8,152 | 9,274 | +1,122 | 2,640 | 3,080 | 33.2% |
| Eyeless Needle Products | 10,222 | 11,183 | +961 | 3,872 | 4,002 | 35.8% |
| Dental Products | 10,139 | 9,509 | (629) | 1,878 | 1,110 | 11.7% |
FY2026 Forecast
For FY2026, the company forecasts consolidated net sales of ¥32,800 million (+9.4% year on year), operating income of ¥9,200 million (+12.3%), ordinary income of ¥8,950 million (+8.2%) and net income of ¥6,450 million (+38.9%), reflecting an expected recovery from the China dia-burs recall, with full-lineup sales anticipated to resume from FY2026 2Q (December 2025-February 2026). FY2026 is positioned as the first year of the company’s new medium-term plan, which targets FY29 consolidated net sales of ¥45 billion and an operating income margin of 32%, supported by growth investments (including U.S. operations and new product development) and strengthening of the management foundation (regulatory affairs, SCM, BPR/DX).
| Item | FY2025 Results | FY2026 Forecast | Change (Amount) | Change % |
|---|---|---|---|---|
| Net sales | 29,968 | 32,800 | +2,832 | +9.4% |
| Cost of sales [%] | 10,650 [35.5%] | 11,400 [34.8%] | +750 | +7.0% [(0.7%)] |
| SG&A expenses [%] | 11,124 [37.1%] | 12,200 [37.2%] | +1,076 | +9.7% [+0.1%] |
| Operating income [%] | 8,193 [27.3%] | 9,200 [28.0%] | +1,007 | +12.3% [+0.7%] |
| Ordinary income | 8,271 | 8,950 | +679 | +8.2% |
| Net income | 4,643 | 6,450 | +1,807 | +38.9% |
Shareholder Returns
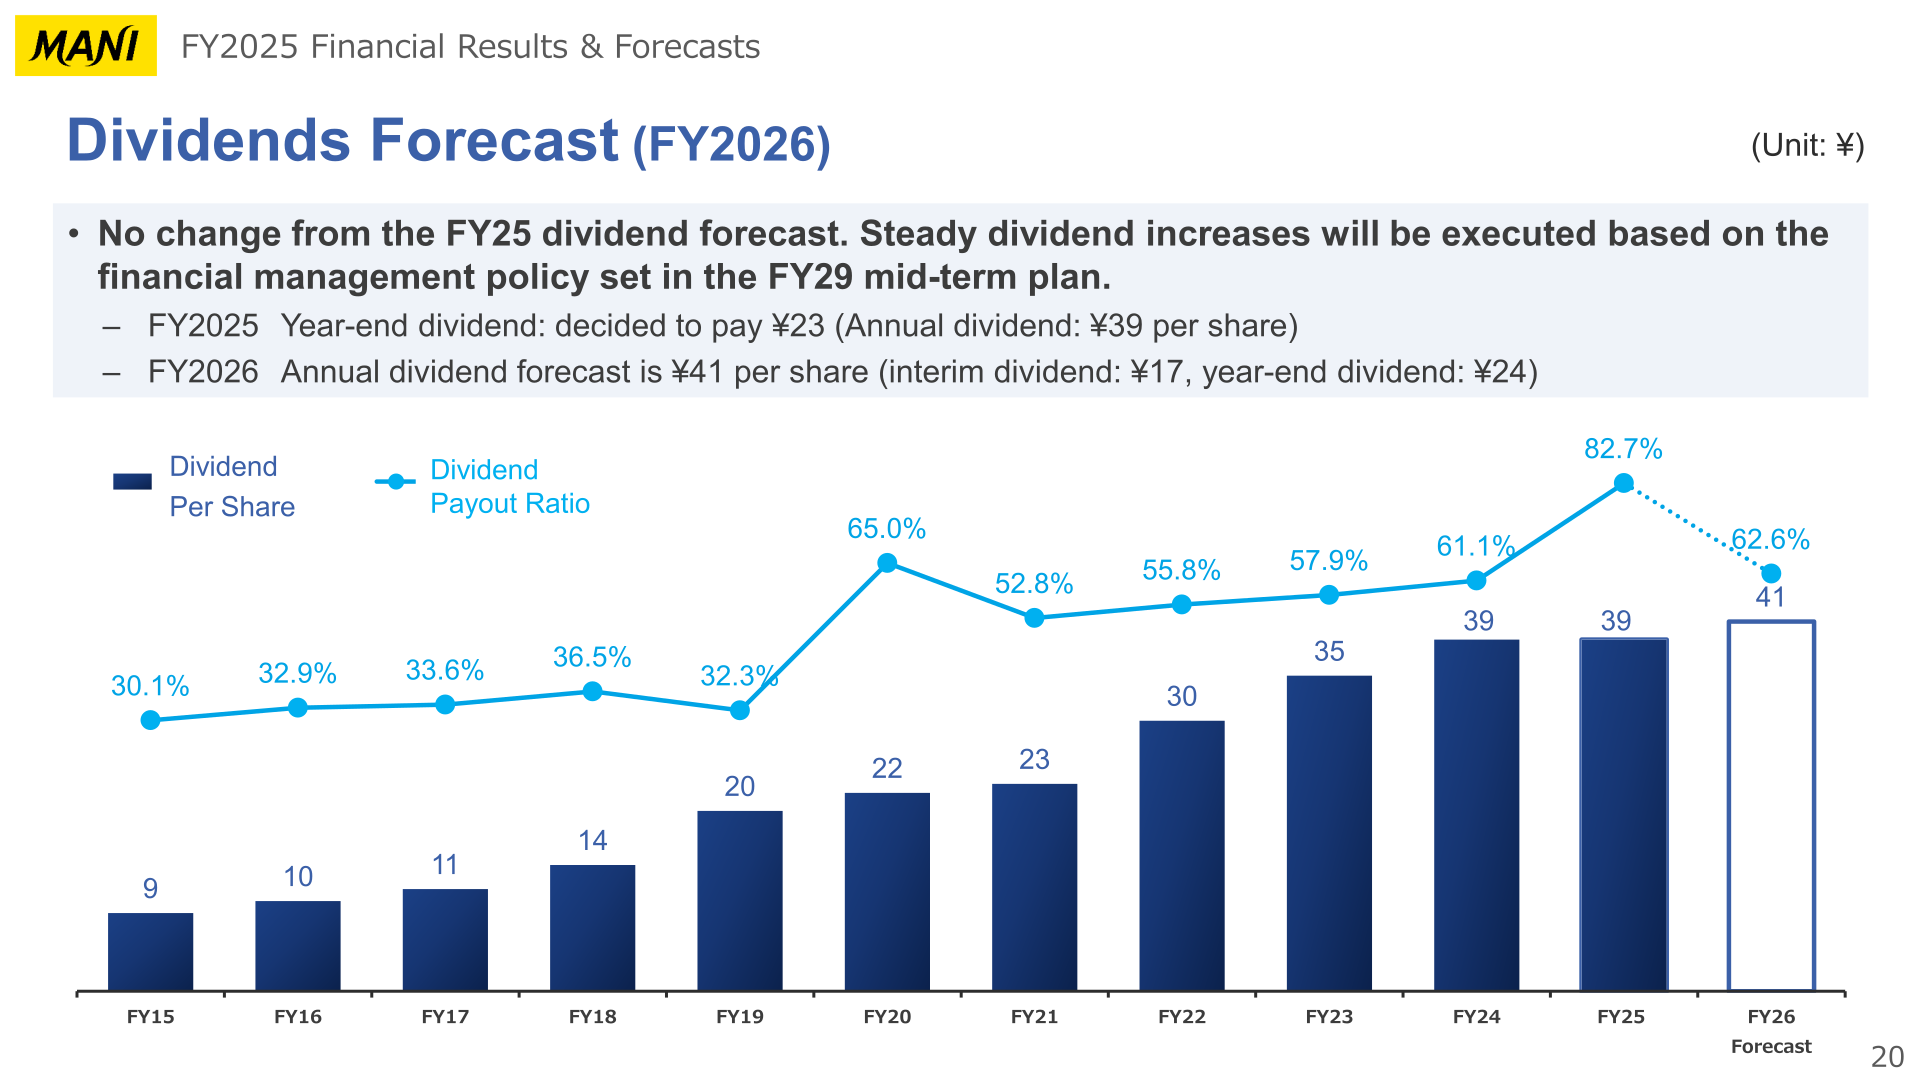
There is no change from the FY2025 dividend forecast. The company decided on a FY2025 year-end dividend of ¥23 per share (annual dividend: ¥39 per share). For FY2026, the company forecasts an annual dividend of ¥41 per share (interim dividend ¥17, year-end dividend ¥24), continuing the steady dividend increases set out under the financial management policy of its FY29 medium-term plan.
| Item | FY2025 | FY2026 Forecast |
|---|---|---|
| Annual dividend per share | ¥39 | ¥41 |
| Interim dividend per share | – | ¥17 |
| Year-end dividend per share | ¥23 | ¥24 |
| Dividend payout ratio | 82.7% | 62.6% |
Medium-Term Plan / Topics
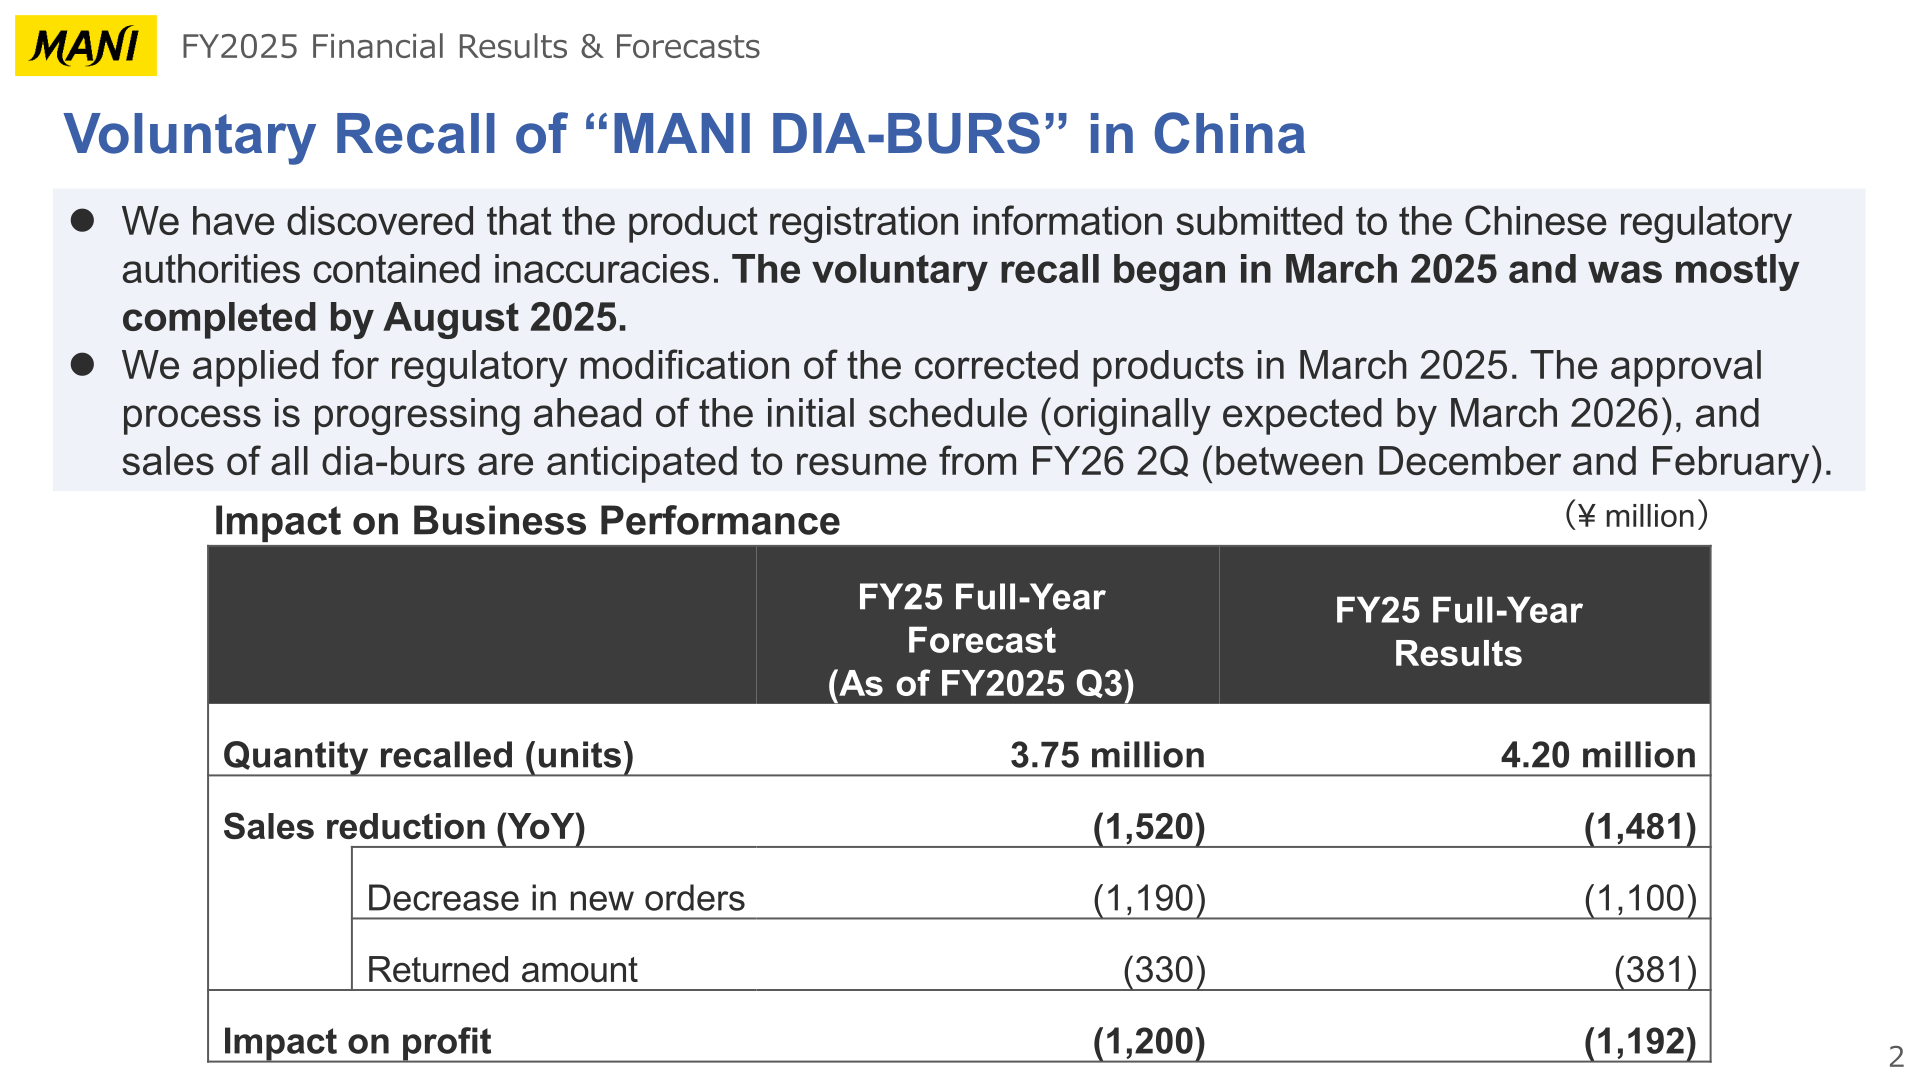
MANI’s new medium-term plan targets FY29 consolidated net sales of ¥45 billion and an operating income margin of 32%. Regarding the voluntary recall of dia-burs in China, the company applied for regulatory modification of the corrected products in March 2025; the approval process is progressing ahead of the initial schedule (originally expected by March 2026), and sales of all dia-burs are anticipated to resume from FY2026 2Q (December 2025-February 2026). Cumulative shipments of the company’s JIZAI product series reached 340,000 units in FY2025 (+56% year on year), achieving the initial plan; the company plans to continue expanding the JIZAI series, including development of JIZAI-2. The company is also promoting a turnaround of its German subsidiary MMG, which recorded a non-current asset impairment in FY2025.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















