
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note on fiscal-year labels: Takasho Co., Ltd. closes its books on January 20, and the company labels the year ended January 20, 2026 as “FY2026” and the prior year as “FY2025”. This article keeps the company’s own labels in the text, tables and charts, while the site classifies the most recently completed fiscal year as FY2025.
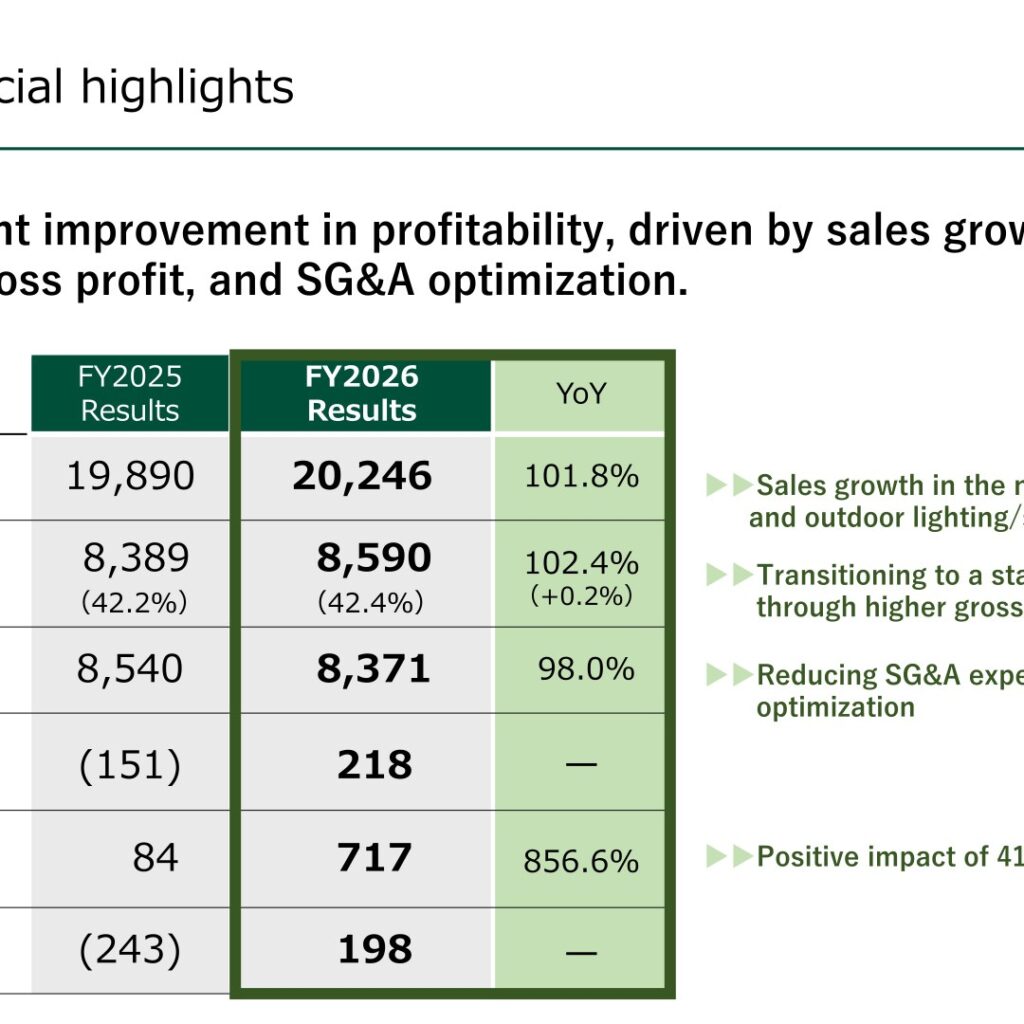
Takasho Co., Ltd. (7590) returned to profit in FY2026 (the fiscal year ended January 20, 2026). Net sales were 20,246 million yen, or 101.8% year on year, operating income was 218 million yen against an operating loss of 151 million yen in the previous period, ordinary income was 717 million yen at 856.6% year on year, and net income was 198 million yen against a net loss of 243 million yen. The company describes the drivers as sales growth in the non-residential sector of the Pro-use business and in the outdoor lighting/signage (Digitec) business, a higher gross profit margin, optimization of SG&A expenses, and foreign exchange gains of 419 million yen.
Consolidated Results (Full-Year Actual)
The materials describe the period as a shift “from correction phase to recovery phase”, with significant improvement in profitability driven by sales growth, higher gross profit and SG&A optimization. Gross profit margin improved from 42.2% in FY2025 to 42.4% in FY2026, while the SG&A ratio fell from 42.9% in FY2025 to 41.3% in FY2026. On the three-year trend slide, net sales are shown as 194.1, 198.9 and 202.4 (100 million yen) for FY2024, FY2025 and FY2026, and operating profit as -1.0, -1.5 and 2.18 (100 million yen). EBITDA is shown at 596 million yen for FY2024, 647 million yen for FY2025 and 1,001 million yen for FY2026, or 155% year on year.
| Item (Million yen) | FY2025 Results | FY2026 Results | YoY |
|---|---|---|---|
| Net sales | 19,890 | 20,246 | 101.8% |
| Gross profit (Gross profit %) | 8,389 (42.2%) | 8,590 (42.4%) | 102.4% (+0.2%) |
| SG&A | 8,540 | 8,371 | 98.0% |
| Operating income | (151) | 218 | – |
| Ordinary income | 84 | 717 | 856.6% |
| Net income | (243) | 198 | – |
Segment Results
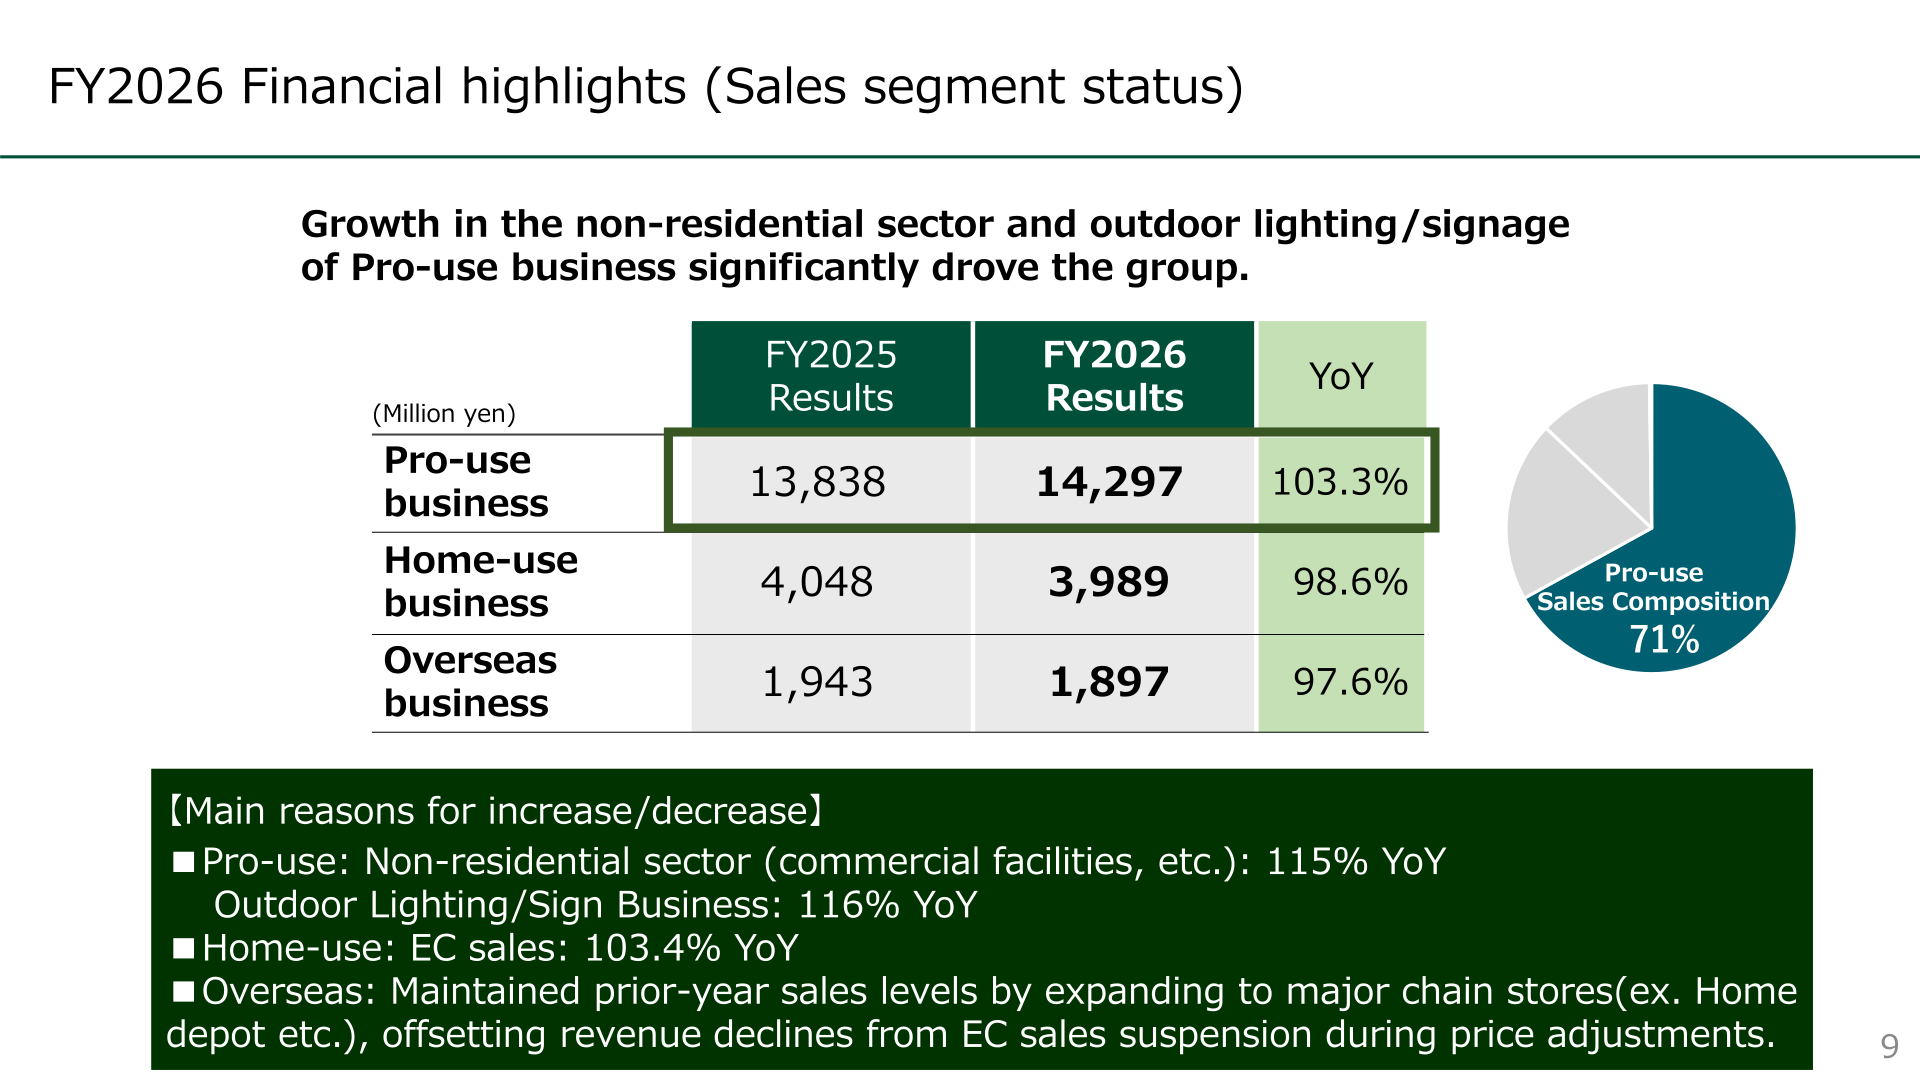
The Pro-use business, which accounts for 71% of sales, drove the group. Within it, the non-residential sector (commercial facilities and similar) grew to 115% year on year and the outdoor lighting/signage business to 116% year on year. In the Home-use business, EC sales were 103.4% year on year. The Overseas business maintained prior-year sales levels by expanding to major chain stores such as Home Depot, offsetting revenue declines from the suspension of EC sales during price adjustments. TAKASHO DIGITEC, which represents 19% of sales composition, grew from 3,238 million yen to 3,765 million yen, or 116% year on year, on expanded adoption in the non-residential sector.
| Segment (Million yen) | FY2025 Results | FY2026 Results | YoY | FY2027 Plan |
|---|---|---|---|---|
| Pro-use business | 13,838 | 14,297 | 103.3% | 15,209 |
| Home-use business | 4,048 | 3,989 | 98.6% | 4,634 |
| Overseas business | 1,943 | 1,897 | 97.6% | 3,040 |
Variance Between Forecast and Actual for FY2026
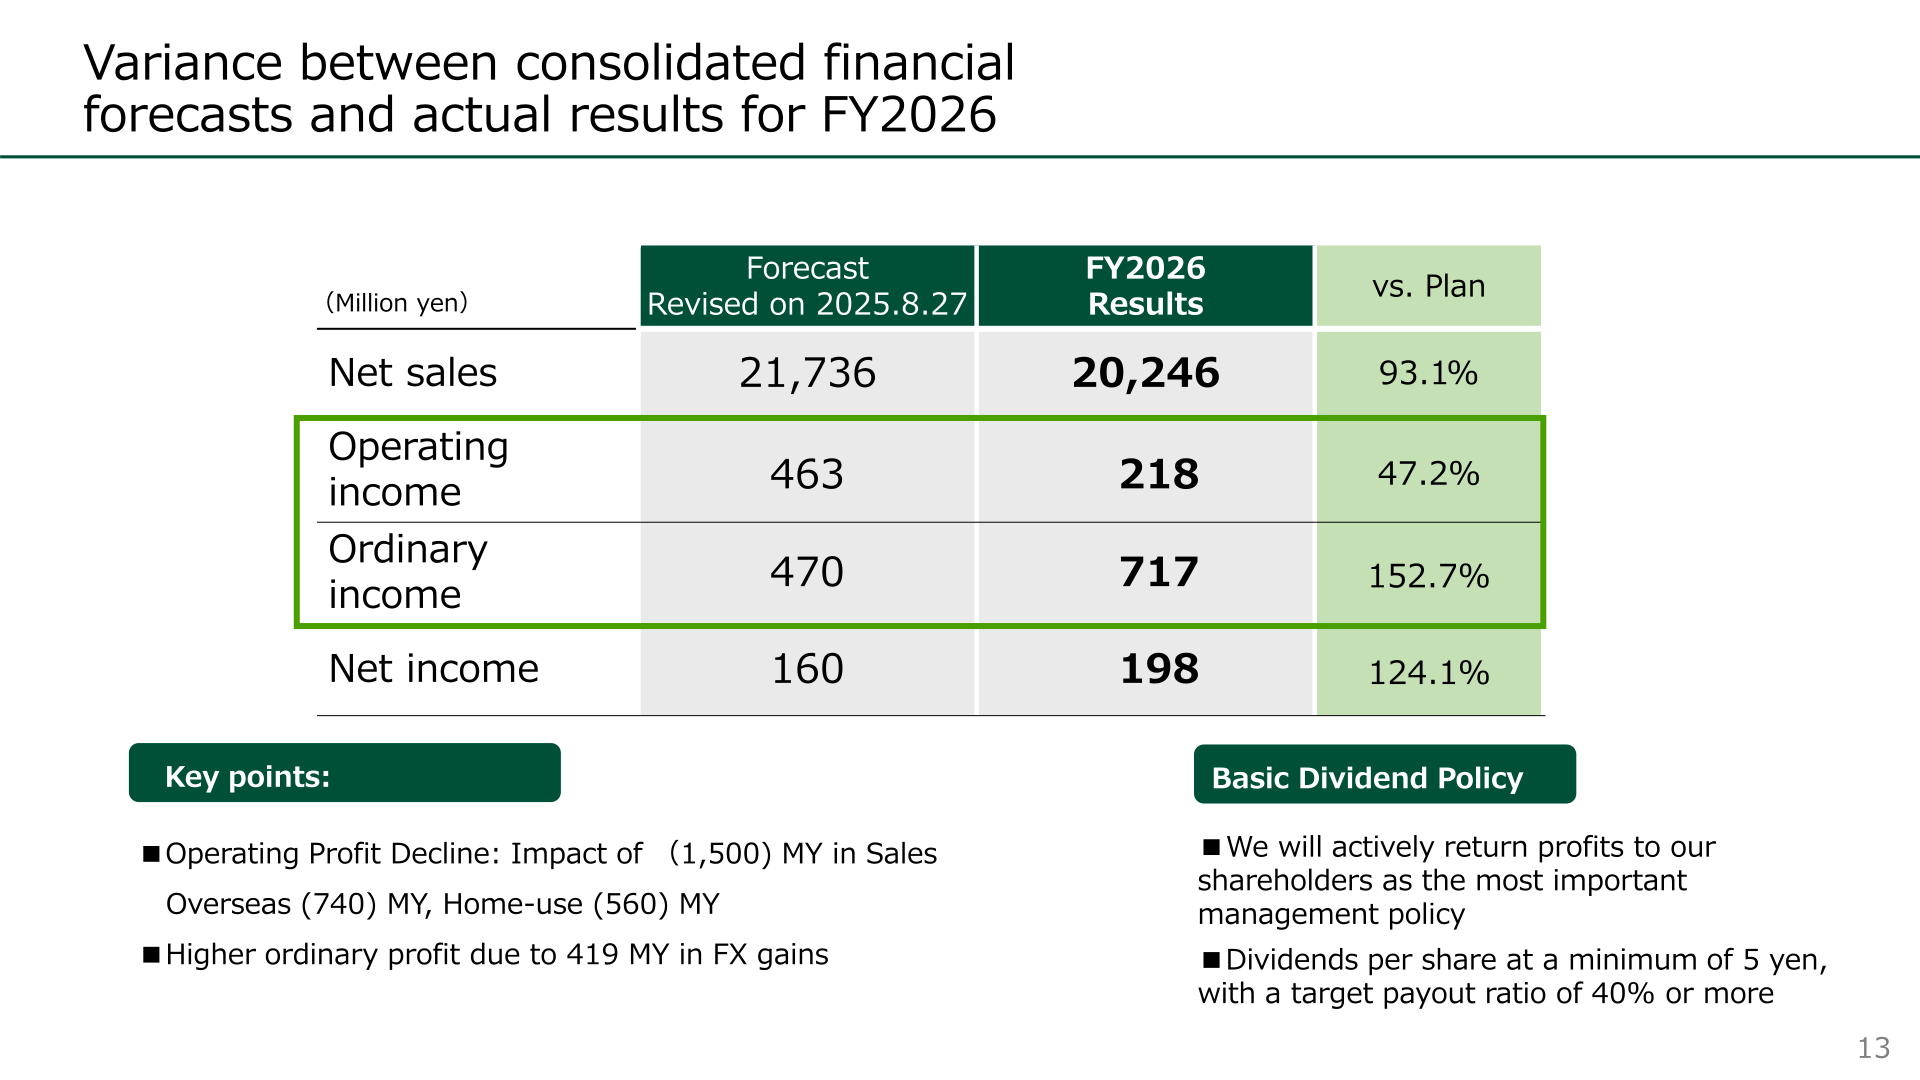
Against the forecast revised on 2025.8.27, net sales came in at 93.1% of plan and operating income at 47.2% of plan, while ordinary income reached 152.7% and net income 124.1% of plan. The materials attribute the operating profit shortfall to a sales impact of (1,500) million yen, comprising Overseas (740) million yen and Home-use (560) million yen, and the higher ordinary profit to 419 million yen of foreign exchange gains.
| Item (Million yen) | Forecast (revised 2025.8.27) | FY2026 Results | vs. Plan |
|---|---|---|---|
| Net sales | 21,736 | 20,246 | 93.1% |
| Operating income | 463 | 218 | 47.2% |
| Ordinary income | 470 | 717 | 152.7% |
| Net income | 160 | 198 | 124.1% |
FY2027 Forecast
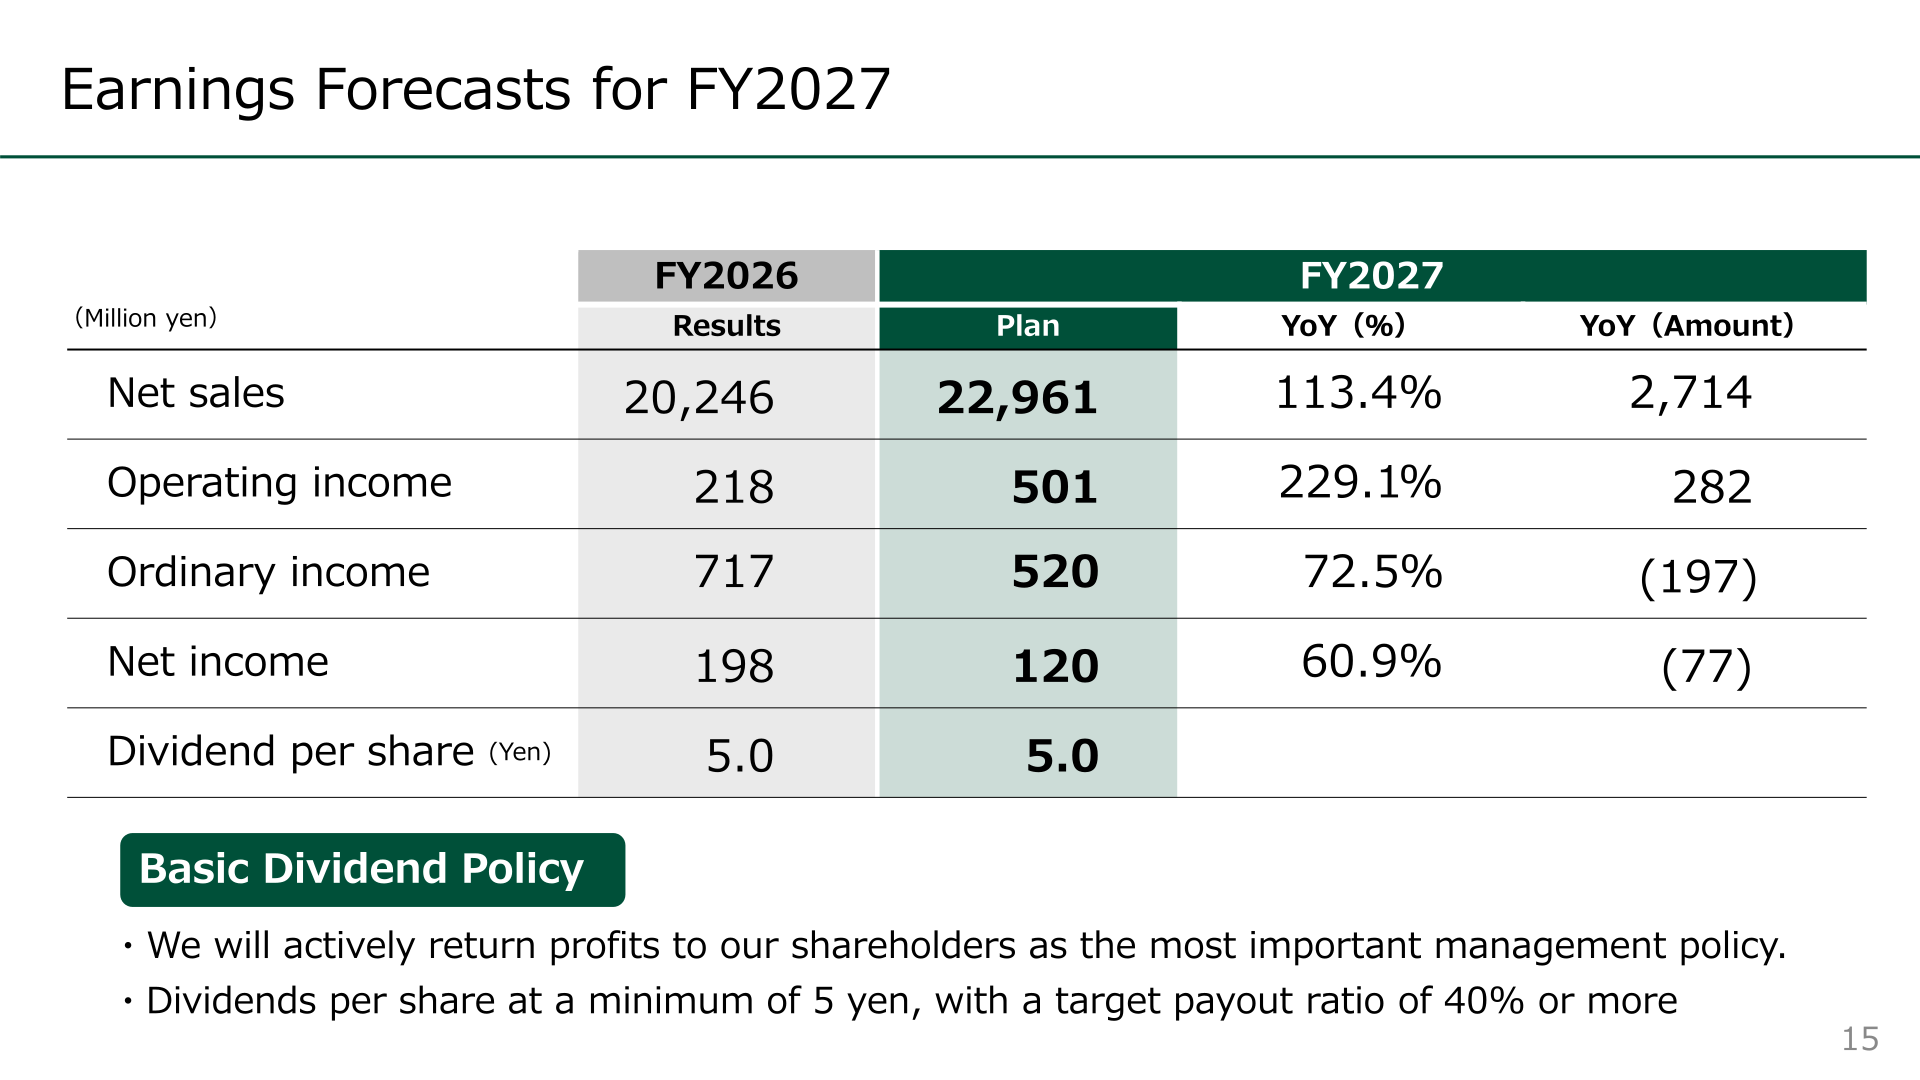
For FY2027, the company plans net sales of 22,961 million yen (113.4% year on year, an increase of 2,714 million yen) and operating income of 501 million yen (229.1% year on year, an increase of 282 million yen). Ordinary income is planned at 520 million yen (72.5% year on year, a decrease of 197 million yen) and net income at 120 million yen (60.9% year on year, a decrease of 77 million yen). By segment, the plan calls for growth of 913 million yen in Pro-use, 645 million yen in Home-use and 1,143 million yen in Overseas. Stated initiatives include development of DX sales tools and expansion in the non-residential sector (hotels, restaurants, commercial facilities) and promotion of the lighting business for Pro-use; strengthening EC sales and new product rollout for Home-use; and expanding major chain stores, strengthening the sales structure in the United States and expanding into untapped markets in Europe for Overseas.
| Item | FY2026 Results | FY2027 Plan | YoY (%) | YoY (Amount) |
|---|---|---|---|---|
| Net sales (Million yen) | 20,246 | 22,961 | 113.4% | 2,714 |
| Operating income (Million yen) | 218 | 501 | 229.1% | 282 |
| Ordinary income (Million yen) | 717 | 520 | 72.5% | (197) |
| Net income (Million yen) | 198 | 120 | 60.9% | (77) |
| Dividend per share (Yen) | 5.0 | 5.0 | – | – |
Shareholder Returns
The basic dividend policy stated in the materials is that the company will actively return profits to shareholders as its most important management policy, with dividends per share of a minimum of 5 yen and a target payout ratio of 40% or more. The dividend per share is 5.0 yen for FY2026 results and 5.0 yen in the FY2027 plan.
Medium-to-Long-Term Plan and Topics
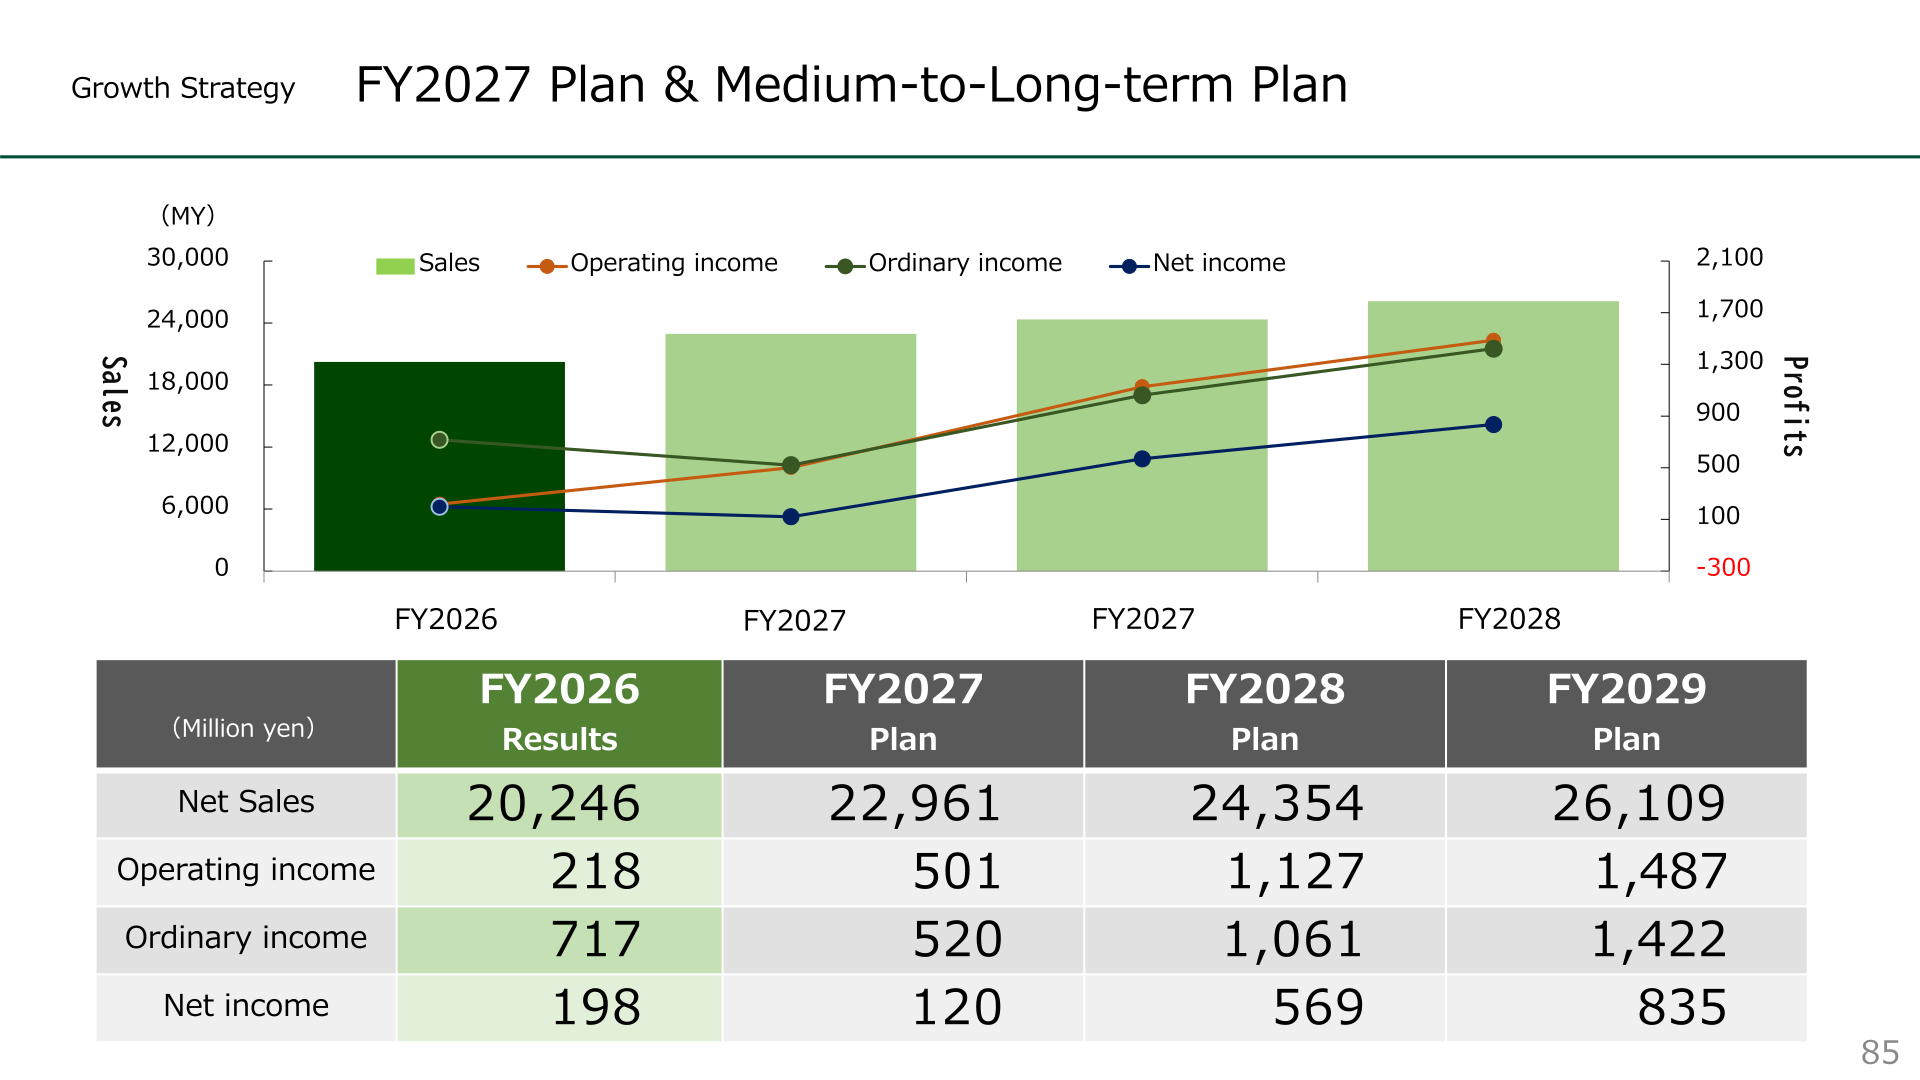
The medium-to-long-term plan shown in the materials runs through FY2029. On the growth strategy, the company promotes hybrid sales that fuse digital (DX) and real products, with GLD-LAB. Co., Ltd. as its software factory in Japan, the Philippines and Vietnam, and Garden Create Co., Ltd. and Takasho DIGITEC Co., Ltd. as manufacturing operations. A new factory of Digitec China of 10,370.6 square meters (500 million yen) started operation, and factory expansion in Wakayama began operation in February 2025. For TAKASHO DIGITEC, the materials show sales rising from 2 billion yen in FY2024 to 6.0 billion yen in FY2028, with the internal/external sales mix moving from 70%/30% to 48%/52% by FY2026, and state that sales are expected to increase by 160% within 2 years. Overseas, the company aims to become the world’s No.1 garden category manufacturer; Home Depot rollout begins this fall at 31 stores with expansion to 130 stores planned for the next fiscal year, and Bunnings implementation started from this summer in 100 stores with expansion to 140 stores next fiscal year. E-commerce at Amazon and Home Depot, temporarily stopped to adjust selling prices, resumed in July, and the company is partnering with a domestic manufacturing factory in the United States as a countermeasure against tariffs. Topics also include the private viewing of new products at the Shinagawa Showroom from February 3 to 6, 2026, and an exhibit at the International Horticultural Expo 2027 in Yokohama, scheduled from March 19 to September 26, 2027.
| Item (Million yen) | FY2026 Results | FY2027 Plan | FY2028 Plan | FY2029 Plan |
|---|---|---|---|---|
| Net Sales | 20,246 | 22,961 | 24,354 | 26,109 |
| Operating income | 218 | 501 | 1,127 | 1,487 |
| Ordinary income | 717 | 520 | 1,061 | 1,422 |
| Net income | 198 | 120 | 569 | 835 |
| Pro-use | 14,297 | 15,209 | 16,018 | 17,085 |
| Home-use | 3,989 | 4,634 | 4,796 | 5,317 |
| Overseas | 1,897 | 3,040 | 3,455 | 3,617 |
| Others | 63 | 76 | 83 | 88 |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















