
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Onoken does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. This site classifies the most recent completed fiscal year as FY2025, while the company’s materials label the period as the fiscal year ended March 2026 (FY3/2026). In FY3/2026, Onoken saw an overall decline in revenue as steel demand and steel product market conditions in the steel business were sluggish. In addition to the overall revenue decline, operating profit fell on higher depreciation centered on newly built warehouses, and the company recorded impairment losses on fixed assets in the Kyushu and Chugoku areas as an extraordinary loss, resulting in the first net loss since its listing. For FY3/2027, based on a phase of price increases accompanying the rise in steel product market conditions and steady progress in orders for large-scale construction projects, the company has formulated a plan for higher revenue, higher profit and a return to net profit. It intends to maintain the minimum annual dividend of 69 yen per share in both FY3/2026 and FY3/2027.
Consolidated Results (FY3/2026 Actual)
Net sales were 253,115 million yen (△6.9% year on year), operating profit was 4,740 million yen (△30.4%) and ordinary profit was 4,711 million yen (△31.7%). Profit attributable to owners of parent was △2,218 million yen (versus a profit of 4,885 million yen in the previous fiscal year), the first net loss since the company’s listing. Against the FY3/2026 plan (announced November 7, 2025), net sales came in at △0.6%, while operating profit exceeded the plan by +3.0% and ordinary profit by 2.4%; net profit fell below the planned 3,000 million yen and ended in a loss.
| Item | FY3/2025 (Full Year) | FY3/2026 (Full Year) | YoY |
|---|---|---|---|
| Net sales (million yen) | 271,942 | 253,115 | △6.9% |
| Operating profit (million yen) | 6,810 | 4,740 | △30.4% |
| Ordinary profit (million yen) | 6,902 | 4,711 | △31.7% |
| Profit attributable to owners of parent (million yen) | 4,885 | △2,218 | — |
Segment (Area) Results
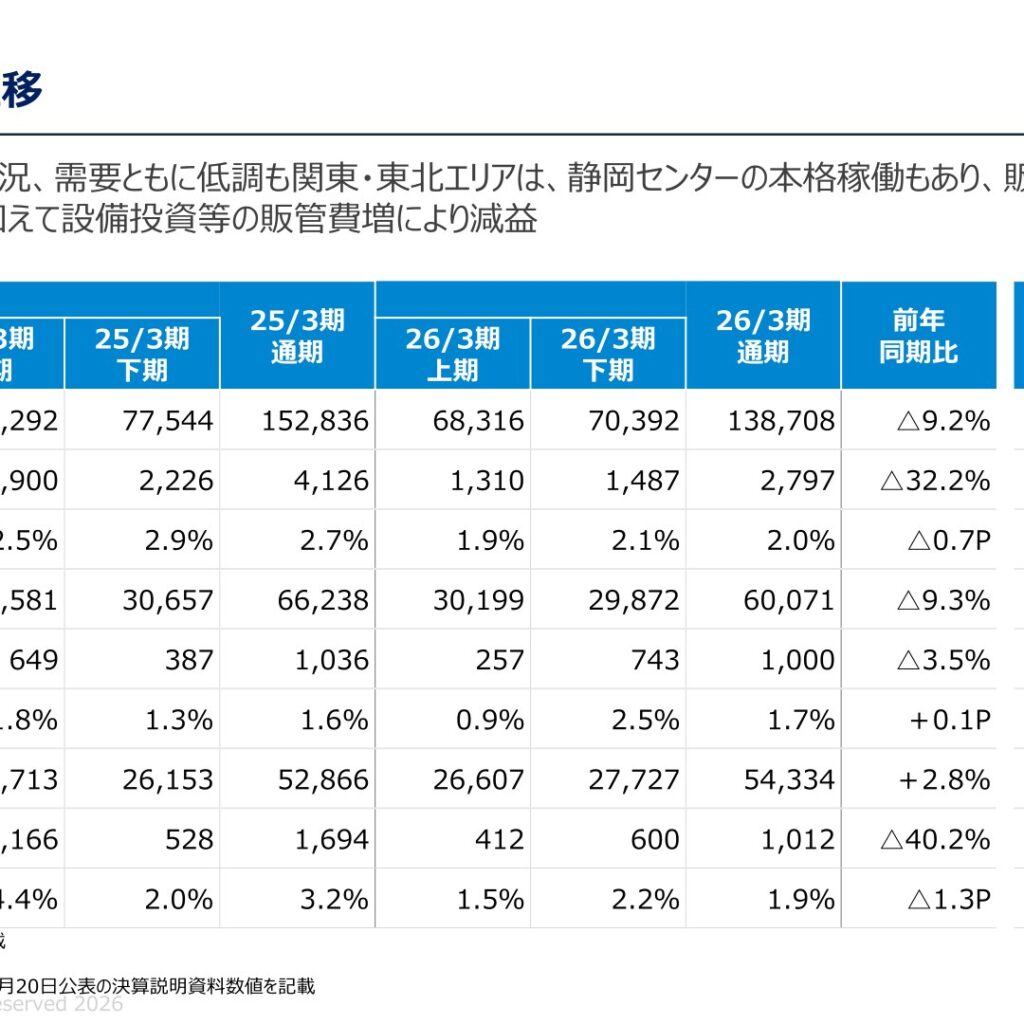
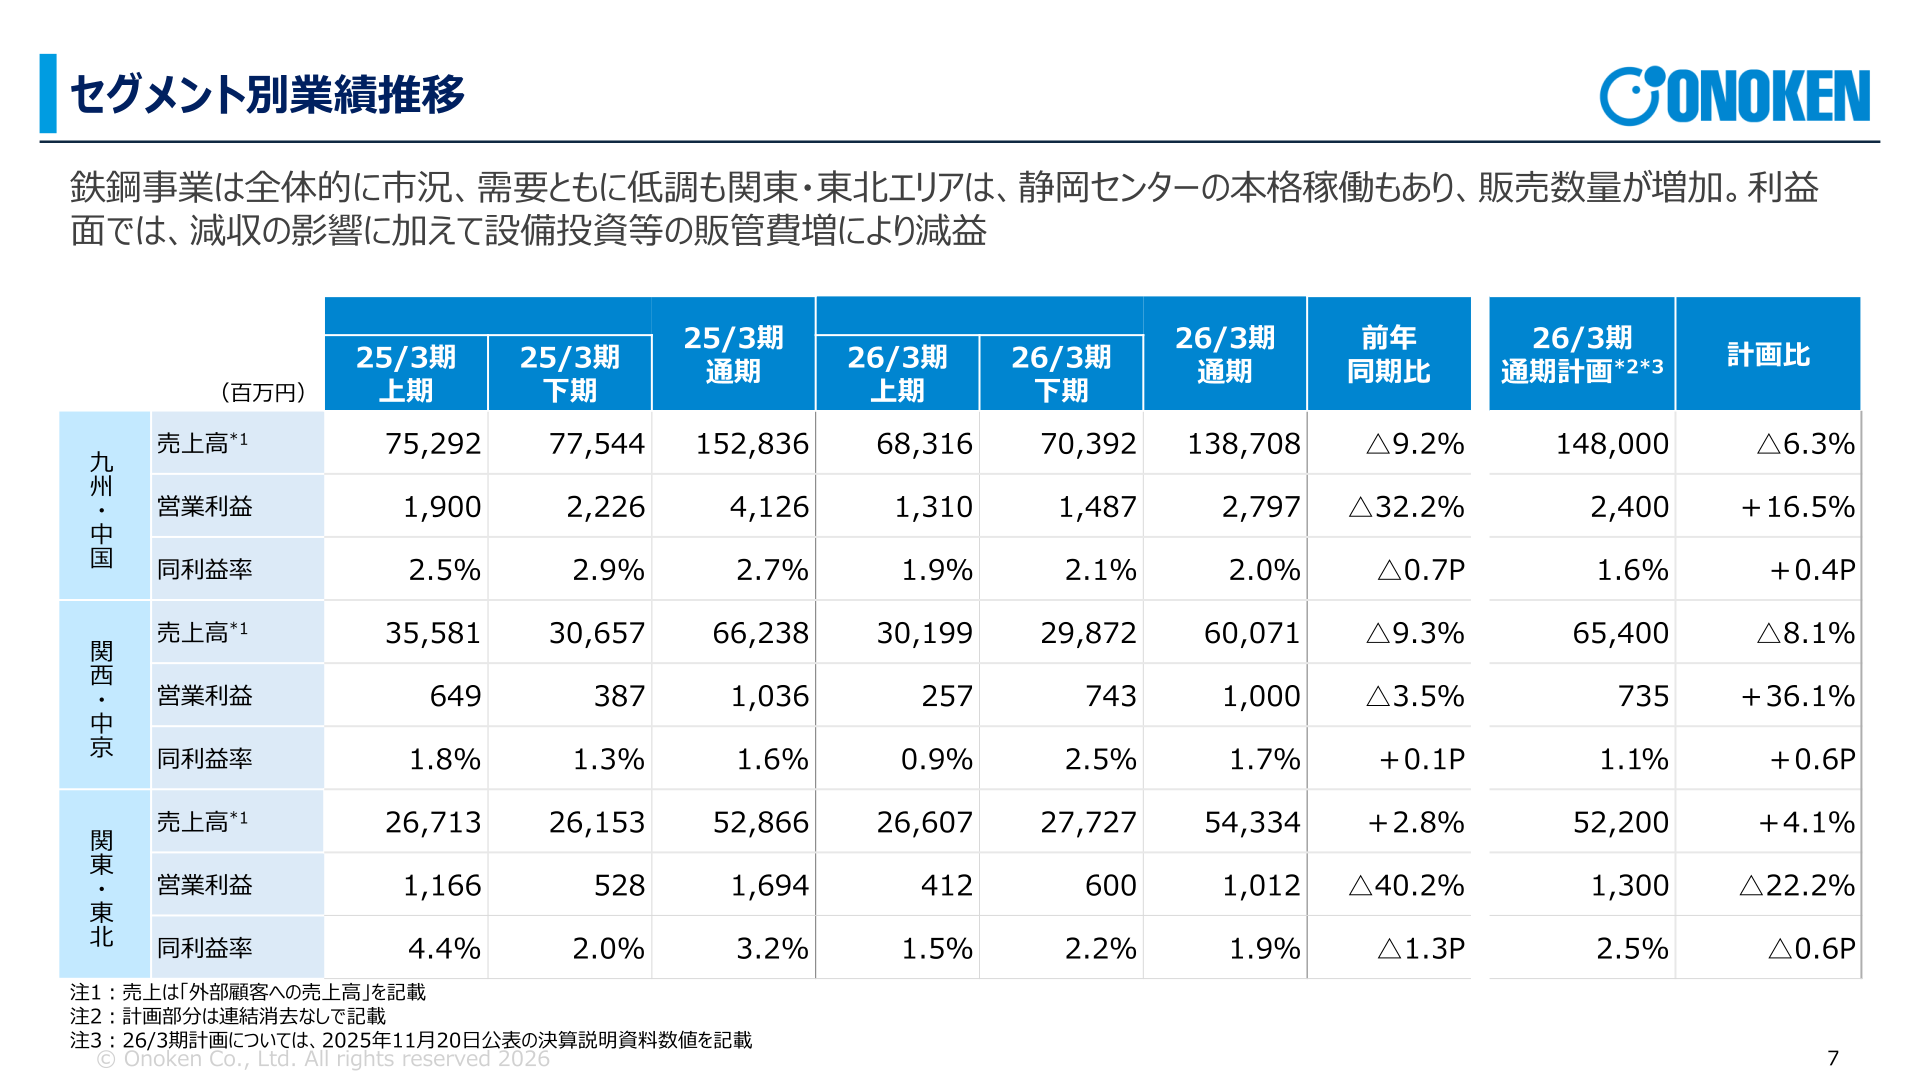
FY3/2026 results are disclosed under a three-area structure: Kyushu/Chugoku, Kansai/Chukyo and Kanto/Tohoku. In the steel business, market conditions and demand were generally sluggish, but sales volume increased in the Kanto/Tohoku area, helped by the full-scale operation of the Shizuoka Center. Kyushu/Chugoku posted net sales of 138,708 million yen (△9.2% year on year) and operating profit of 2,797 million yen (△32.2%); Kansai/Chukyo posted net sales of 60,071 million yen (△9.3%) and operating profit of 1,000 million yen (△3.5%); and Kanto/Tohoku posted net sales of 54,334 million yen (+2.8%) and operating profit of 1,012 million yen (△40.2%).
| Area | Metric | FY3/2025 (Full Year) | FY3/2026 (Full Year) |
|---|---|---|---|
| Kyushu/Chugoku | Net sales (million yen) | 152,836 | 138,708 |
| Kyushu/Chugoku | Operating profit (million yen) | 4,126 | 2,797 |
| Kansai/Chukyo | Net sales (million yen) | 66,238 | 60,071 |
| Kansai/Chukyo | Operating profit (million yen) | 1,036 | 1,000 |
| Kanto/Tohoku | Net sales (million yen) | 52,866 | 54,334 |
| Kanto/Tohoku | Operating profit (million yen) | 1,694 | 1,012 |
Full-Year Forecast (FY3/2027)
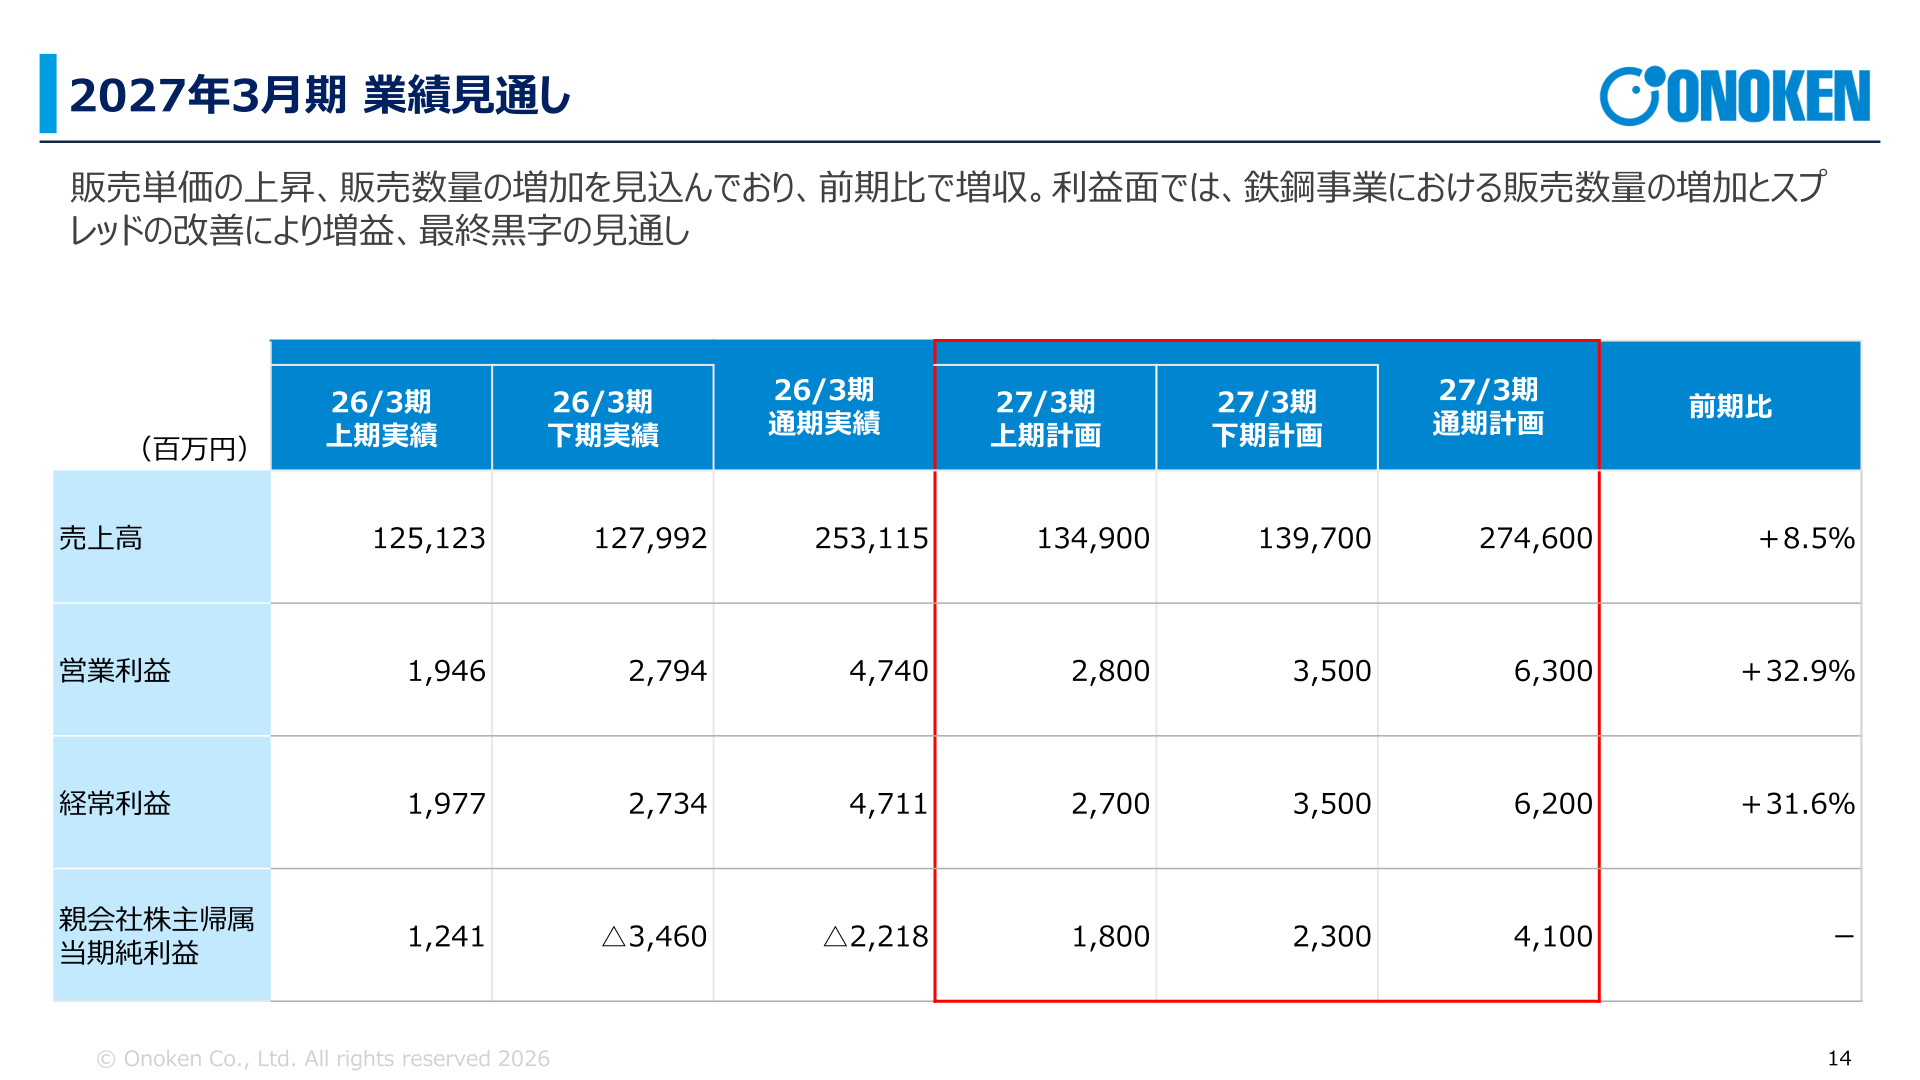
For FY3/2027, the company plans higher revenue, higher profit and a return to net profit, anticipating higher selling prices against the backdrop of an upward trend in steel product market conditions, an earnings boost from inventory valuation gains, and progress on large-scale projects already received in the construction business. It plans net sales of 274,600 million yen (+8.5% versus the previous fiscal year), operating profit of 6,300 million yen (+32.9%), ordinary profit of 6,200 million yen (+31.6%) and profit attributable to owners of parent of 4,100 million yen (versus a loss of △2,218 million yen in the previous fiscal year).
| Item | FY3/2026 (Full-Year Actual) | FY3/2027 (Full-Year Plan) | YoY |
|---|---|---|---|
| Net sales (million yen) | 253,115 | 274,600 | +8.5% |
| Operating profit (million yen) | 4,740 | 6,300 | +32.9% |
| Ordinary profit (million yen) | 4,711 | 6,200 | +31.6% |
| Profit attributable to owners of parent (million yen) | △2,218 | 4,100 | — |
Segment Outlook (FY3/2027 Plan)
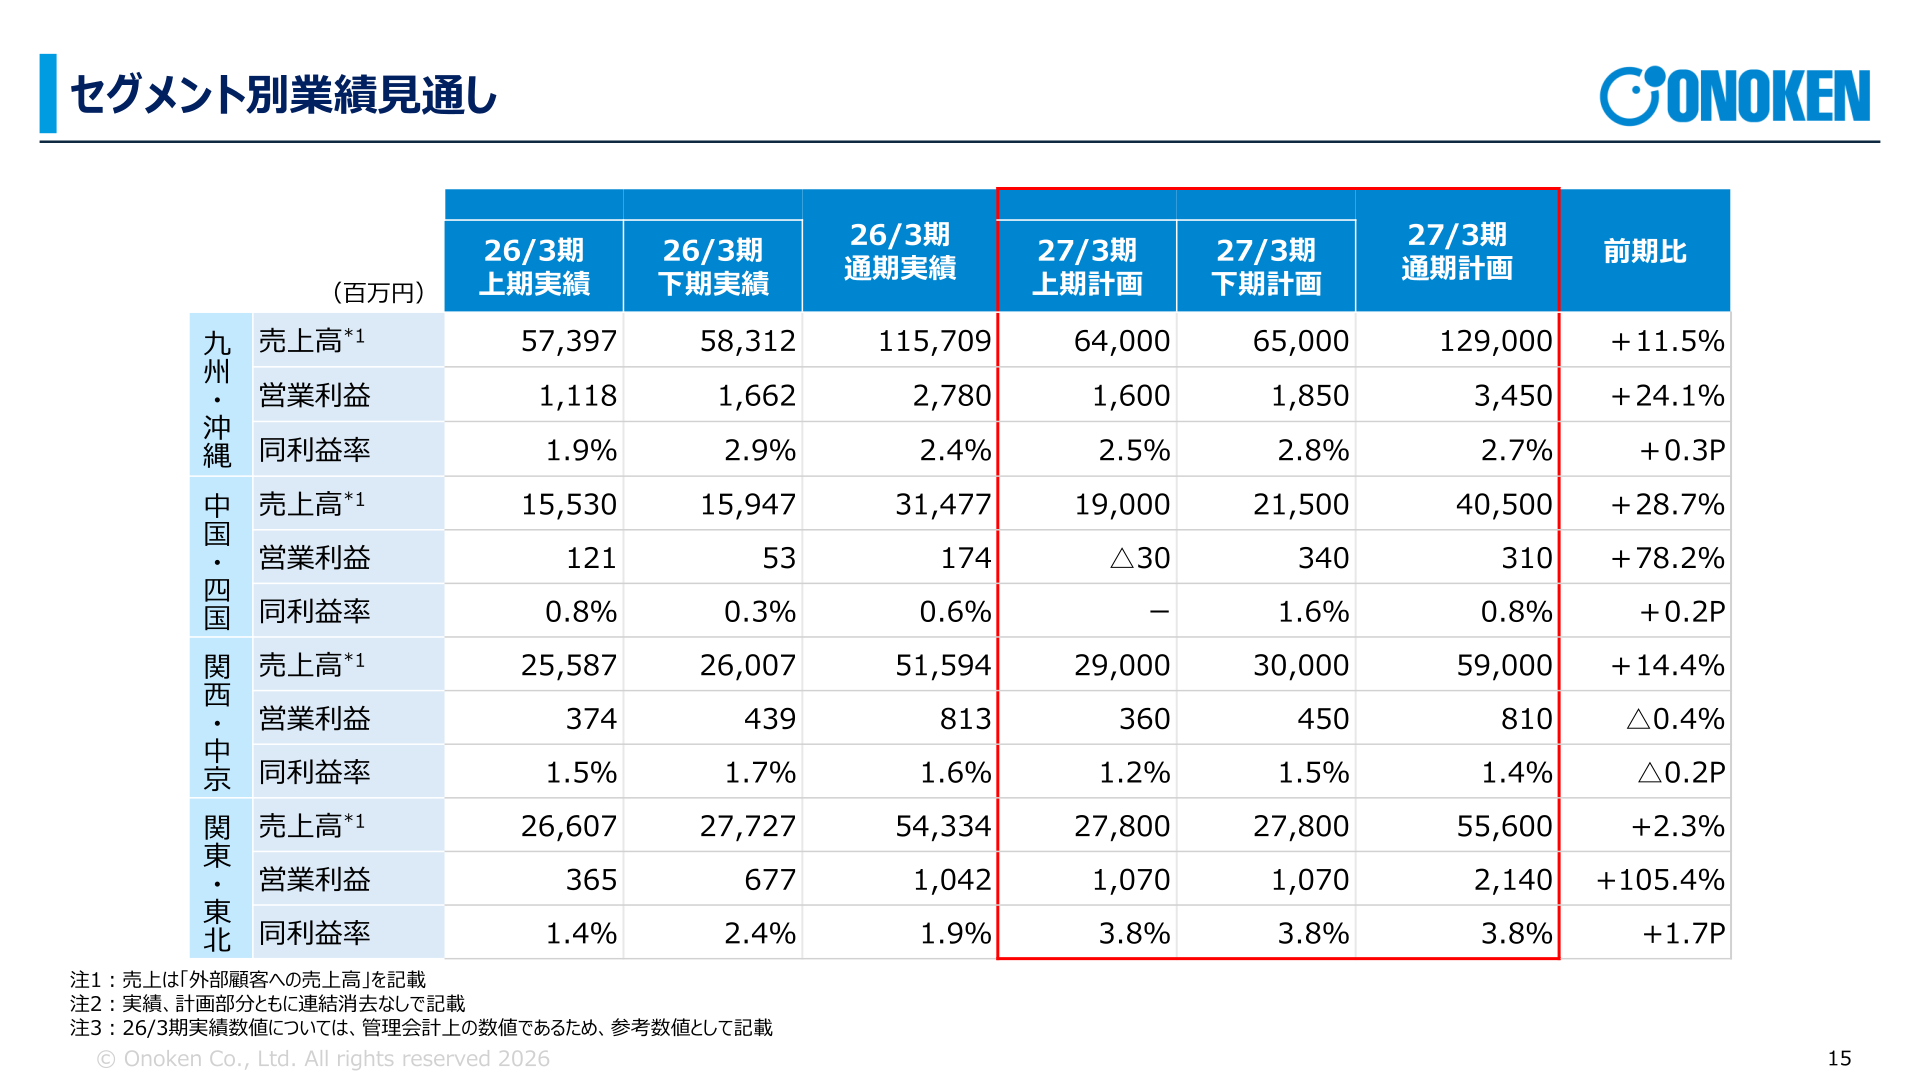
The FY3/2027 plan is disclosed under a four-area structure: Kyushu/Okinawa, Chugoku/Shikoku, Kansai/Chukyo and Kanto/Tohoku (per a note in the materials, the FY3/2026 actual figures are reference figures on a management accounting basis). Kyushu/Okinawa plans net sales of 129,000 million yen (+11.5% versus the previous fiscal year) and operating profit of 3,450 million yen (+24.1%); Chugoku/Shikoku plans net sales of 40,500 million yen (+28.7%) and operating profit of 310 million yen (+78.2%); Kansai/Chukyo plans net sales of 59,000 million yen (+14.4%) and operating profit of 810 million yen (△0.4%); and Kanto/Tohoku plans net sales of 55,600 million yen (+2.3%) and operating profit of 2,140 million yen (+105.4%).
Shareholder Returns
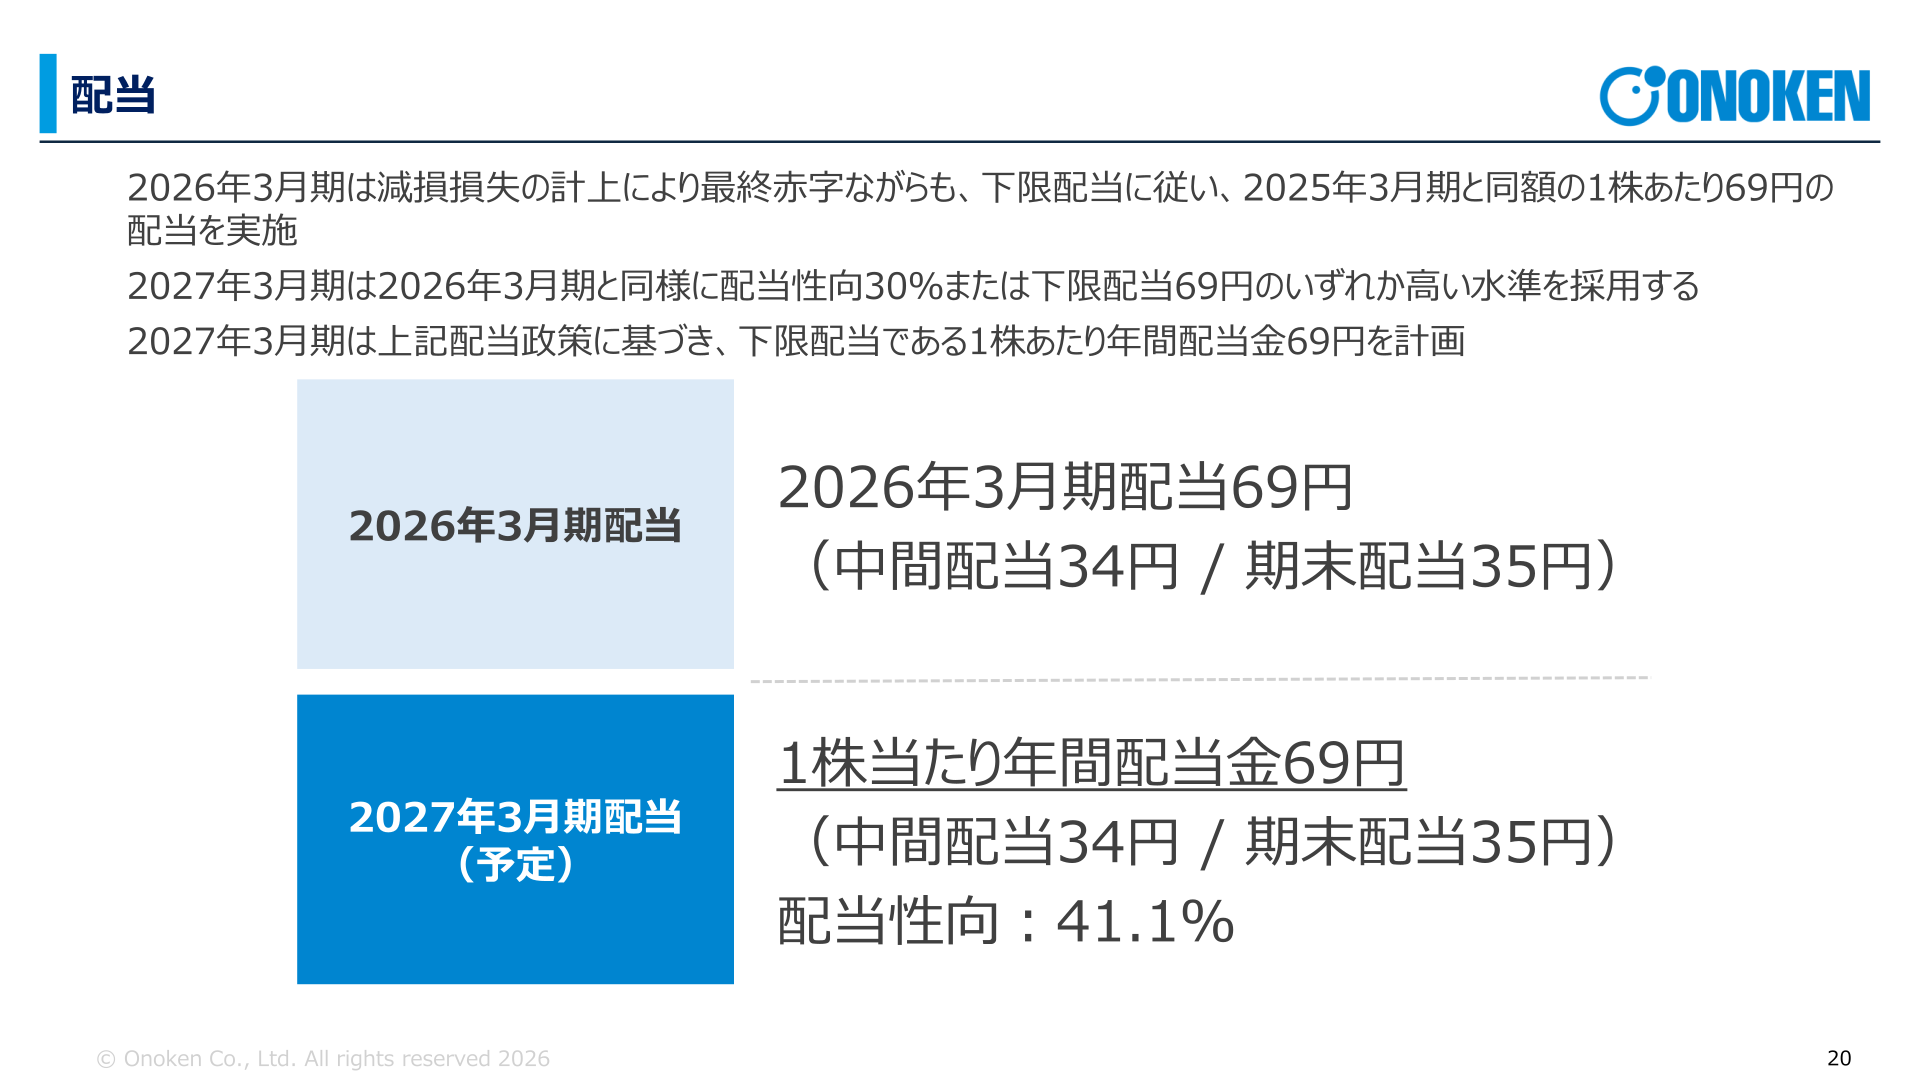
Although FY3/2026 ended in a net loss due to the recording of impairment losses, in line with its minimum dividend policy the company paid an annual dividend of 69 yen per share (34 yen interim, 35 yen year-end; payout ratio 41.1%), the same amount as in FY3/2025. For FY3/2027 the company likewise intends to adopt whichever is higher, a payout ratio of 30% or the minimum dividend of 69 yen, and plans the minimum annual dividend of 69 yen per share (planned). In addition, in FY3/2026 the company carried out a share buyback with an upper limit of 1 billion yen.
| Item | FY3/2026 | FY3/2027 (Planned) |
|---|---|---|
| Annual dividend per share | 69 yen (34 yen interim, 35 yen year-end) | 69 yen |
| Payout ratio | 41.1% | Whichever is higher: the minimum dividend of 69 yen or a payout ratio of 30% |
Progress on the Medium-Term Management Plan
The First Medium-Term Management Plan (FY3/2026 to FY3/2028) is positioned as a period for building the foundations to achieve Long-Term Vision 2035 (targets for FY3/2035 of net sales of 500 billion yen, EBITDA of 24 billion yen, operating profit of 20 billion yen, ROE of 10% and ROIC of 6%). In FY3/2026 the company executed three M&A deals — Chuo Kozai (June 2025), Marumi Kosho (September 2025) and Stahl Kakefu (January 2026) — and it also plans to acquire shares in Sanyu Kozai Co., Ltd. on May 29, 2026. The Medium-Term Management Plan targets for FY3/2028 are net sales of 310 billion yen, EBITDA of 12.5 billion yen, operating profit of 7.5 billion yen and ROE of 6.0%.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















