
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Aichi Financial Group, the Nagoya-based holding company of Aichi Bank, reported FG consolidated ordinary profits of 30.9 billion yen and profit attributable to owners of parent of 21.8 billion yen for the fiscal year ended March 31, 2026 (FY2025), up 20.6 billion yen and 12.7 billion yen year on year respectively. The company plans an annual dividend of 135 yen per share, up 25 yen year on year. For the fiscal year ending March 31, 2027 (FY2026) it forecasts consolidated profit of 23.0 billion yen, and it has raised the final-year targets of its 2nd Medium-Term Business Plan. Separately, the group concluded a basic agreement on a business integration with San ju San Financial Group.
Consolidated Results (Full-Year Actual)
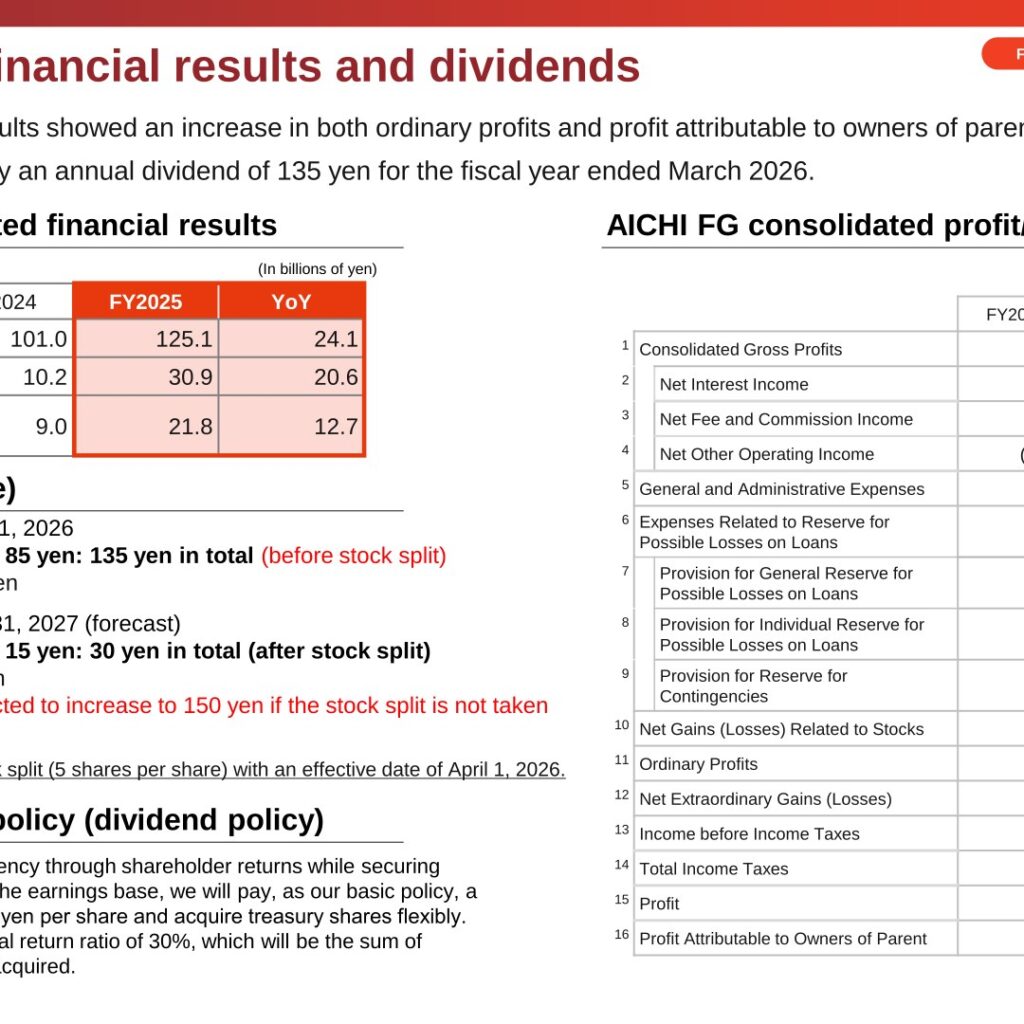
On an FG consolidated basis, ordinary income rose to 125.1 billion yen from 101.0 billion yen, and both ordinary profits and profit attributable to owners of parent increased. Consolidated gross profits were 58.5 billion yen (up 8.6 billion yen), with net interest income of 52.5 billion yen (up 2.1 billion yen) and net other operating income improving by 7.0 billion yen to -6.1 billion yen. General and administrative expenses fell 2.7 billion yen to 45.0 billion yen. Expenses related to the reserve for possible losses on loans swung to -2.2 billion yen, and net gains related to stocks rose 3.7 billion yen to 16.4 billion yen. ROE was 5.56% for FY2025, against 2.48% for FY2024, and the FG consolidated own capital ratio stood at 8.83% as of March 31, 2026 versus 8.78% a year earlier.
| Item (In billions of yen) | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Ordinary Income | 101.0 | 125.1 | 24.1 |
| Consolidated Gross Profits | 49.8 | 58.5 | 8.6 |
| Net Interest Income | 50.4 | 52.5 | 2.1 |
| Net Fee and Commission Income | 12.5 | 12.0 | (0.5) |
| Net Other Operating Income | (13.1) | (6.1) | 7.0 |
| General and Administrative Expenses | 47.7 | 45.0 | (2.7) |
| Expenses Related to Reserve for Possible Losses on Loans | 1.2 | (2.2) | (3.4) |
| Net Gains (Losses) Related to Stocks | 12.6 | 16.4 | 3.7 |
| Ordinary Profits | 10.2 | 30.9 | 20.6 |
| Income before Income Taxes | 9.7 | 29.9 | 20.2 |
| Total Income Taxes | 0.6 | 8.1 | 7.5 |
| Profit Attributable to Owners of Parent | 9.0 | 21.8 | 12.7 |
Aichi Bank Non-Consolidated Results
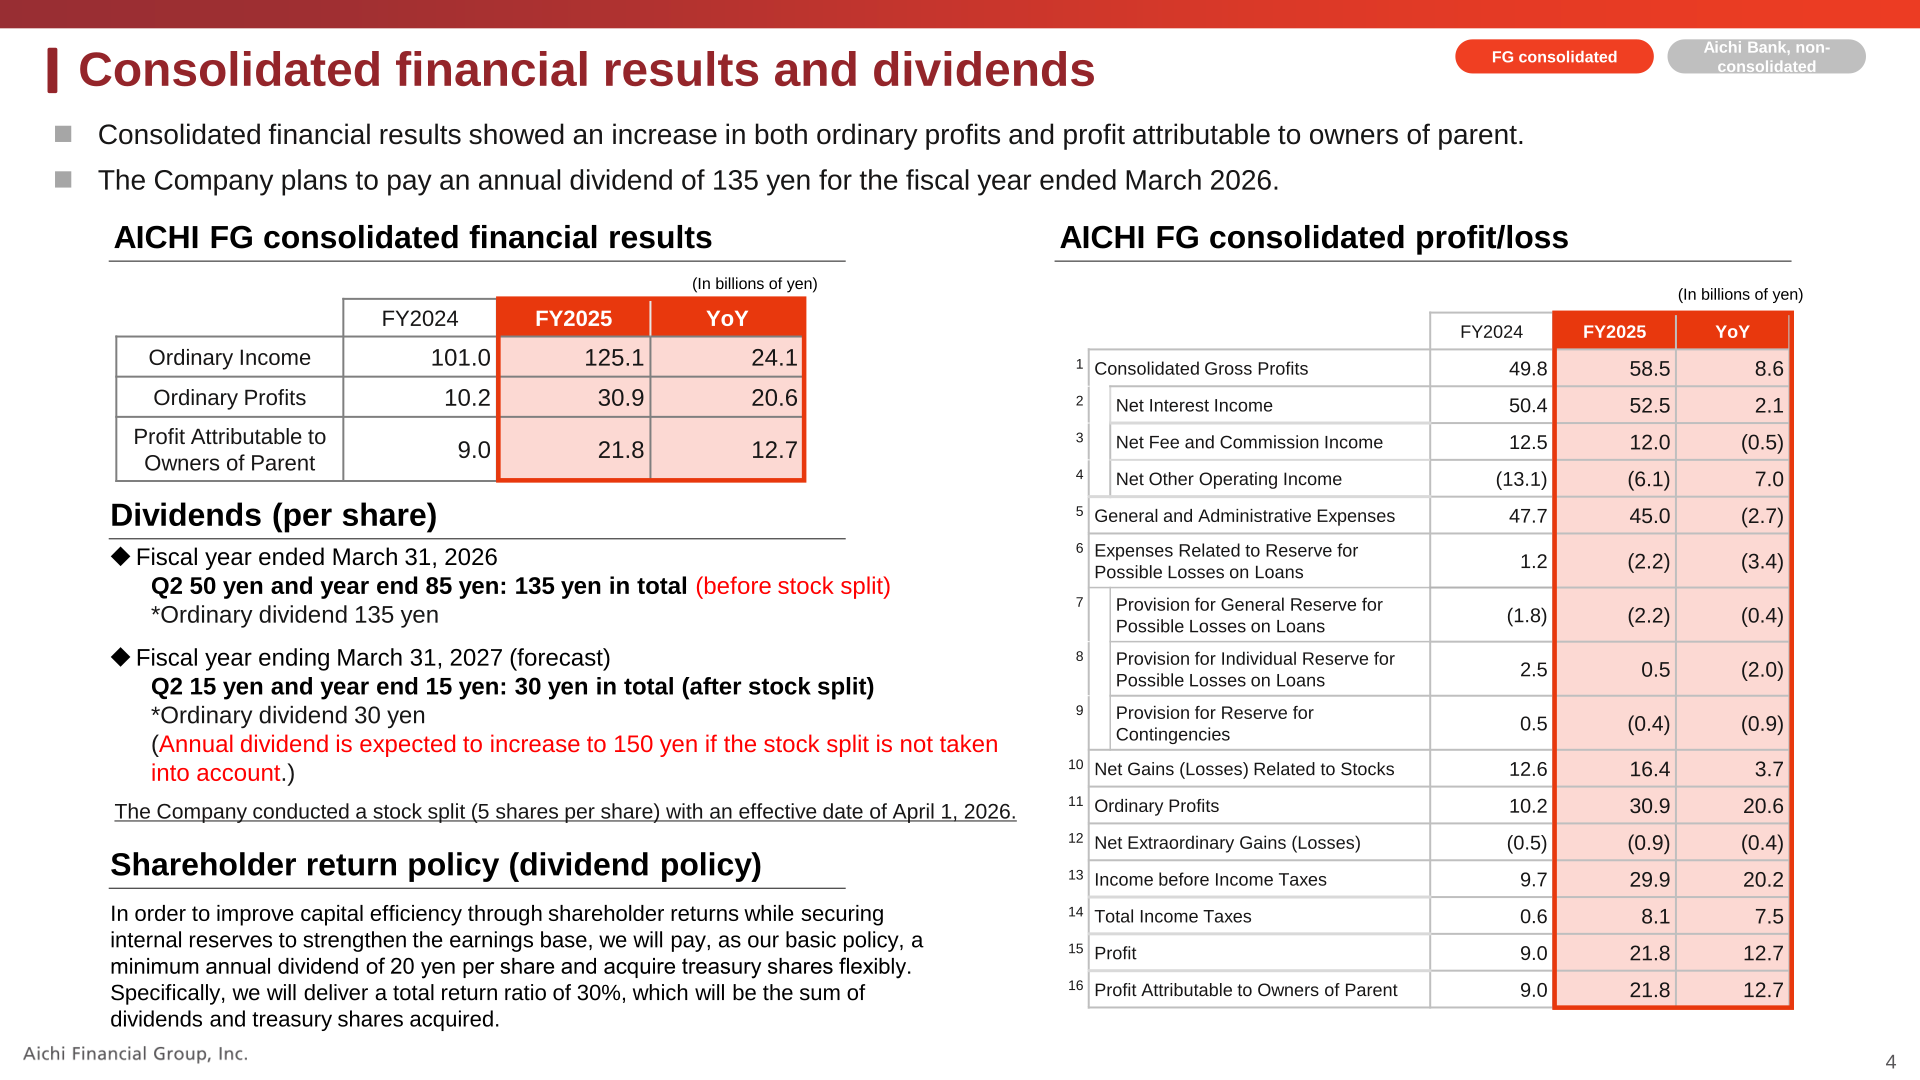
At Aichi Bank on a non-consolidated basis, net business profits before provision for the general reserve for losses on loans increased from 2.0 billion yen to 13.9 billion yen. Net interest income was 52.5 billion yen (up 2.2 billion yen), as a 12.9 billion yen increase in interest on loans and bills discounted and a 1.2 billion yen increase in interest and dividends on securities outweighed a 12.3 billion yen increase in interest on deposits. Net fee and commission income was 10.5 billion yen (down 0.8 billion yen), mainly on lower fees related to client assets, while consulting-related fees and commissions grew 0.4 billion yen. Expenses fell 4.0 billion yen to 42.1 billion yen, with non-personnel expenses down 3.6 billion yen on cost reductions from the merger and the elimination of integration-related expenses; the core OHR improved to 66.99% from 75.77%. Net gains related to stocks were 16.8 billion yen (up 3.8 billion yen), and credit-related costs were -2.4 billion yen (down 3.5 billion yen) on a reversal of reserves.
| Aichi Bank, non-consolidated (In billions of yen) | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Gross Profits | 48.2 | 56.1 | 7.9 |
| Core Gross Profits | 60.9 | 62.9 | 2.0 |
| Net Interest Income | 50.3 | 52.5 | 2.2 |
| Interest on Loans and Bills Discounted | 39.8 | 52.8 | 12.9 |
| Interest on Deposits | 5.9 | 18.2 | 12.3 |
| Net Fee and Commission Income | 11.4 | 10.5 | (0.8) |
| Expenses | 46.1 | 42.1 | (4.0) |
| Net Business Profits (before Provision for General Reserve for Losses on Loans) | 2.0 | 13.9 | 11.9 |
| Net Business Profits (before Provision for General Reserve for Losses on Loans) from Core Business Area | 14.7 | 20.7 | 6.0 |
| Net Gains (Losses) Related to Bonds | (12.7) | (6.7) | 5.9 |
| Net Gains (Losses) Related to Stocks | 13.0 | 16.8 | 3.8 |
| Ordinary Profits | 10.3 | 30.7 | 20.3 |
| Profit | 9.6 | 21.4 | 11.8 |
| Credit-Related Costs | 1.1 | (2.4) | (3.5) |
Deposits, Loans and Asset Quality
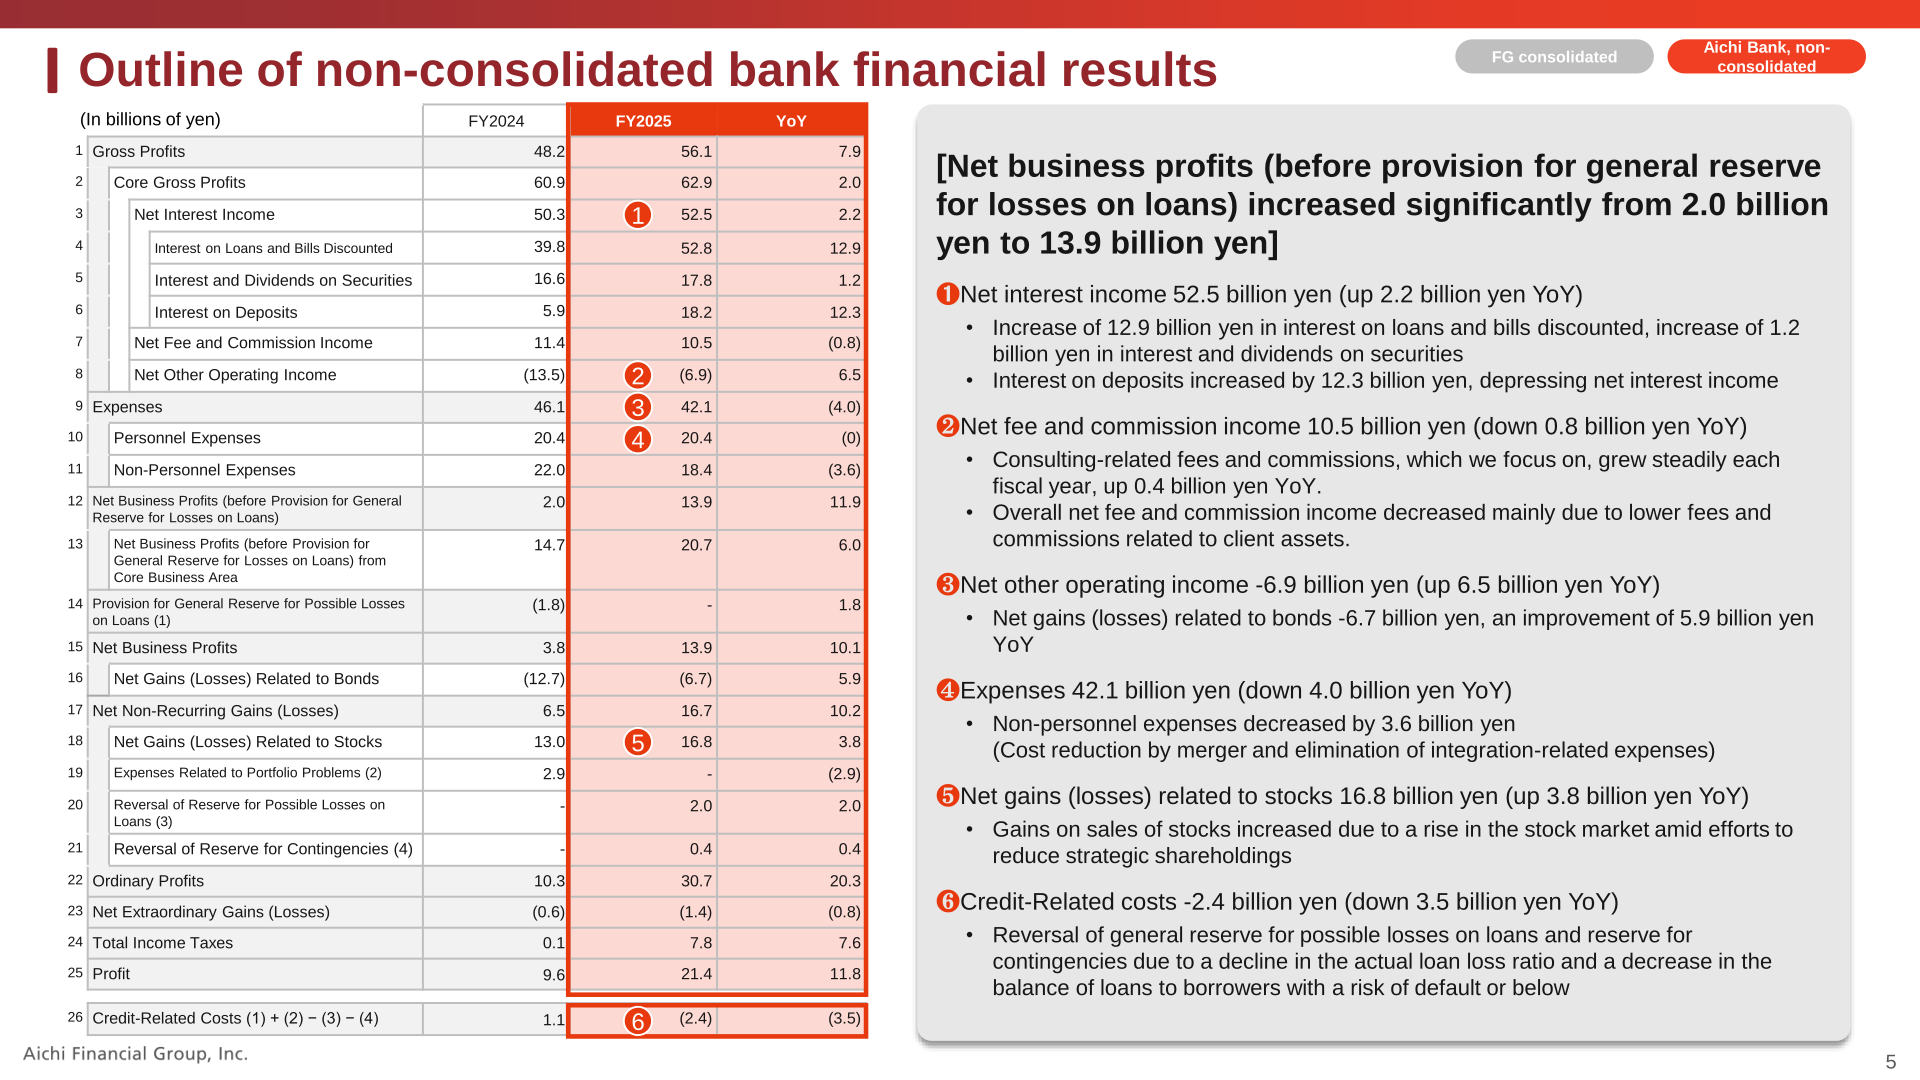
Total deposits at Aichi Bank reached 6,004.4 billion yen as of March 31, 2026, from 5,945.7 billion yen a year earlier, while total loans and bills discounted rose to 4,953.1 billion yen from 4,854.7 billion yen. Loans to SMEs were 3,959.1 billion yen and consumer loans 1,501.8 billion yen. Housing loans accounted for 29.4% of total loans and bills discounted, of which approximately 96% carry floating rates. The yield on loans and bills discounted rose to 1.07% in FY2025 from 0.82% in FY2024, while the cost of deposits rose to 0.30% from 0.10%. The non-performing loan ratio improved to 1.62% from 1.80%, with non-performing loans of 81.4 billion yen. Securities balances were 1,270.7 billion yen and total net unrealized gains on securities were 137.5 billion yen, up 68.3 billion yen.
Consulting and Solution Income
Consulting-related fees and commissions for the entire Aichi FG were 2,432 million yen in FY2025, comprising 1,978 million yen at Aichi Bank and 454 million yen at group companies, against 1,531 million yen for the entire group in FY2024. Within FY2025, business matching contributed 750 million yen (up 45 million yen), M&A and business succession 452 million yen, consulting 592 million yen (up 411 million yen), business insurance 184 million yen (up 49 million yen), Sakaemachi Research & Consulting 274 million yen, Aichi FG Marketing 90 million yen and AAST 90 million yen. The balance of investment trusts at Aichi Bank was 208.0 billion yen, up from 175.7 billion yen in FY2024.
FY2026 Forecast
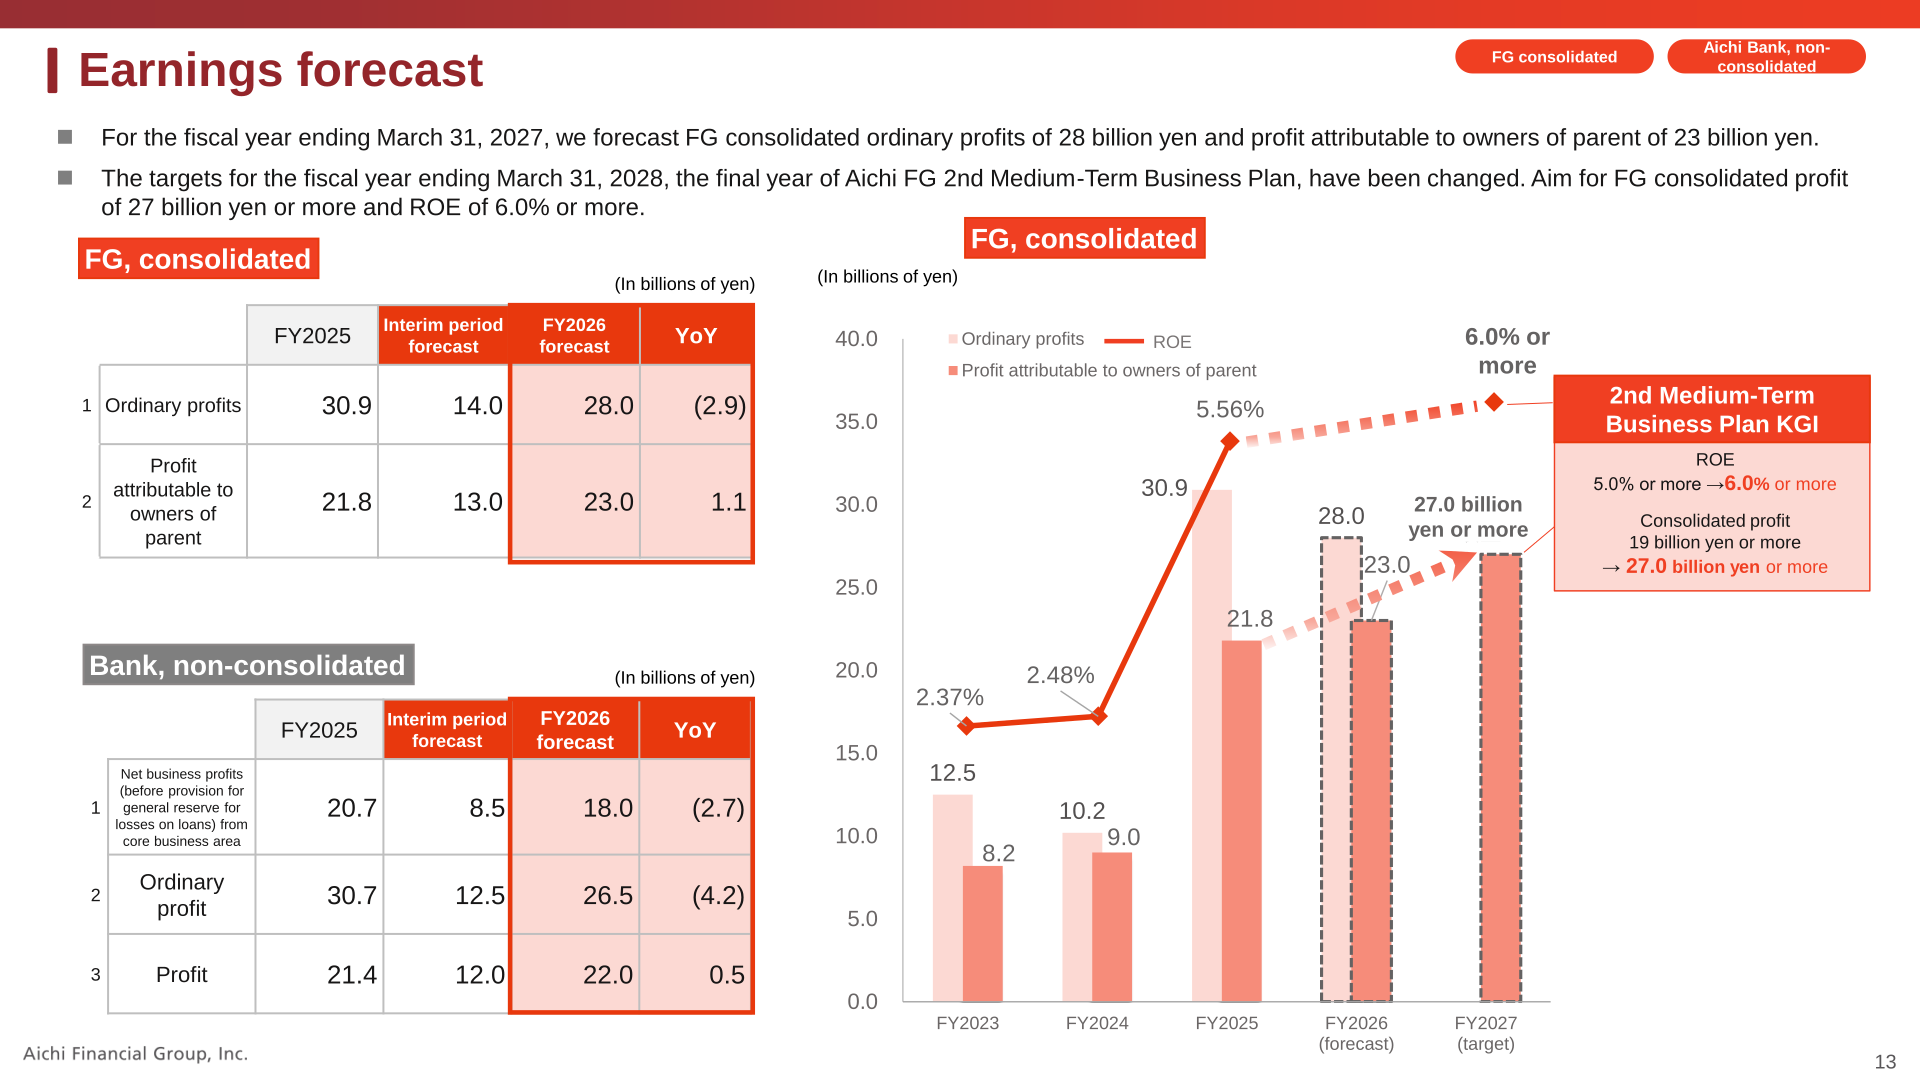
For the fiscal year ending March 31, 2027, the company forecasts FG consolidated ordinary profits of 28.0 billion yen and profit attributable to owners of parent of 23.0 billion yen, with an interim-period forecast of 14.0 billion yen and 13.0 billion yen respectively. On a bank non-consolidated basis, net business profits from the core business area are forecast at 18.0 billion yen, ordinary profit at 26.5 billion yen and profit at 22.0 billion yen.
| Item (In billions of yen) | FY2025 | Interim period forecast | FY2026 forecast | YoY |
|---|---|---|---|---|
| FG consolidated: Ordinary profits | 30.9 | 14.0 | 28.0 | (2.9) |
| FG consolidated: Profit attributable to owners of parent | 21.8 | 13.0 | 23.0 | 1.1 |
| Bank non-consolidated: Net business profits (before provision for general reserve for losses on loans) from core business area | 20.7 | 8.5 | 18.0 | (2.7) |
| Bank non-consolidated: Ordinary profit | 30.7 | 12.5 | 26.5 | (4.2) |
| Bank non-consolidated: Profit | 21.4 | 12.0 | 22.0 | 0.5 |
Shareholder Returns
For the fiscal year ended March 31, 2026 the company plans an annual dividend of 135 yen per share before the stock split, consisting of 50 yen at the second quarter and 85 yen at year end. A five-for-one stock split took effect on April 1, 2026. For the fiscal year ending March 31, 2027 the forecast annual dividend is 30 yen per share after the split (15 yen at the second quarter and 15 yen at year end), equivalent to 150 yen per share before the split. Under its shareholder return policy, the company sets a minimum annual dividend of 20 yen per share, acquires treasury shares flexibly, and targets a total return ratio of 30% covering dividends and treasury share acquisitions; the capital policy slide envisages a total shareholder return ratio of around 30%.
| Dividend per share | FY2025 (ended March 31, 2026) | FY2026 forecast (ending March 31, 2027) |
|---|---|---|
| Q2 | 50 yen | 15 yen |
| Year end | 85 yen | 15 yen |
| Annual total | 135 yen (before stock split) | 30 yen (after stock split) |
Reduction of Strategic Shareholdings
In the fiscal year ended March 31, 2026, listed strategic shareholdings were reduced by 13 issues to 92 issues, with the bank book value down 4.6 billion yen to 24.1 billion yen and sales totaling 13.9 billion yen. The FG book value fell 5.0 billion yen to 33.4 billion yen, while the market value rose 13.5 billion yen to 101.0 billion yen partly on a rise in the stock market, equal to 23.4% of FG net assets of 431.0 billion yen. The company aims to reduce strategic shareholdings to less than 20% of consolidated net assets on a market-value basis by the end of FY2028 (March 31, 2029), and to direct the cash generated to human capital investment, DX investment, group strategy investment, equity capital and shareholder returns.
Business Integration with San ju San Financial Group
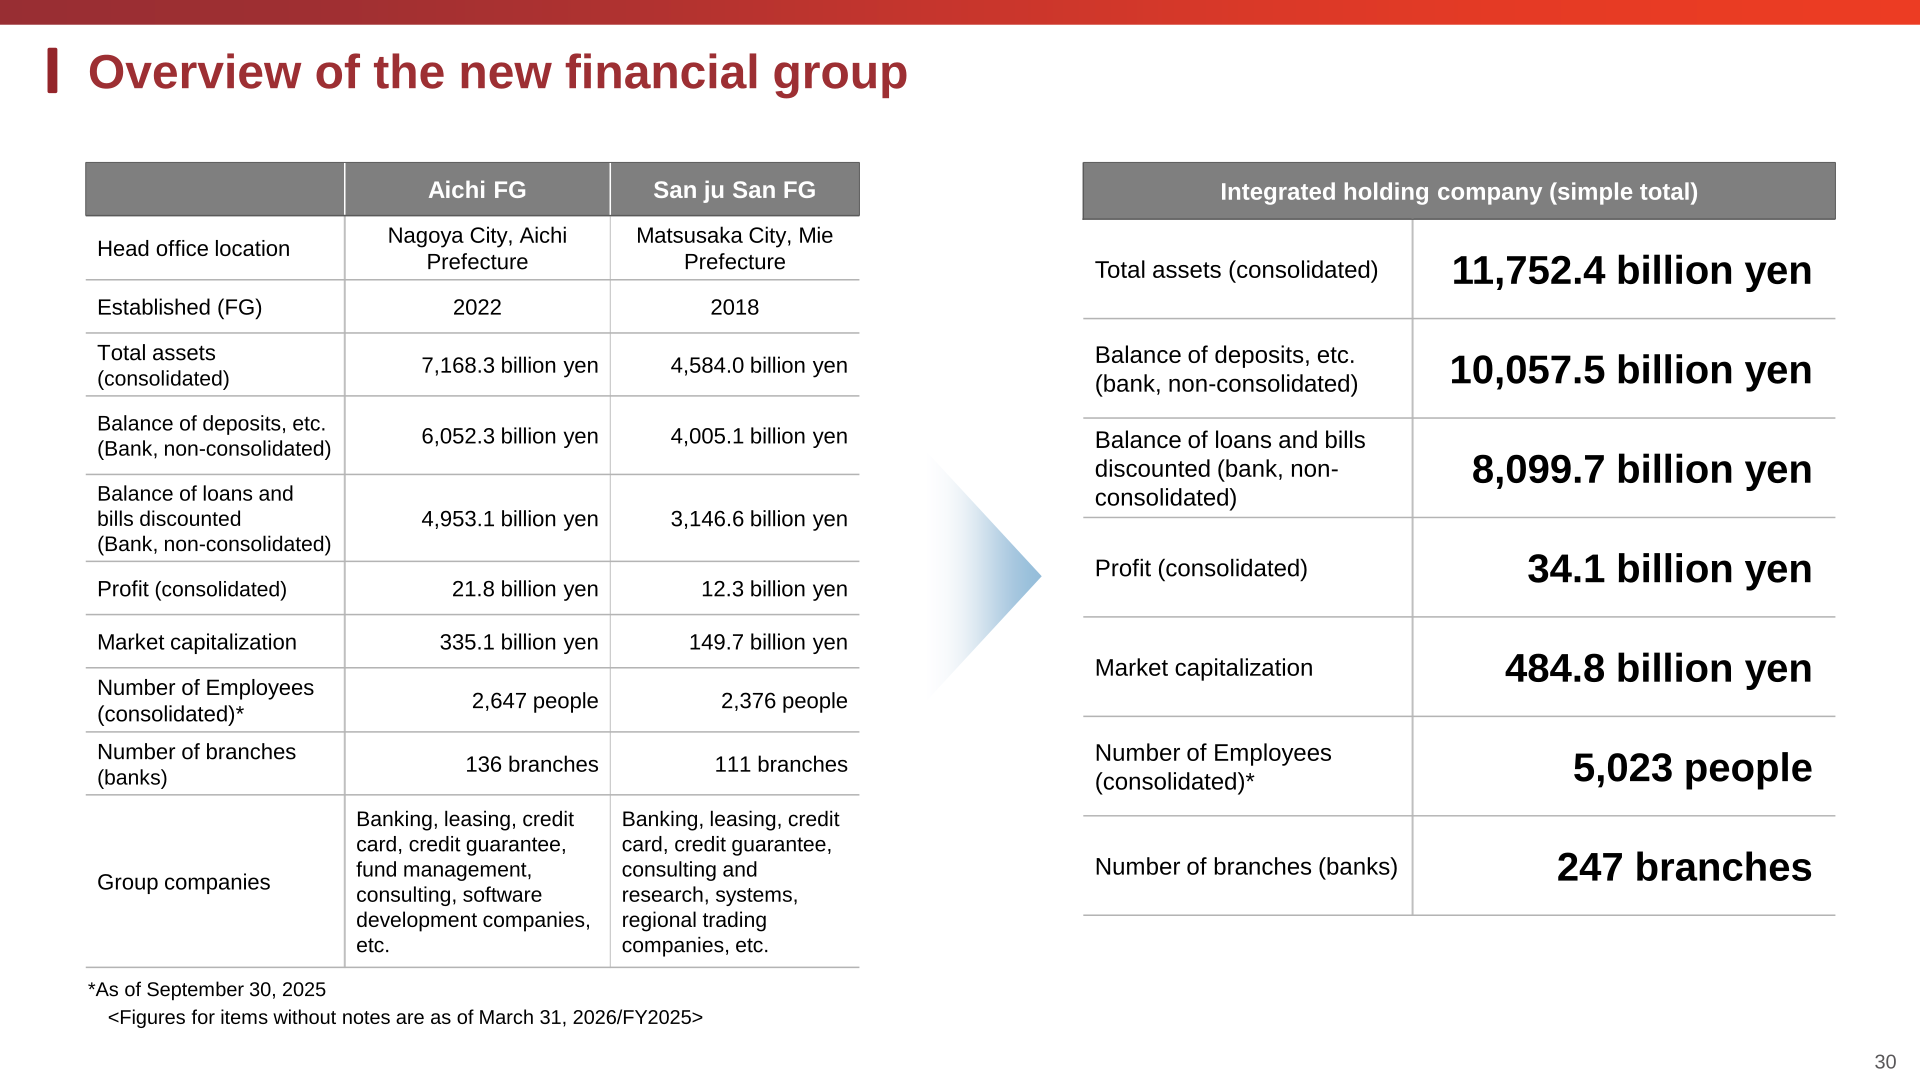
On May 13, 2026 the company concluded a basic agreement on a business integration with San ju San Financial Group, to be implemented through an absorption-type merger between the two bank holding companies; the surviving and disappearing companies have not yet been determined. The schedule calls for a final agreement and merger agreement in September 2026, extraordinary general meetings of shareholders of both companies in December 2026, and an effective date of April 1, 2027, subject to approvals. Both banks will retain their names under a two-brand structure, and the combined branch network would cover Tokyo, Osaka and six prefectures.
| Item | Aichi FG | San ju San FG | Simple total |
|---|---|---|---|
| Head office location | Nagoya City, Aichi Prefecture | Matsusaka City, Mie Prefecture | – |
| Total assets (consolidated) | 7,168.3 billion yen | 4,584.0 billion yen | 11,752.4 billion yen |
| Balance of deposits, etc. (bank, non-consolidated) | 6,052.3 billion yen | 4,005.1 billion yen | 10,057.5 billion yen |
| Balance of loans and bills discounted (bank, non-consolidated) | 4,953.1 billion yen | 3,146.6 billion yen | 8,099.7 billion yen |
| Profit (consolidated) | 21.8 billion yen | 12.3 billion yen | 34.1 billion yen |
| Market capitalization | 335.1 billion yen | 149.7 billion yen | 484.8 billion yen |
| Number of employees (consolidated) | 2,647 people | 2,376 people | 5,023 people |
| Number of branches (banks) | 136 branches | 111 branches | 247 branches |
2nd Medium-Term Business Plan
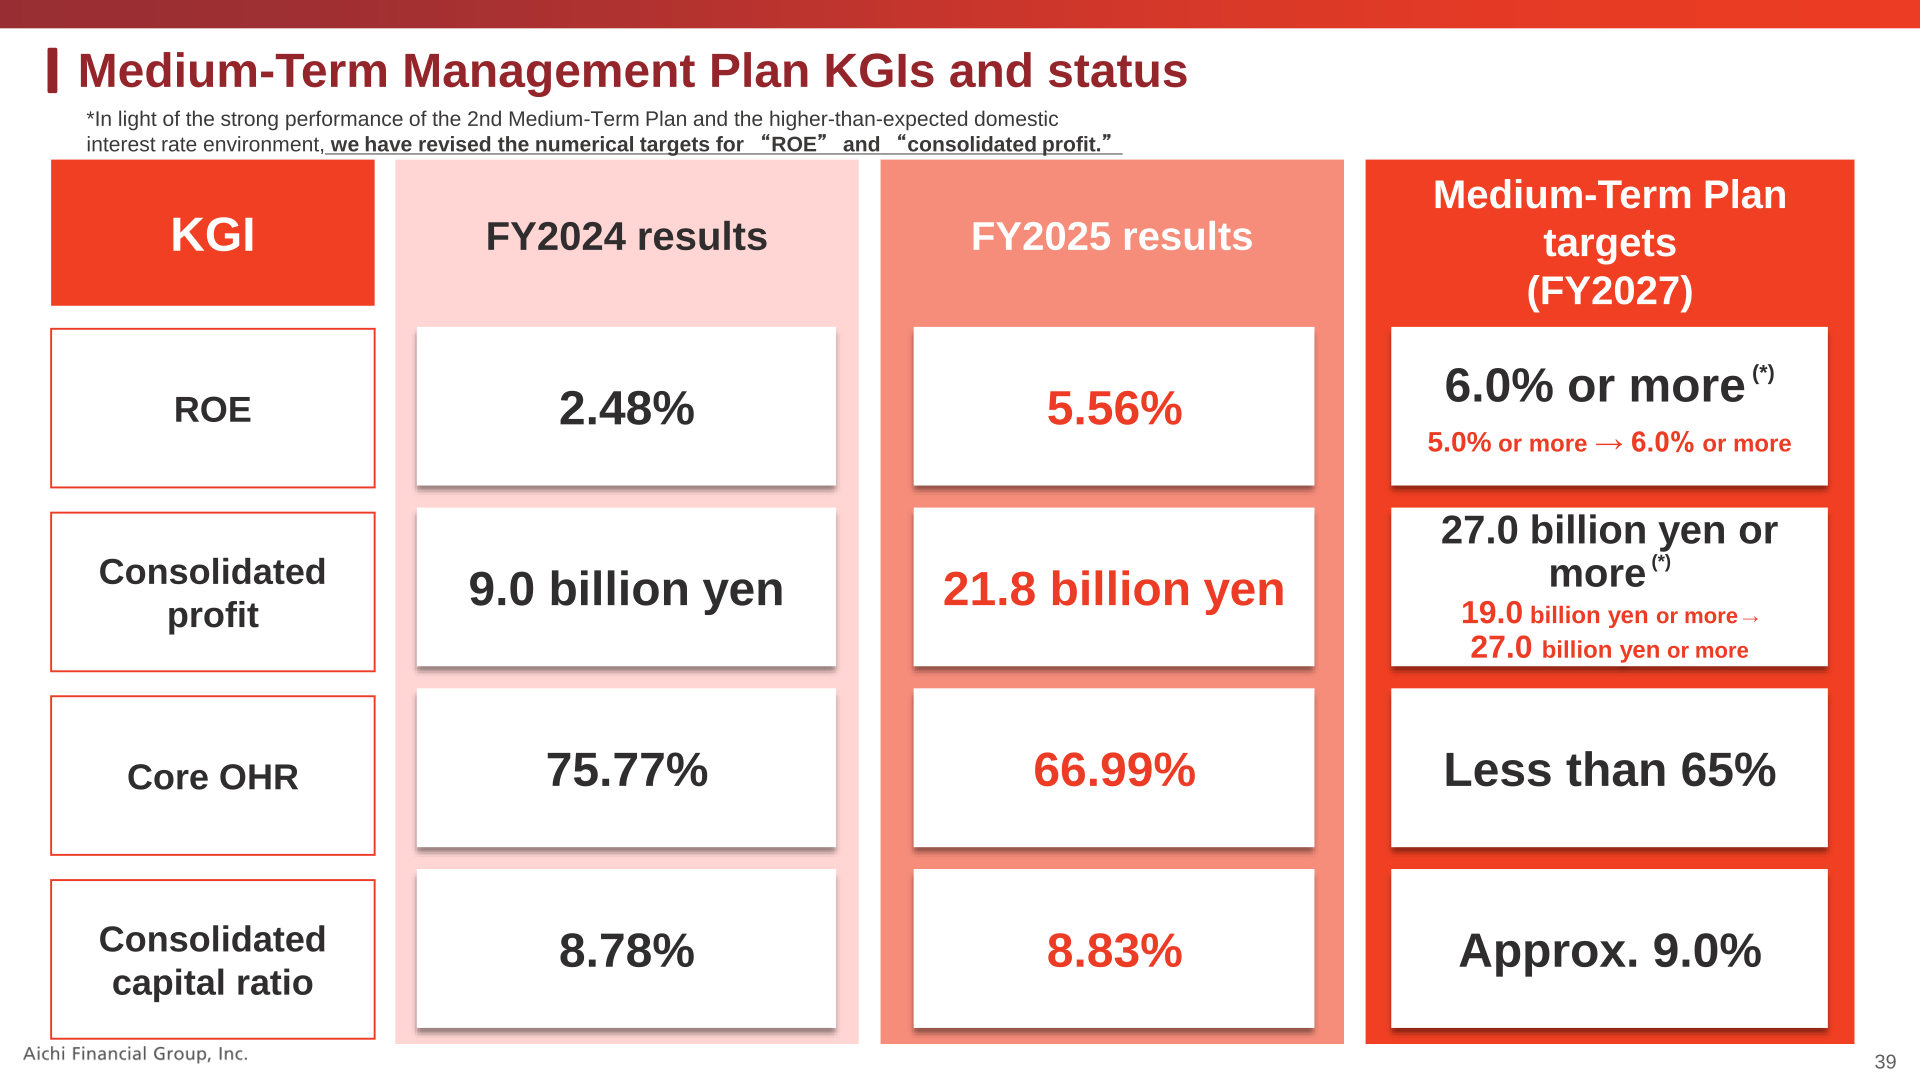
Citing strong performance under the 2nd Medium-Term Business Plan and a higher-than-expected domestic interest rate environment, the company revised its numerical targets for ROE and consolidated profit for FY2027, the final year of the plan. The ROE target was raised from 5.0% or more to 6.0% or more, and consolidated profit from 19.0 billion yen or more to 27.0 billion yen or more. Targets for the core OHR (less than 65%) and the consolidated capital ratio (approximately 9.0%) are unchanged. Over the longer term, the group aims for an FG consolidated own capital ratio of approximately 9.5% at the end of March 2031, the final year of the 3rd Medium-Term Business Plan, and recognizes a cost of shareholders’ equity of around 6-9%.
| KGI | FY2024 results | FY2025 results | Medium-Term Plan targets (FY2027) |
|---|---|---|---|
| ROE | 2.48% | 5.56% | 6.0% or more (revised from 5.0% or more) |
| Consolidated profit | 9.0 billion yen | 21.8 billion yen | 27.0 billion yen or more (revised from 19.0 billion yen or more) |
| Core OHR | 75.77% | 66.99% | Less than 65% |
| Consolidated capital ratio | 8.78% | 8.83% | Approx. 9.0% |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















