
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
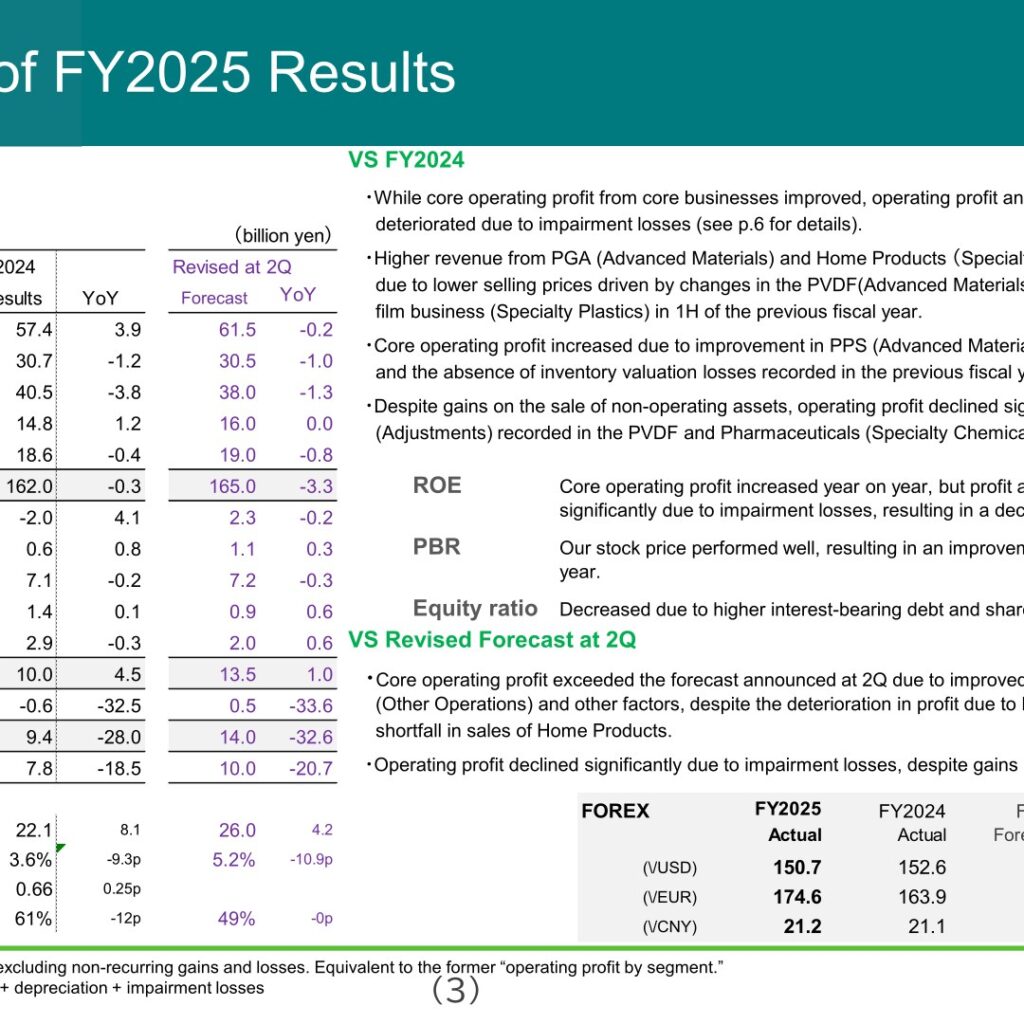
Kureha Corporation, a chemical manufacturer operating in Advanced Materials, Specialty Chemicals, Specialty Plastics, Construction and Other Operations, reported FY2025 (fiscal year ended March 31, 2026) revenue of 161.7 billion yen (FY2024: 162.0 billion yen) and core operating profit of 14.5 billion yen (FY2024: 10.0 billion yen). However, impairment losses of ¥36.5 billion on PVDF and KREMEZIN manufacturing facilities resulted in an operating loss of -18.6 billion yen and a loss attributable to owners of parent of -10.7 billion yen. For FY2026, the company forecasts revenue of 172.0 billion yen, core operating profit of 10.0 billion yen and operating profit of 11.0 billion yen, and it plans an annual dividend of 216.0 yen per share after 214.0 yen for FY2025.
Consolidated Results (FY2025 Actual)
According to the company, core operating profit (operating profit excluding non-recurring gains and losses) increased due to improvement in PPS (Advanced Materials) profit, including equity method earnings, and the absence of inventory valuation losses recorded in the previous fiscal year for PVDF. Revenue remained flat overall: revenue rose in PGA (Advanced Materials) and Home Products (Specialty Plastics), but this was offset by lower selling prices driven by changes in the PVDF sales mix and the withdrawal from the ML film business (Specialty Plastics) in 1H of the previous fiscal year. Despite gains on the sale of non-operating assets, operating profit declined significantly due to impairment losses recorded in the PVDF and Pharmaceuticals (Specialty Chemicals) businesses.
Against the forecast revised at 2Q, core operating profit of 14.5 billion yen exceeded the 13.5 billion yen forecast, which the company attributes to improved profitability in Environment Engineering (Other Operations) and other factors, despite the deterioration in profit due to PGA resin production problems and the shortfall in sales of Home Products. ROE declined to -5.7% from 3.6%, while PBR improved to 0.91 from 0.66 on the back of stock price performance. The equity ratio fell to 49% from 61%, which the company attributes to higher interest-bearing debt and share buybacks.
| Item (billion yen) | FY2025 Results | FY2024 Results | YoY | FY2025 Forecast (Revised at 2Q) |
|---|---|---|---|---|
| Revenue | 161.7 | 162.0 | -0.3 | 165.0 |
| Core operating profit | 14.5 | 10.0 | 4.5 | 13.5 |
| Operating profit | -18.6 | 9.4 | -28.0 | 14.0 |
| Profit attributable to owners of parent | -10.7 | 7.8 | -18.5 | 10.0 |
| EBITDA | 30.2 | 22.1 | 8.1 | 26.0 |
| ROE | -5.7% | 3.6% | -9.3p | 5.2% |
| PBR | 0.91 | 0.66 | 0.25p | ― |
| Equity ratio | 49% | 61% | -12p | 49% |
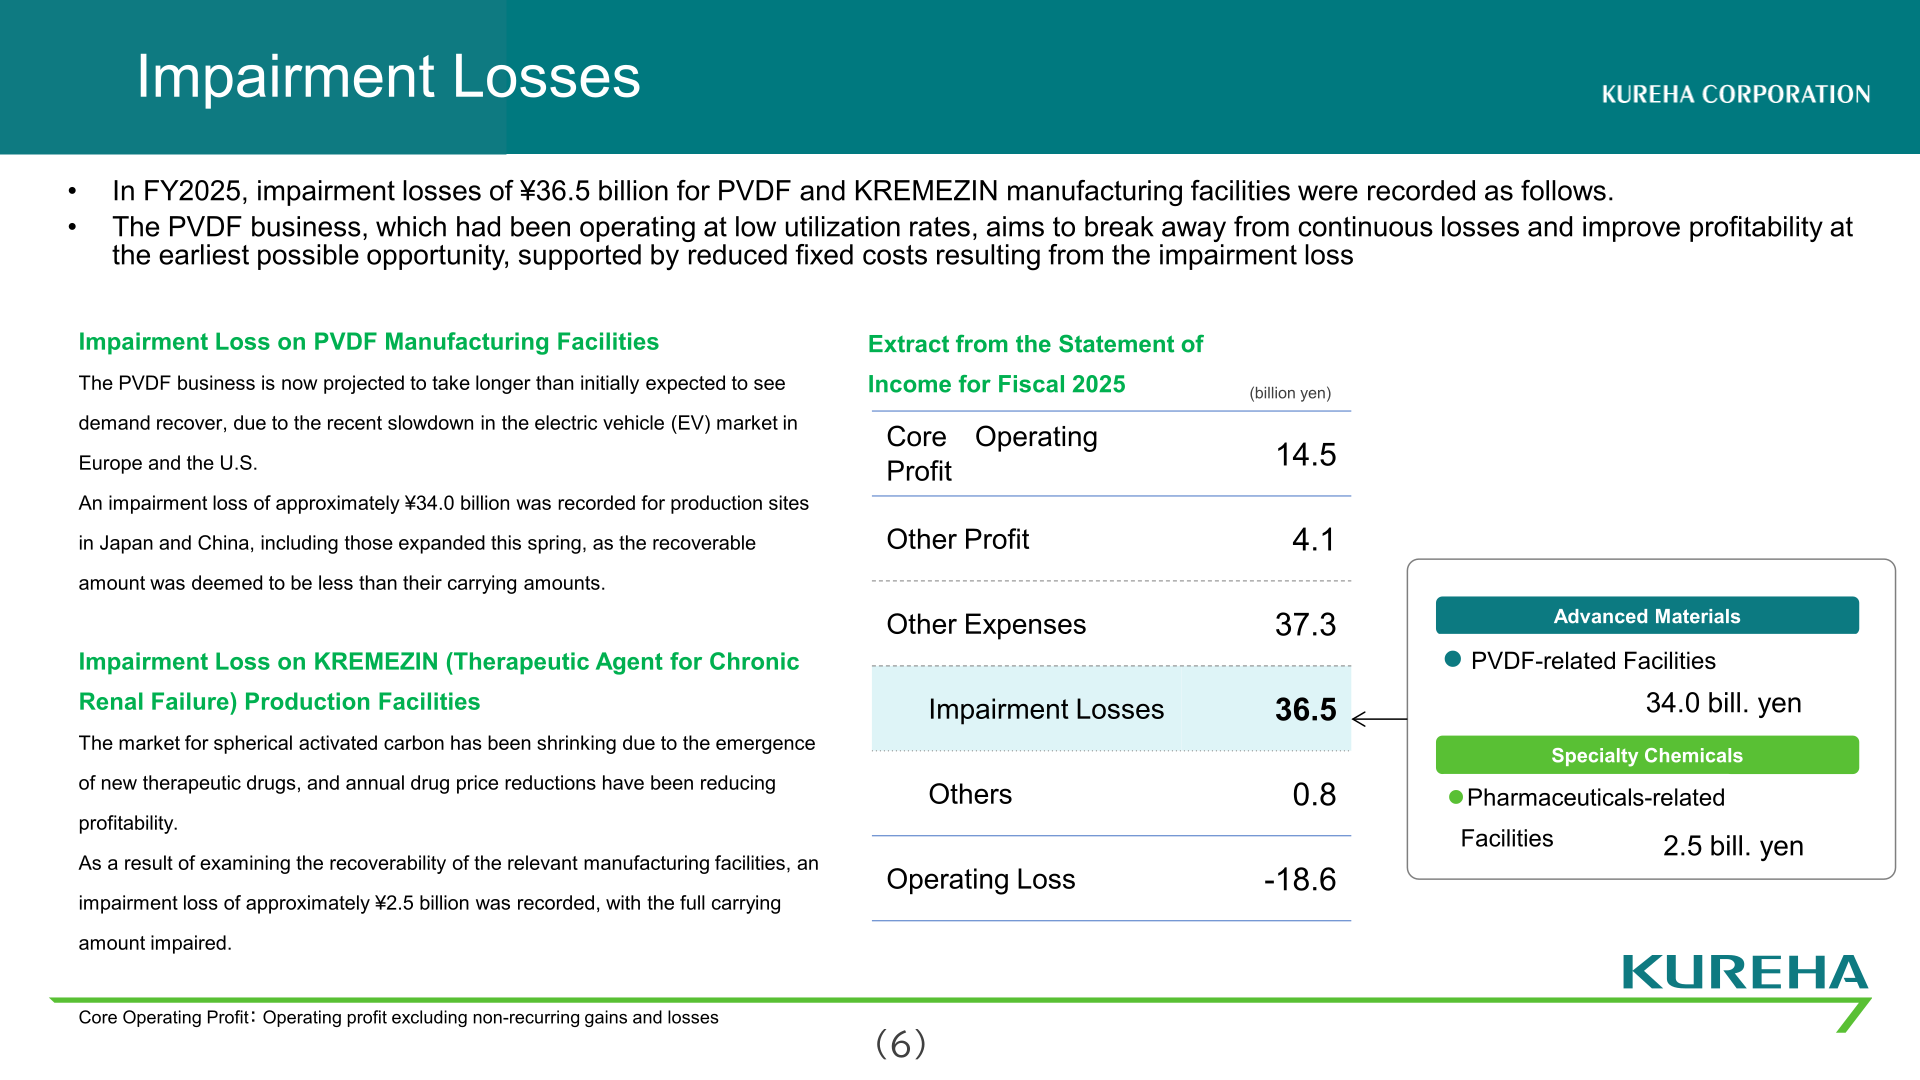
The company recorded impairment losses of ¥36.5 billion in FY2025. For PVDF, the business is now projected to take longer than initially expected to see demand recover due to the recent slowdown in the electric vehicle (EV) market in Europe and the U.S., and an impairment loss of approximately ¥34.0 billion was recorded for production sites in Japan and China, including those expanded this spring. For KREMEZIN (a therapeutic agent for chronic renal failure), the market for spherical activated carbon has been shrinking due to the emergence of new therapeutic drugs, and annual drug price reductions have been reducing profitability; an impairment loss of approximately ¥2.5 billion was recorded, with the full carrying amount impaired. The company states that the PVDF business aims to break away from continuous losses and improve profitability at the earliest possible opportunity, supported by reduced fixed costs resulting from the impairment loss.
Cash flow from operating activities was 28.0 billion yen (FY2024: 29.5 billion yen), cash flow from investing activities was -13.7 billion yen (FY2024: -39.4 billion yen), and free cash flow was 14.3 billion yen (FY2024: -9.9 billion yen). At March 31, 2026, total assets were 338.4 billion yen (March 31, 2025: 345.3 billion yen), interest-bearing debt was 124.2 billion yen (86.0 billion yen) and total equity was 167.2 billion yen (211.1 billion yen).
Segment Results
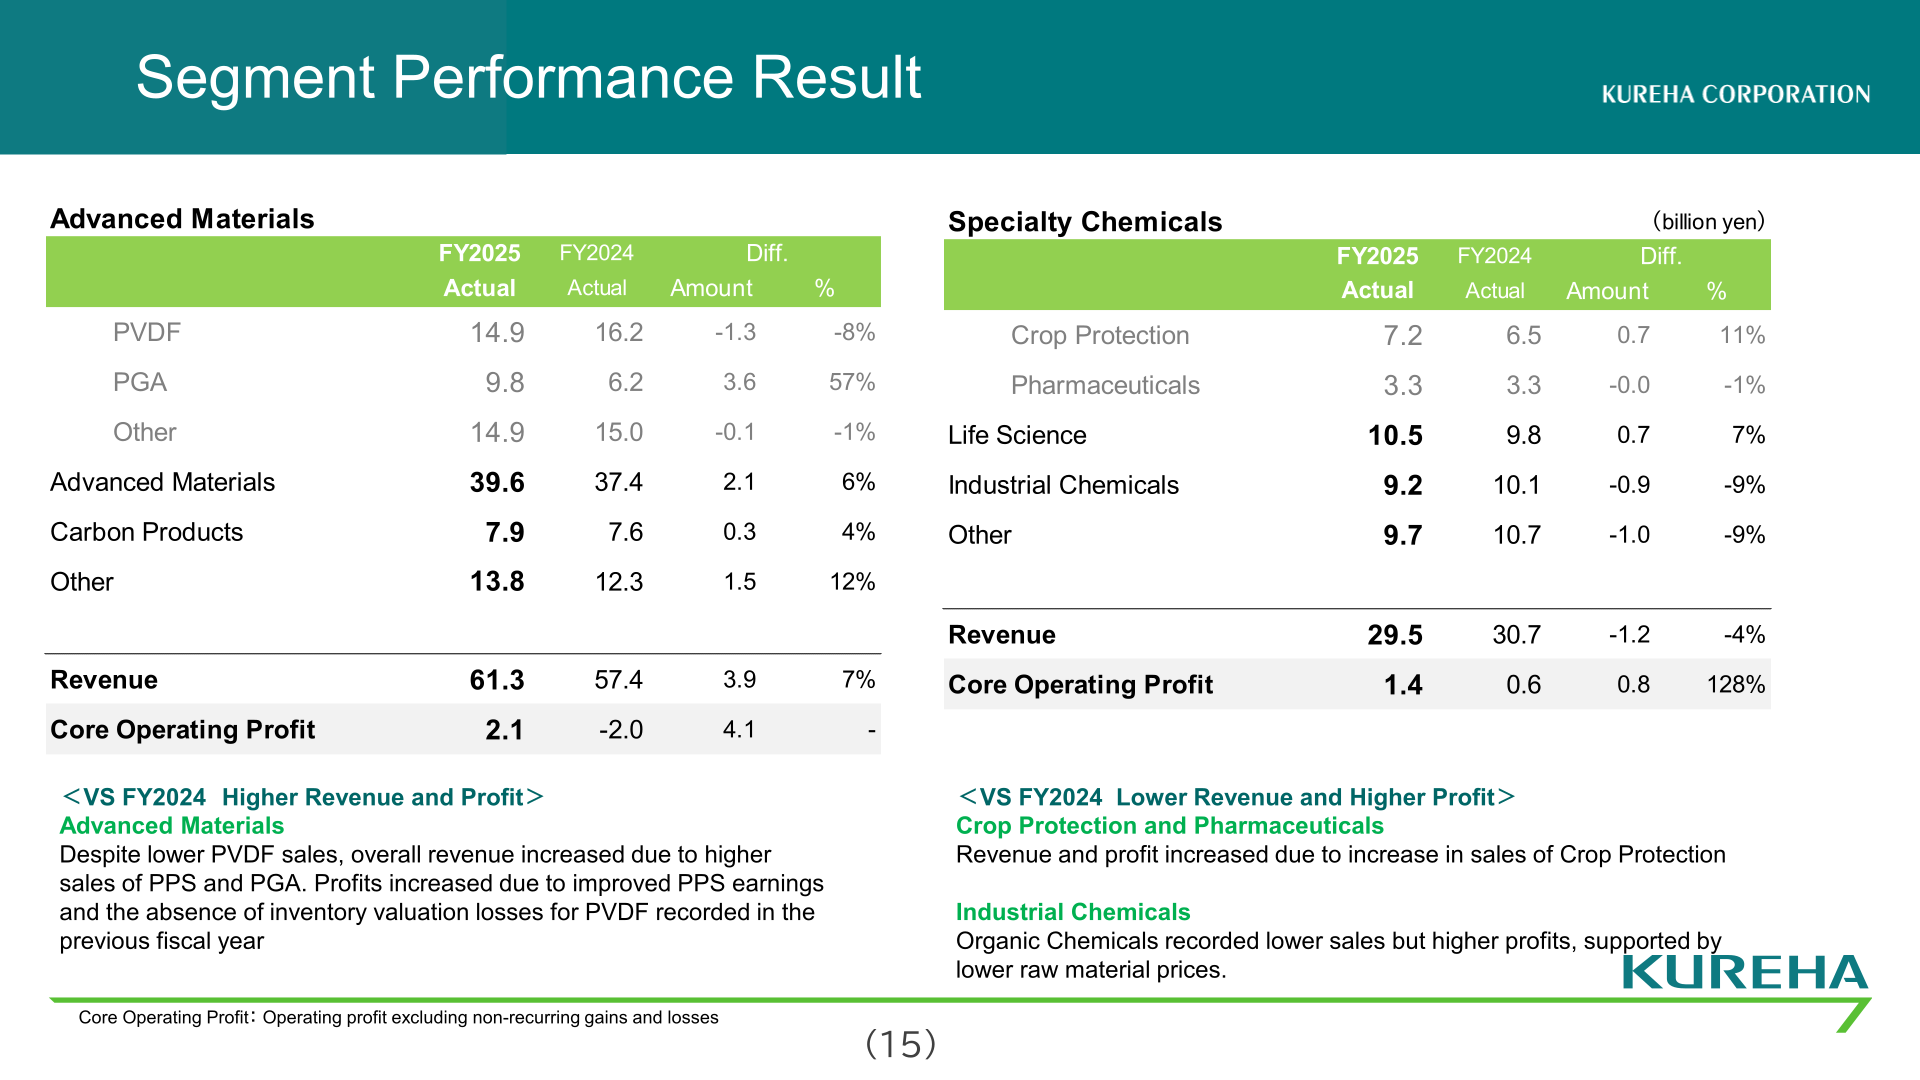
Advanced Materials posted higher revenue and profit: despite lower PVDF sales, revenue increased due to higher sales of PPS and PGA, and the segment returned to a core operating profit of 2.1 billion yen from -2.0 billion yen. PVDF revenue was 14.9 billion yen (FY2024: 16.2 billion yen) and PGA revenue was 9.8 billion yen (6.2 billion yen). In Specialty Chemicals, revenue and profit of Crop Protection and Pharmaceuticals increased due to higher Crop Protection sales, while in Industrial Chemicals, Organic Chemicals recorded lower sales but higher profits, supported by lower raw material prices. In Specialty Plastics, Home Products and Fishing Lines grew on sales of NEW Krewrap, household wraps and the Seaguar fishing lines, but Packaging Materials revenue fell to 3.9 billion yen from 9.1 billion yen owing to the end of sales of heat-shrinkable multilayer film (ML film) in 1H of the previous fiscal year.
| Segment (billion yen) | Metric | FY2025 | FY2024 | YoY |
|---|---|---|---|---|
| Advanced Materials | Revenue | 61.3 | 57.4 | 3.9 |
| Advanced Materials | Core operating profit | 2.1 | -2.0 | 4.1 |
| Specialty Chemicals | Revenue | 29.5 | 30.7 | -1.2 |
| Specialty Chemicals | Core operating profit | 1.4 | 0.6 | 0.8 |
| Specialty Plastics | Revenue | 36.7 | 40.5 | -3.8 |
| Specialty Plastics | Core operating profit | 6.9 | 7.1 | -0.2 |
| Construction | Revenue | 16.0 | 14.8 | 1.2 |
| Construction | Core operating profit | 1.5 | 1.4 | 0.1 |
| Other Operations | Revenue | 18.2 | 18.6 | -0.4 |
| Other Operations | Core operating profit | 2.6 | 2.9 | -0.3 |
FY2026 Forecast
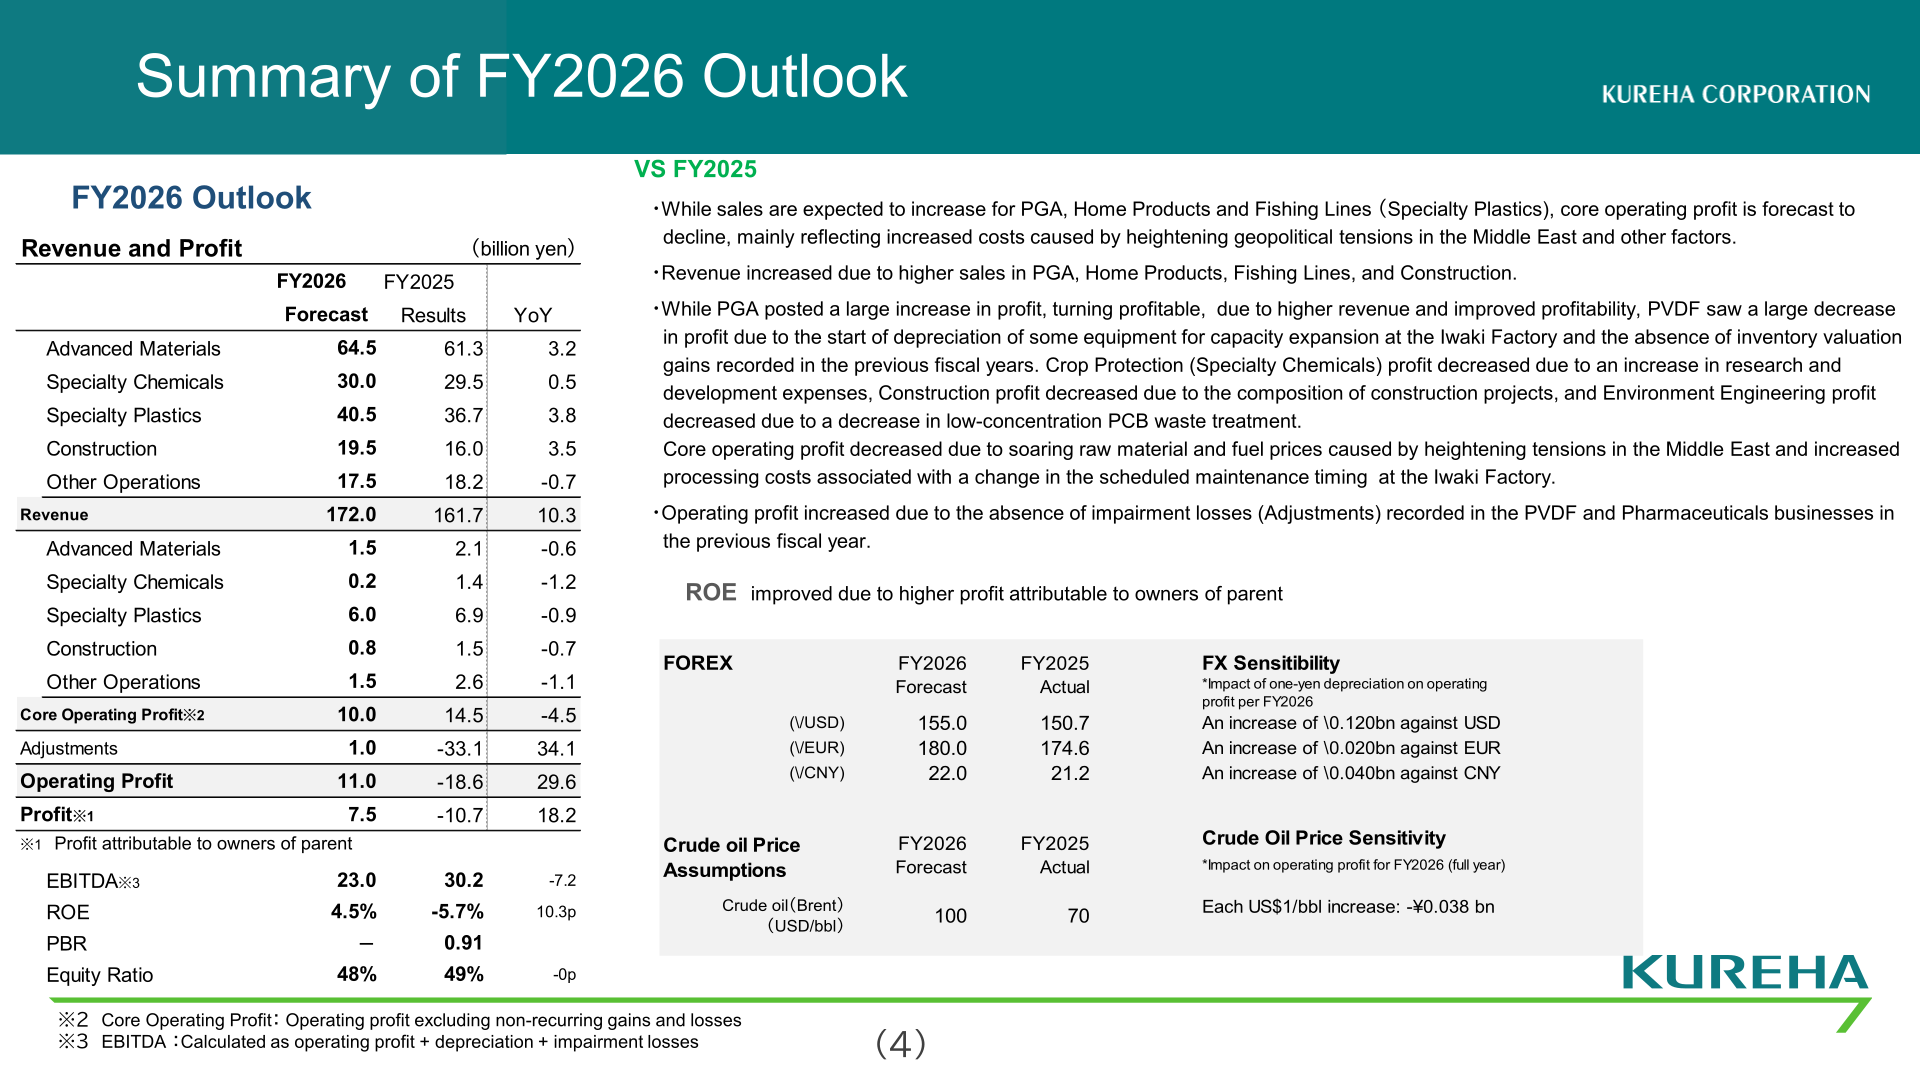
For FY2026, Kureha expects revenue to increase due to higher sales in PGA, Home Products, Fishing Lines and Construction, while core operating profit is forecast to decline, mainly reflecting soaring raw material and fuel prices caused by heightening tensions in the Middle East and increased processing costs associated with a change in the scheduled maintenance timing at the Iwaki Factory. PGA is expected to post a large increase in profit and turn profitable, while PVDF is expected to see a large decrease in profit due to the start of depreciation of some equipment for capacity expansion at the Iwaki Factory and the absence of inventory valuation gains recorded in the previous fiscal years. Operating profit is forecast to increase due to the absence of the impairment losses recorded in FY2025. The forecast assumes an exchange rate of 155.0 yen/USD and a Brent crude oil price of US$100/bbl; the company estimates that each ¥1 depreciation against the USD increases operating profit by ¥0.120 billion, and each US$1/bbl increase in crude oil prices reduces it by ¥0.038 billion.
| Item (billion yen) | FY2026 Forecast | FY2025 Results | YoY |
|---|---|---|---|
| Revenue | 172.0 | 161.7 | 10.3 |
| Advanced Materials (core operating profit) | 1.5 | 2.1 | -0.6 |
| Specialty Chemicals (core operating profit) | 0.2 | 1.4 | -1.2 |
| Specialty Plastics (core operating profit) | 6.0 | 6.9 | -0.9 |
| Construction (core operating profit) | 0.8 | 1.5 | -0.7 |
| Other Operations (core operating profit) | 1.5 | 2.6 | -1.1 |
| Core operating profit | 10.0 | 14.5 | -4.5 |
| Operating profit | 11.0 | -18.6 | 29.6 |
| Profit attributable to owners of parent | 7.5 | -10.7 | 18.2 |
| EBITDA | 23.0 | 30.2 | -7.2 |
| ROE | 4.5% | -5.7% | 10.3p |
| Equity ratio | 48% | 49% | -0p |
Shareholder Returns
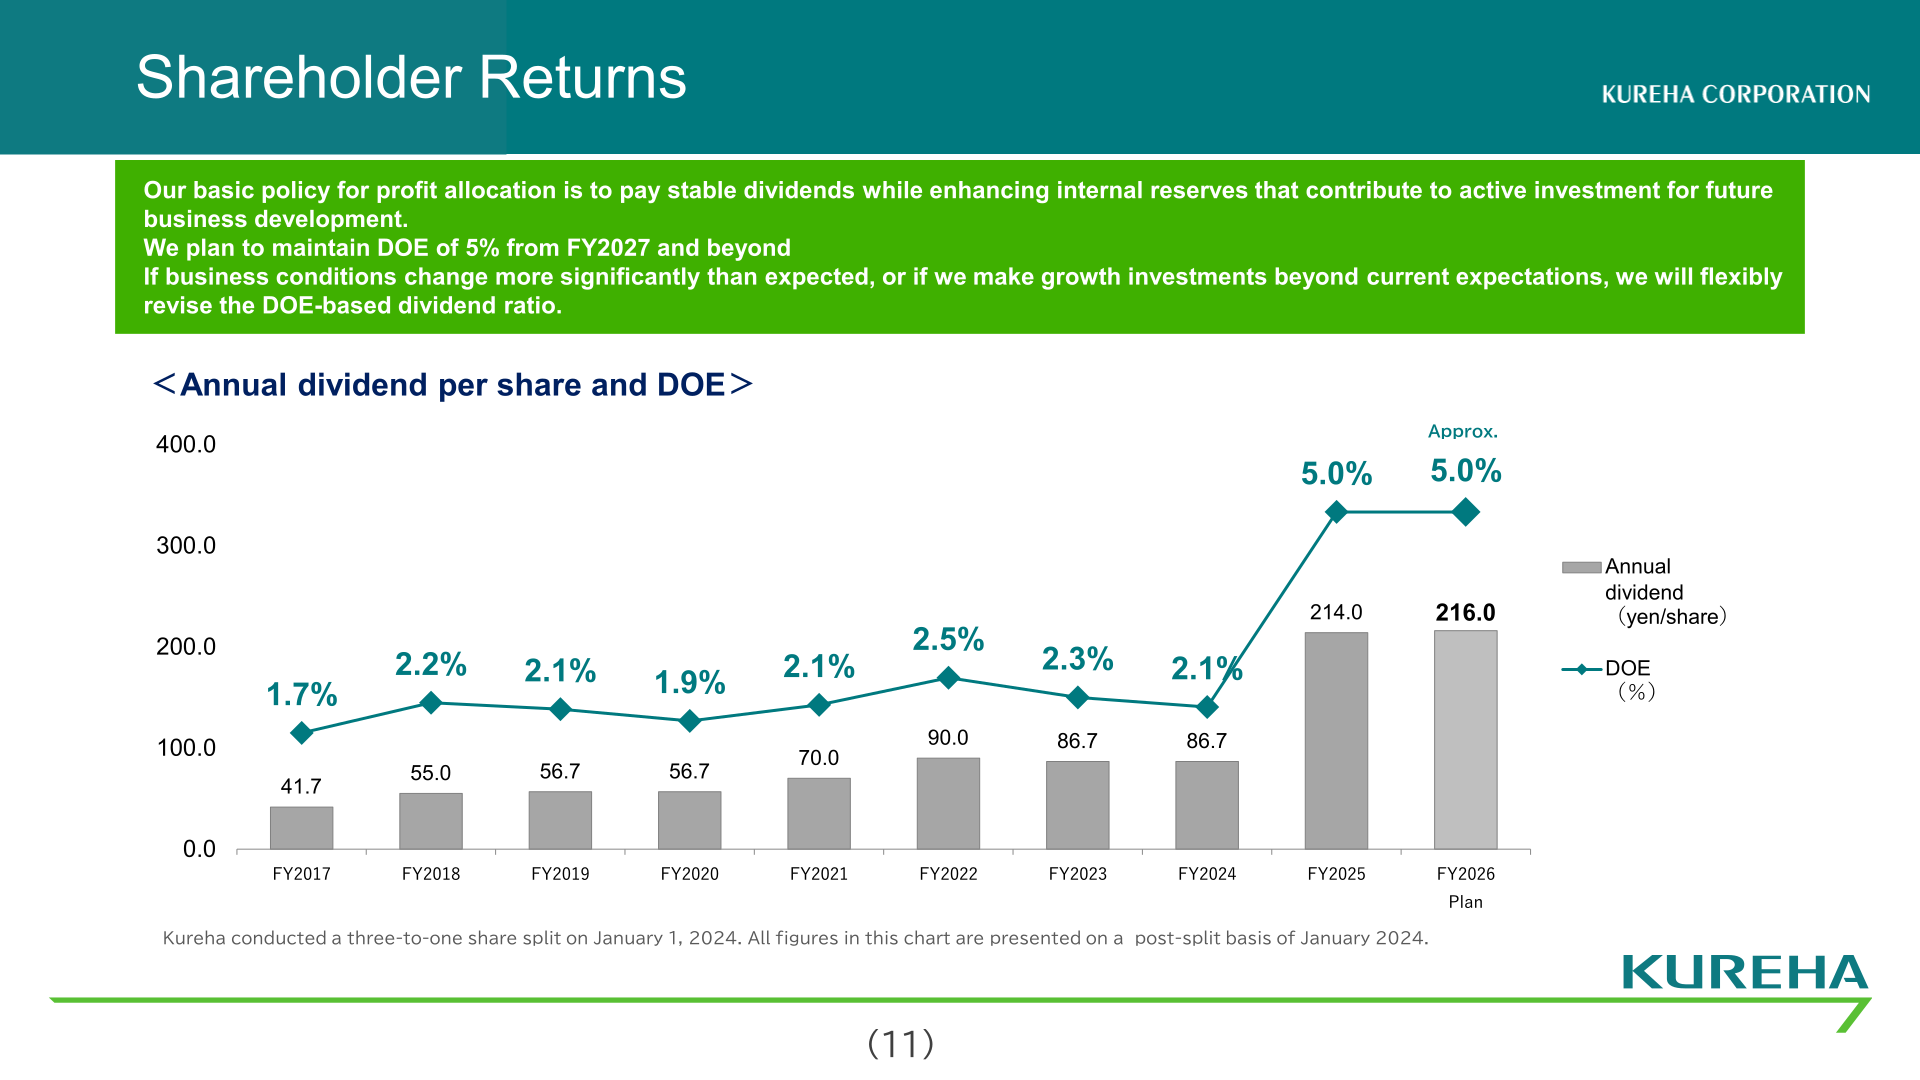
Kureha’s basic policy for profit allocation is to pay stable dividends while enhancing internal reserves that contribute to active investment for future business development. The annual dividend per share was 214.0 yen for FY2025 (DOE 5.0%), up from 86.7 yen for FY2024 (DOE 2.1%), and the FY2026 plan is 216.0 yen (DOE approx. 5.0%). The company plans to maintain DOE of 5% from FY2027 and beyond, but states that it will flexibly revise the DOE-based dividend ratio if business conditions change more significantly than expected or if it makes growth investments beyond current expectations. Figures are presented on a post-split basis reflecting the three-to-one share split on January 1, 2024.
| Item | FY2024 | FY2025 | FY2026 (Plan) |
|---|---|---|---|
| Annual dividend per share (yen) | 86.7 | 214.0 | 216.0 |
| DOE | 2.1% | 5.0% | Approx. 5.0% |
Topics: PVDF and PGA Businesses
PVDF: In FY2025, sales for ESS contributed but sales for automotive applications decreased; sales volume was in line with the previous year, but revenue decreased due to changes in the sales mix. For FY2026, sales volume is expected to increase on higher sales for ESS and expanded sales for industrial applications, with ESS expected to grow to nearly 30% of total PVDF sales volume. The capacity expansion at the Iwaki Factory was completed in April 2026, and the company plans to develop new high-value-added grades for LFP (ESS and EV applications) and new global customers, including those in China.
PGA: In FY2025, orders were restricted due to inventory shortages caused by production problems at a resin plant in the U.S., but the recovery in gas-field drilling and market share gains in oil fields resulted in record sales volume and increased revenue. Earnings declined by approximately ¥1.2 billion due to the U.S. resin plant production problems and the shortening of the regular maintenance period, and operating losses remained flat. For FY2026, the company expects to return to profitability through increased revenue, improved profitability from switching to shortened plugs (targeting a ratio of 80% in FY2026, up from 18% in FY2025), and other factors. Kureha states that it will initiate a fundamental review of the business structure if the PGA business fails to return to profitability in FY2026.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















