
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Tomoku labels the fiscal year ended March 31, 2026 as “FY3/2026” in its presentation; this site classifies it as FY2025. The body text and tables below keep the company’s own labels (FY3/2026 = year ended March 2026; FY3/2027 = year ending March 2027).
TOMOKU CO., LTD., which operates the Corrugated Container and Display Carton, Housing, and Transportation and Logistics businesses, reported FY3/2026 net sales of 224,090 million yen (+2.0% YoY) and operating profit of 11,378 million yen (+21.6% YoY), describing the year as one of higher sales and profit, with profits hitting a record high. The company attributes the result mainly to improved gross profit from price revisions in the Corrugated Container and Display Carton segment. For FY3/2027, it forecasts net sales of 220,500 million yen (-1.6%) and operating profit of 12,700 million yen (+11.6%), and plans an annual dividend of 170 yen per share, up 40 yen. The company also presented its Third Medium-Term Business Plan (FY3/2027 – FY3/2029).
Consolidated Results (Full-Year Actual)
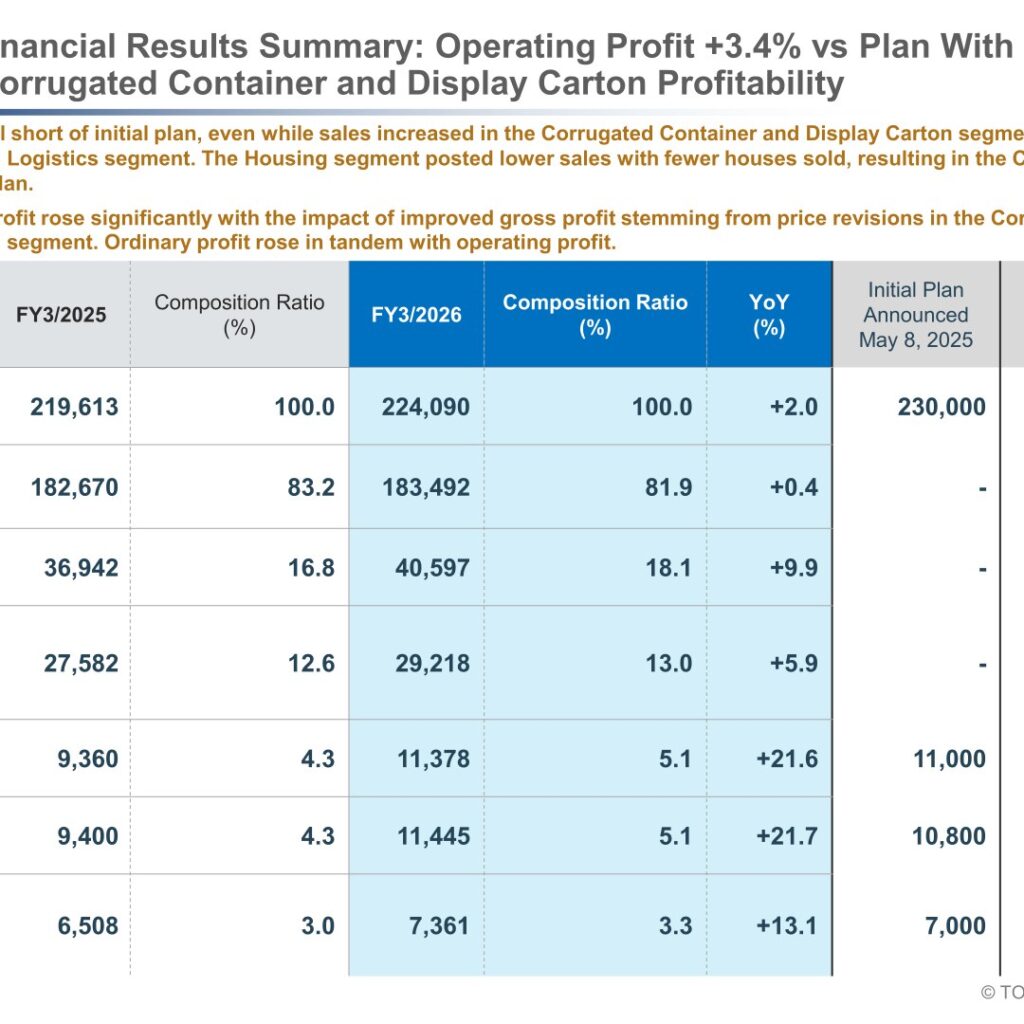
Net sales were 224,090 million yen, up 2.0% from 219,613 million yen in FY3/2025, and reached 97.4% of the initial plan of 230,000 million yen announced on May 8, 2025. According to the company, sales fell short of the initial plan even though the Corrugated Container and Display Carton and the Transportation and Logistics segments posted higher sales, as the Housing segment recorded lower sales with fewer houses sold. Gross profit rose 9.9% to 40,597 million yen, and SG&A expenses increased 5.9% to 29,218 million yen.
Operating profit rose 21.6% to 11,378 million yen (103.4% of the initial plan of 11,000 million yen), with the operating profit margin improving to 5.1% from 4.3%. The company states that profit rose significantly on improved gross profit stemming from price revisions in the Corrugated Container and Display Carton segment, where price revisions in Japan covered the decline in sales volume and increases in personnel expenses and other costs. Ordinary profit rose 21.7% to 11,445 million yen, and profit attributable to owners of parent rose 13.1% to 7,361 million yen.
| Item (Millions of yen) | FY3/2026 | FY3/2025 | YoY | Initial Plan (May 8, 2025) | Progress vs. Plan |
|---|---|---|---|---|---|
| Net sales | 224,090 | 219,613 | +2.0% | 230,000 | 97.4% |
| Cost of sales | 183,492 | 182,670 | +0.4% | – | – |
| Gross profit | 40,597 | 36,942 | +9.9% | – | – |
| SG&A expenses | 29,218 | 27,582 | +5.9% | – | – |
| Operating profit | 11,378 | 9,360 | +21.6% | 11,000 | 103.4% |
| Ordinary profit | 11,445 | 9,400 | +21.7% | 10,800 | 106.0% |
| Profit attributable to owners of parent | 7,361 | 6,508 | +13.1% | 7,000 | 105.2% |
On the balance sheet, total assets rose by 17,010 million yen to 223,835 million yen, and net assets increased to 102,966 million yen from 93,371 million yen. Inventories rose to 25,126 million yen from 23,159 million yen, reflecting an increase in the Housing segment. The company notes a shift to short-term debt in a rising interest rate environment; interest-bearing debt was 70,212 million yen and the D/E ratio declined to 0.68 from 0.72. Cash flows from operating activities were 15,172 million yen (18,142 million yen in FY3/2025) and cash flows from investing activities were -10,647 million yen, including purchases of property, plant and equipment of -9,803 million yen and purchases of shares of subsidiaries of -1,590 million yen. Free cash flow decreased to 4,525 million yen from 9,880 million yen, which the company attributes to the increase in inventories and the purchase of shares of subsidiaries in connection with M&A.
Segment Results
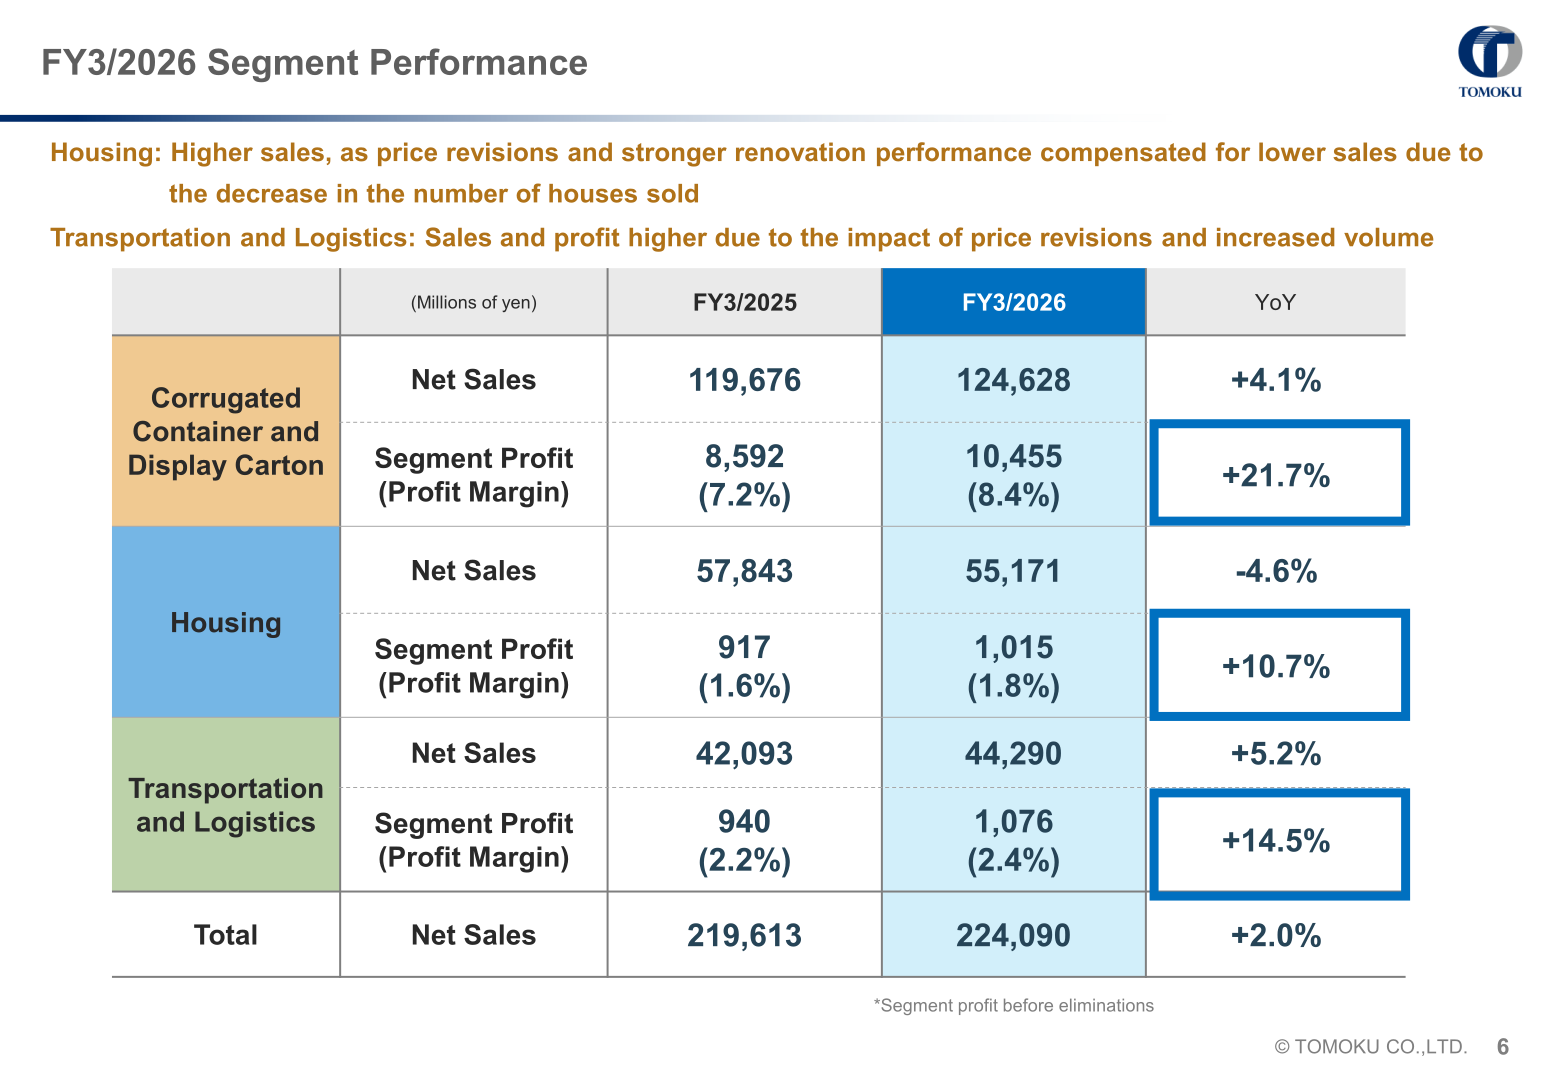
Corrugated Container and Display Carton: Net sales rose 4.1% to 124,628 million yen and segment profit rose 21.7% to 10,455 million yen (margin 8.4%). In Japan, sales volume decreased, but selling prices rose due to price revisions. Overseas, U.S. sales volume declined due to lower demand, resulting in lower sales and profit, while sales in Vietnam rose with higher sales volume but profit decreased due to higher personnel expenses and other costs.
Housing: Net sales declined 4.6% to 55,171 million yen, while segment profit rose 10.7% to 1,015 million yen (margin 1.8%). Profit increased with strong renovation performance, reflecting appropriate selling prices amid rising construction costs, overcoming a decline in the number of houses sold due to a sluggish housing market in Japan.
Transportation and Logistics: Net sales rose 5.2% to 44,290 million yen and segment profit rose 14.5% to 1,076 million yen (margin 2.4%). Sales increased due to higher summer volume and price revisions, and although personnel expenses and vehicle collection costs increased, profit rose with price revisions and increased volume.
| Segment | Metric | FY3/2026 | FY3/2025 | YoY |
|---|---|---|---|---|
| Corrugated Container and Display Carton | Net sales | 124,628 | 119,676 | +4.1% |
| Corrugated Container and Display Carton | Segment profit (margin) | 10,455 (8.4%) | 8,592 (7.2%) | +21.7% |
| Housing | Net sales | 55,171 | 57,843 | -4.6% |
| Housing | Segment profit (margin) | 1,015 (1.8%) | 917 (1.6%) | +10.7% |
| Transportation and Logistics | Net sales | 44,290 | 42,093 | +5.2% |
| Transportation and Logistics | Segment profit (margin) | 1,076 (2.4%) | 940 (2.2%) | +14.5% |
| Total | Net sales | 224,090 | 219,613 | +2.0% |
Figures are in millions of yen. Segment profit is shown before eliminations.
FY3/2027 Forecast
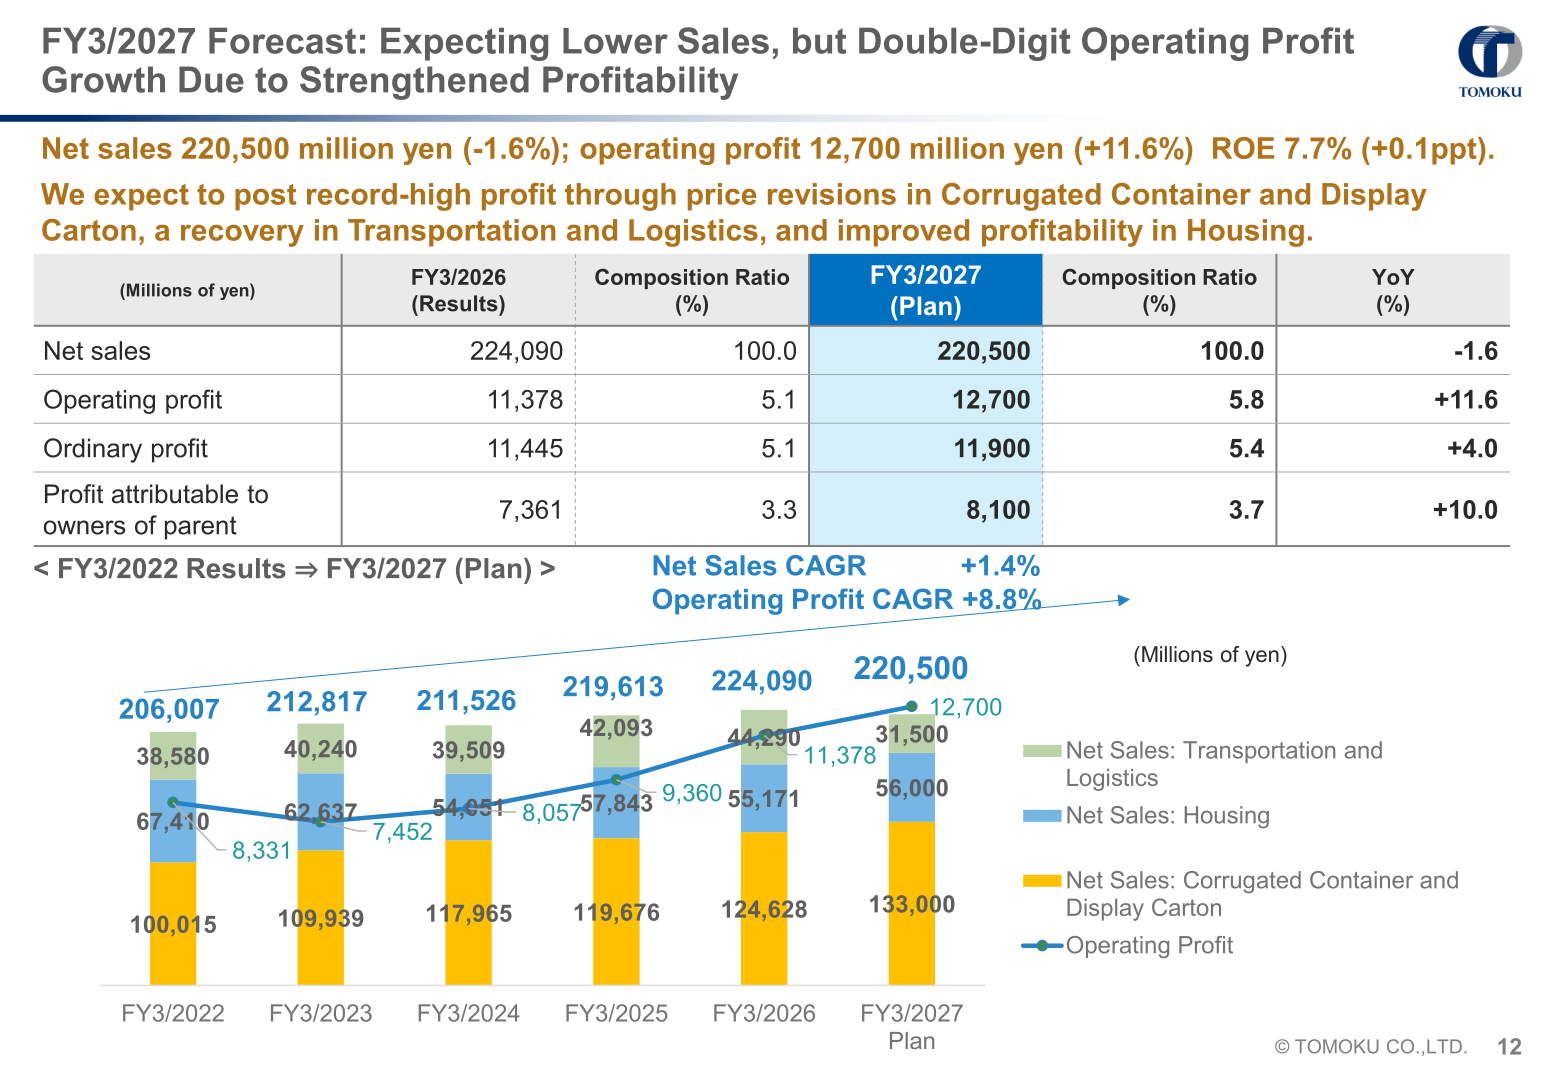
For FY3/2027, the company forecasts net sales of 220,500 million yen (-1.6%), operating profit of 12,700 million yen (+11.6%, margin 5.8%), ordinary profit of 11,900 million yen (+4.0%) and profit attributable to owners of parent of 8,100 million yen (+10.0%), with ROE of 7.7% (+0.1ppt). It expects to post record-high profit through price revisions in Corrugated Container and Display Carton, a recovery in Transportation and Logistics, and improved profitability in Housing. As for the business environment, the company cites concerns about sluggish personal consumption due to the ongoing weak yen and high prices.
By segment, Corrugated Container and Display Carton and Housing are expected to post higher sales and profit with continued price revisions. In Transportation and Logistics, sales are expected to decline due to the sale of shares of subsidiaries, while earnings should improve due to ongoing talks to optimize logistics costs.
| Item (Millions of yen) | FY3/2027 (Plan) | FY3/2026 (Results) | YoY |
|---|---|---|---|
| Net sales | 220,500 | 224,090 | -1.6% |
| Operating profit | 12,700 | 11,378 | +11.6% |
| Ordinary profit | 11,900 | 11,445 | +4.0% |
| Profit attributable to owners of parent | 8,100 | 7,361 | +10.0% |
| Corrugated Container and Display Carton: Net sales | 133,000 | 124,628 | +6.7% |
| Corrugated Container and Display Carton: Segment profit (margin) | 11,500 (8.6%) | 10,455 (8.4%) | +10.0% |
| Housing: Net sales | 56,000 | 55,171 | +1.5% |
| Housing: Segment profit (margin) | 1,200 (2.1%) | 1,015 (1.8%) | +18.2% |
| Transportation and Logistics: Net sales | 31,500 | 44,290 | -28.9% |
| Transportation and Logistics: Segment profit (margin) | 1,100 (3.5%) | 1,076 (2.4%) | +2.2% |
Shareholder Returns
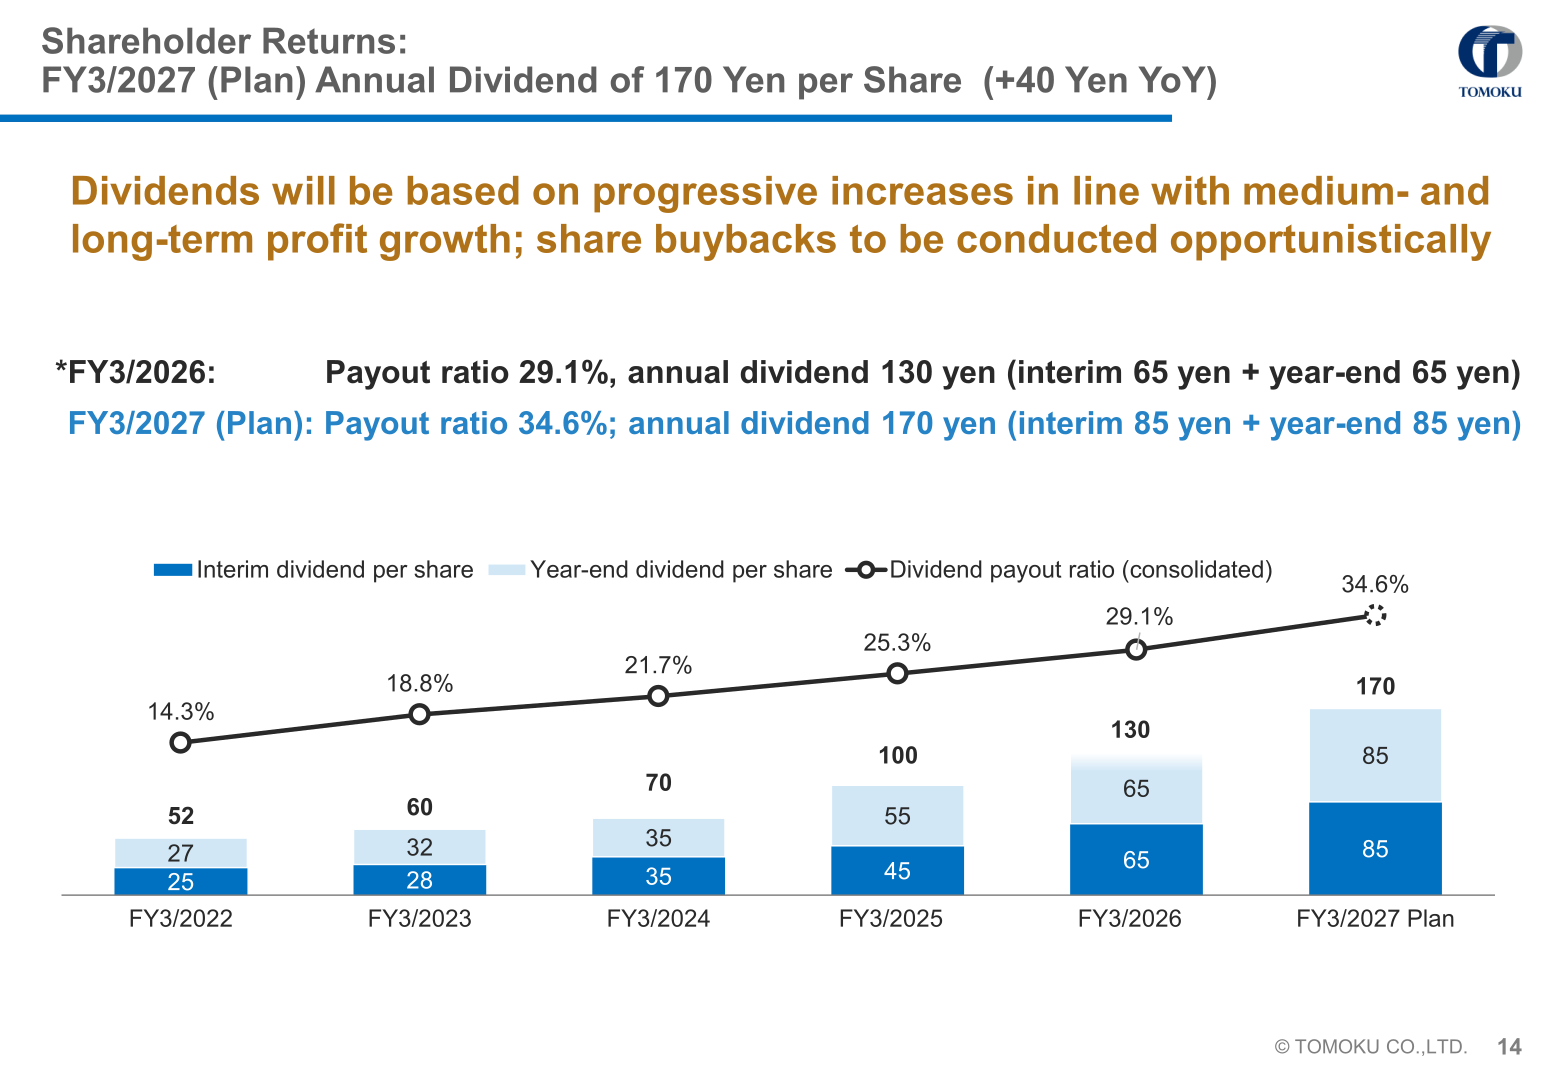
The company’s policy is that dividends will be based on progressive increases in line with medium- and long-term profit growth, with share buybacks to be conducted opportunistically. The FY3/2026 annual dividend was 130 yen per share (interim 65 yen + year-end 65 yen), for a payout ratio of 29.1%. For FY3/2027, the company plans an annual dividend of 170 yen per share (interim 85 yen + year-end 85 yen), up 40 yen, for a payout ratio of 34.6%. Under the Third Medium-Term Business Plan, it aims to raise the dividend payout ratio in stages to at least 40% and is considering shareholder benefits.
| Fiscal Year | Interim | Year-End | Annual | Payout Ratio |
|---|---|---|---|---|
| FY3/2025 | 45 yen | 55 yen | 100 yen | 25.3% |
| FY3/2026 | 65 yen | 65 yen | 130 yen | 29.1% |
| FY3/2027 (Plan) | 85 yen | 85 yen | 170 yen | 34.6% |
Third Medium-Term Business Plan (FY3/2027 – FY3/2029)
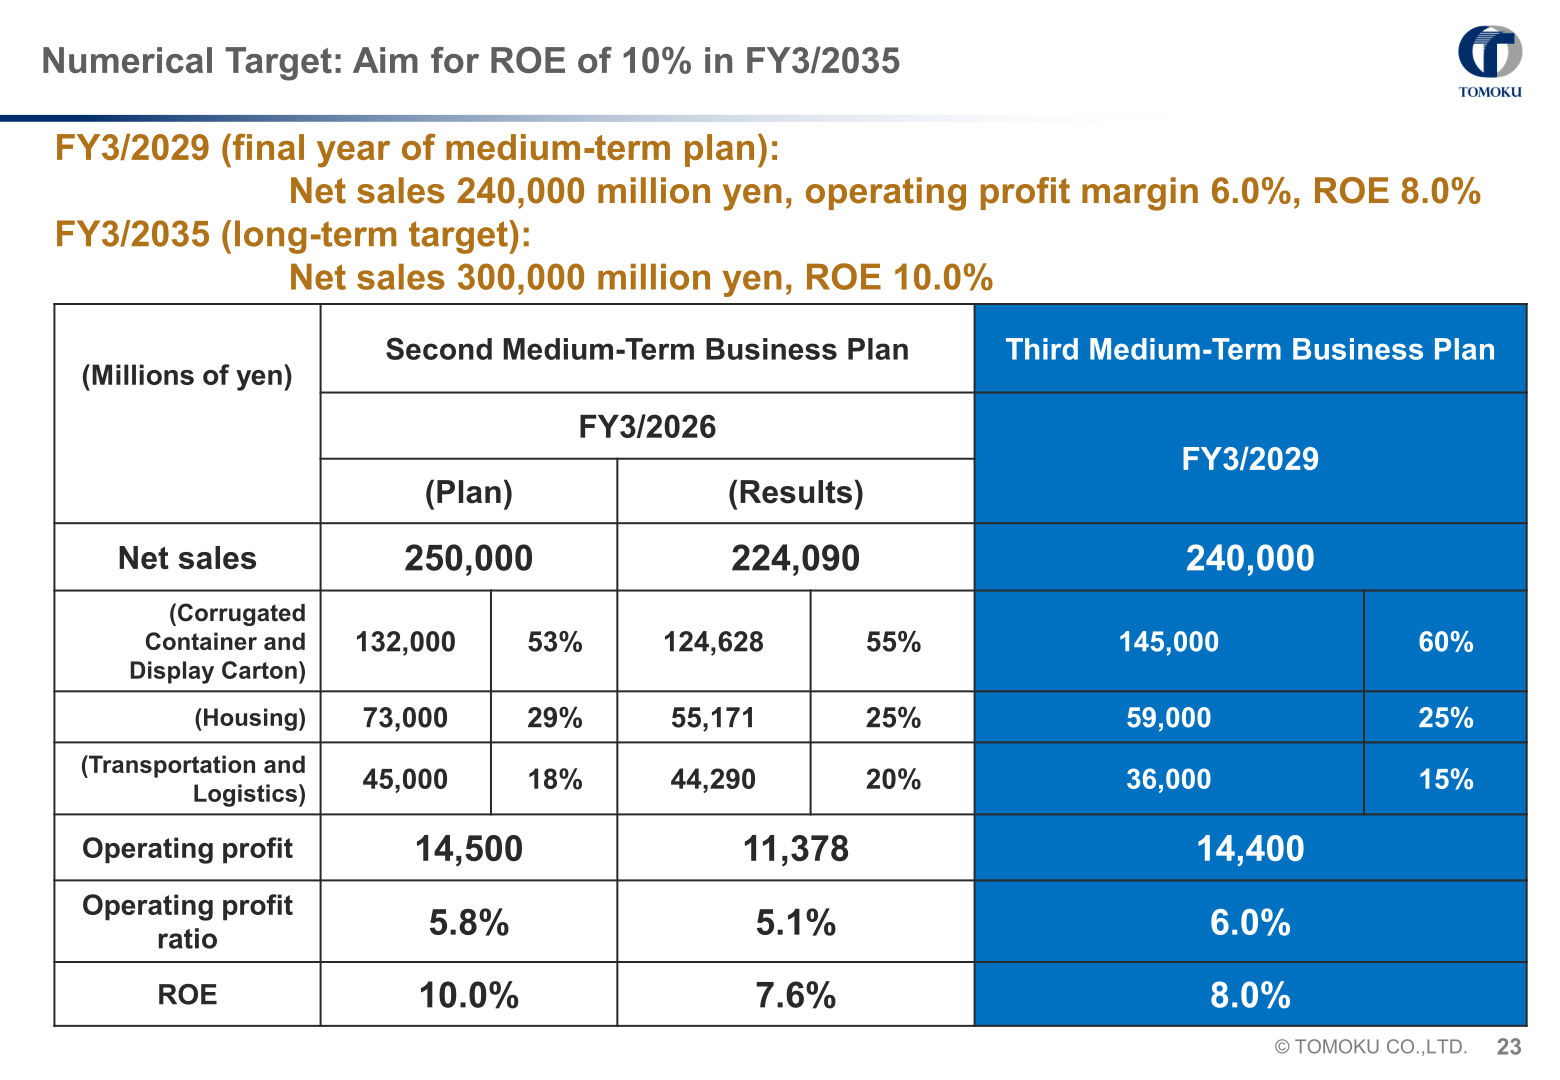
Reviewing the Second Medium-Term Business Plan (FY3/2023 – FY3/2026), the company notes that in the final year net sales were 224,090 million yen against a target of 250,000 million yen, operating profit was 11,378 million yen against a target of 14,500 million yen, and ROE was 7.6% against a target of 10.0%. It states that although sales and profits increased, it must address other issues to improve profitability, as ROE decreased.
The main theme of the Third Medium-Term Business Plan is “Strengthening Profitability – Creating Value 2026-2028.” Its basic policy covers cost-conscious management, a balance between investments in growth and shareholder returns, and capital efficiency improvement (ROE, PBR). For FY3/2029, the final year of the plan, the company targets net sales of 240,000 million yen, operating profit of 14,400 million yen (margin 6.0%) and ROE of 8.0%. As long-term targets for FY3/2035, it aims for net sales of 300,000 million yen and ROE of 10.0%.
| Item (Millions of yen) | FY3/2029 (Third MTP Target) | FY3/2026 (Results) | FY3/2026 (Second MTP Target) |
|---|---|---|---|
| Net sales | 240,000 | 224,090 | 250,000 |
| Corrugated Container and Display Carton | 145,000 | 124,628 | 132,000 |
| Housing | 59,000 | 55,171 | 73,000 |
| Transportation and Logistics | 36,000 | 44,290 | 45,000 |
| Operating profit | 14,400 | 11,378 | 14,500 |
| Operating profit ratio | 6.0% | 5.1% | 5.8% |
| ROE | 8.0% | 7.6% | 10.0% |
For cash allocation over the three years from FY3/2027 to FY3/2029, the company expects cash flows from operations of 55,000 million yen plus cash on hand of 3,000 million yen, to be allocated to capital investment of 28,000 million yen (Corrugated Container and Display Carton 23,000 million yen, Housing 1,000 million yen, Transportation and Logistics 4,000 million yen), M&A of 15,000 million yen, and shareholder returns of 15,000 million yen (dividends 10,000 million yen, share buybacks 5,000 million yen).
Other topics include a memorandum of understanding signed on April 7, 2026 with Nippon Paper Industries Co., Ltd. and Tokushu Tokai Paper Co., Ltd. to consider future collaborations in the Corrugated Container and Display Carton segment, and the acquisition of Okayama-based logistics company Fujishou as a subsidiary in December 2025 to expand the Transportation and Logistics network in western Japan. The company also states that its actual PBR is 0.65x (as of May 25, 2026), and that it will continue addressing PBR below 1x by improving ROE and PER, including expanding English-language disclosure materials.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















