
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Double Standard labels the fiscal year ended March 31, 2026 as “FY2026” in its presentation; this site classifies it as FY2025. The body text and tables below keep the company’s own labels (FY2026 = year ended March 2026; FY2027 = year ending March 2027).
Double Standard Inc., which builds a data business on its proprietary data cleansing technology, reported net sales of 7,010,865 JPY thousands for FY2026 (down 12.4% year on year) and operating profit of 1,721,657 JPY thousands (down 33.9%). The company attributes the decline to the termination of transactions with a major client, timing differences in revenue recognition for certain contracted projects, and upfront costs from delays in launching new services. At the same time, the number of client companies rose to 246, with 60 new clients acquired. For FY2027, the company forecasts net sales of 7,200,000 JPY thousands and operating profit of 1,800,000 JPY thousands, with an annual dividend of ¥70 per share.
Consolidated Results (Full-Year Actual)
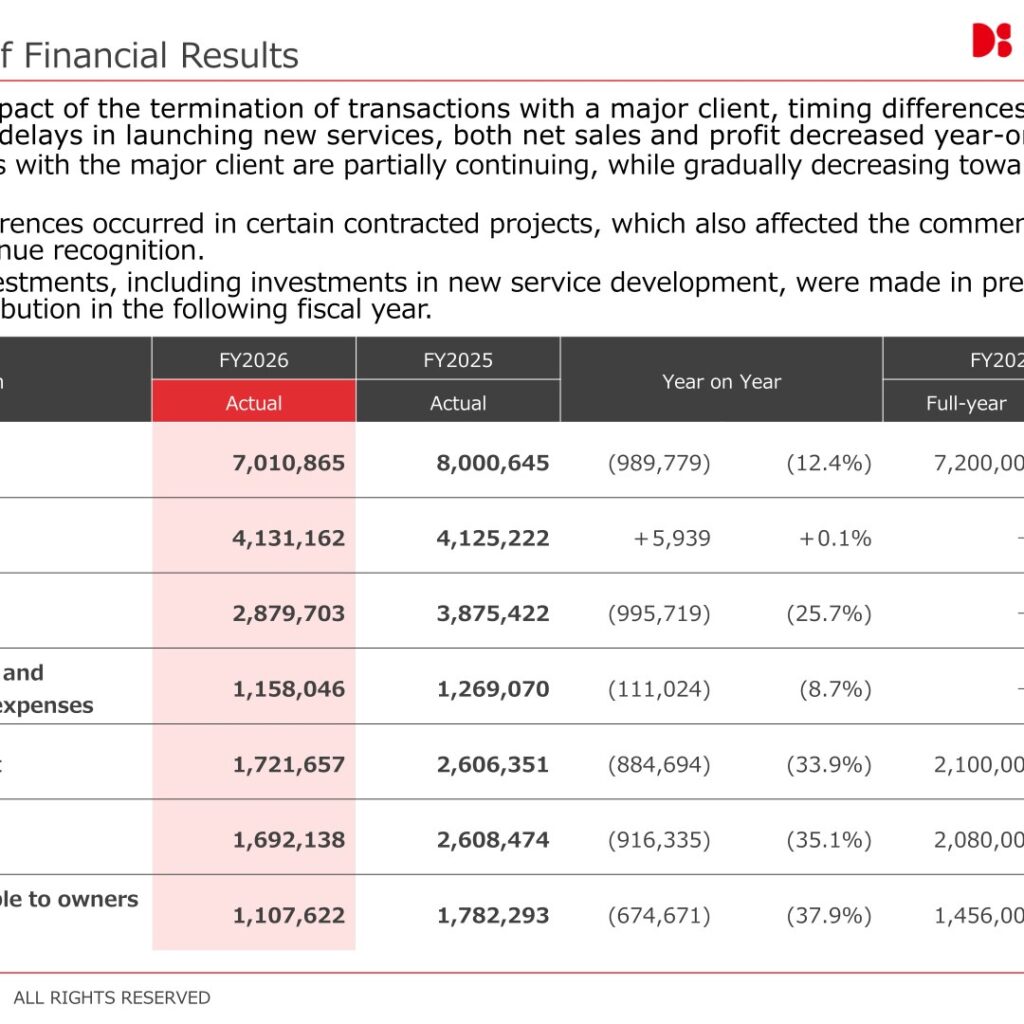
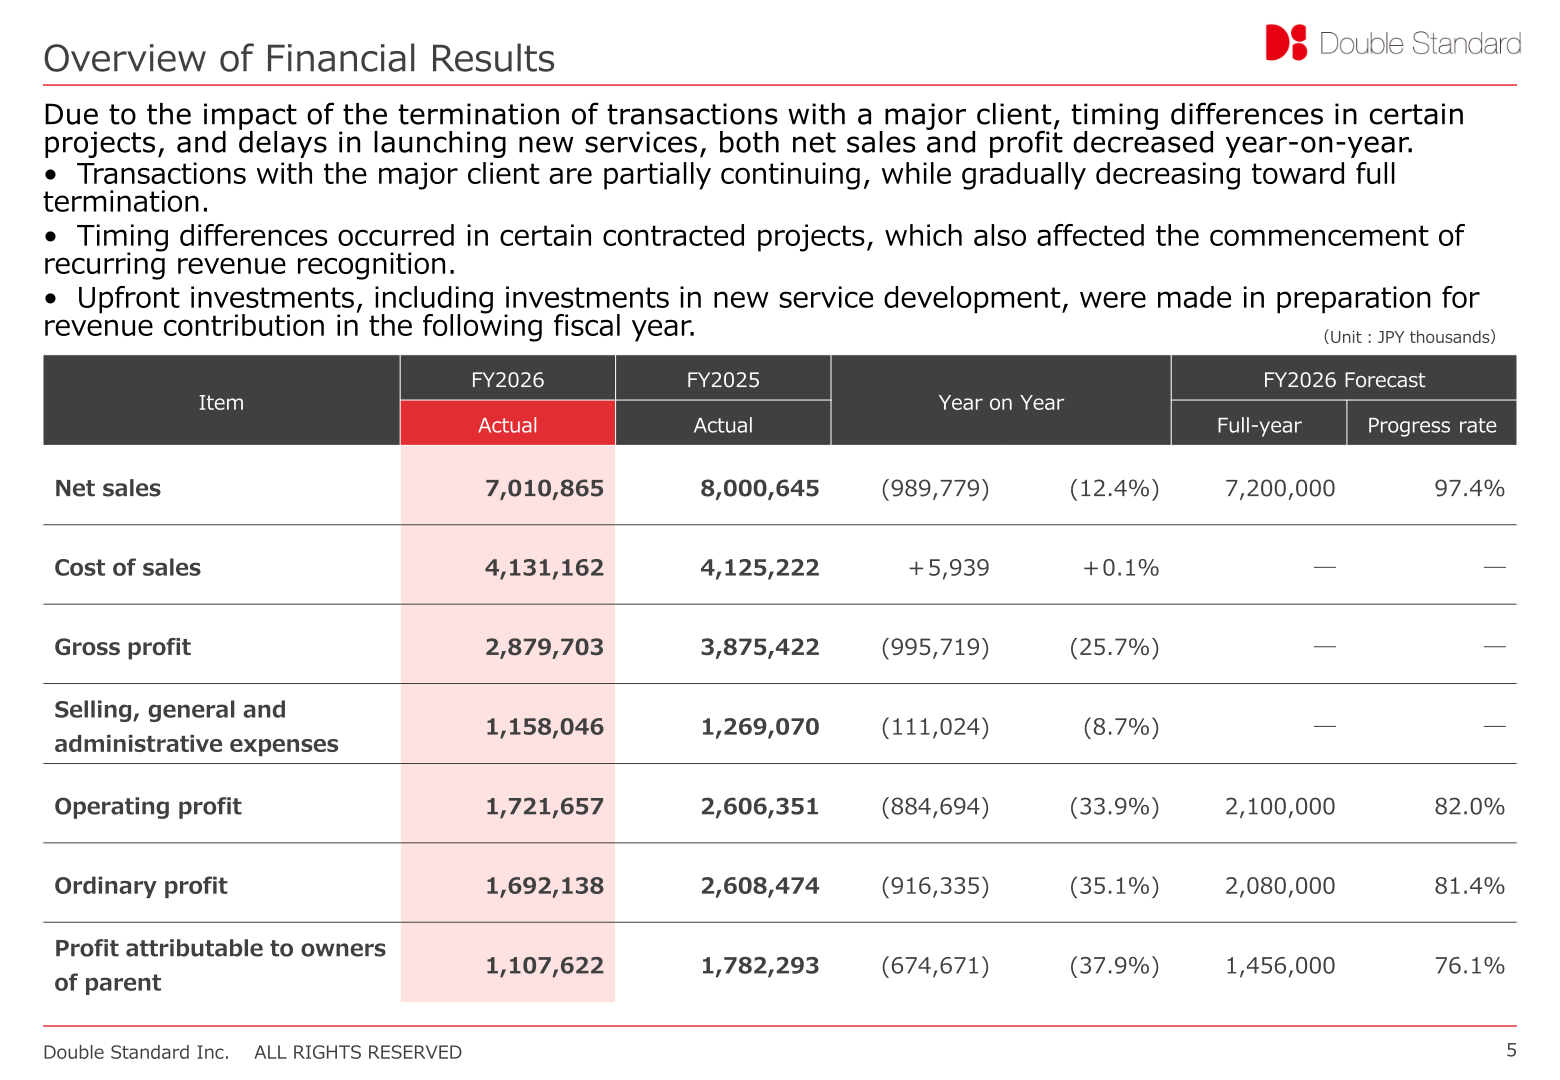
Net sales came to 7,010,865 JPY thousands, versus 8,000,645 JPY thousands in FY2025, a decrease of 12.4%, and reached 97.4% of the FY2026 full-year forecast of 7,200,000 JPY thousands. Gross profit fell 25.7% to 2,879,703 JPY thousands as cost of sales rose 0.1% to 4,131,162 JPY thousands, while SG&A expenses declined 8.7% to 1,158,046 JPY thousands. Operating profit was 1,721,657 JPY thousands (82.0% of the full-year forecast), ordinary profit was 1,692,138 JPY thousands (81.4%), and profit attributable to owners of parent was 1,107,622 JPY thousands (76.1%).
According to the company, transactions with the major client are partially continuing but gradually decreasing toward full termination; timing differences in certain contracted projects also affected the start of recurring revenue recognition; and upfront investments, including new service development, were made in preparation for revenue contribution in the following fiscal year. The operating profit margin was 24.6%, compared with 32.6% in FY2025.
| Item (JPY thousands) | FY2026 Actual | FY2025 Actual | YoY Change | YoY % | FY2026 Forecast | Progress |
|---|---|---|---|---|---|---|
| Net sales | 7,010,865 | 8,000,645 | (989,779) | (12.4%) | 7,200,000 | 97.4% |
| Cost of sales | 4,131,162 | 4,125,222 | +5,939 | +0.1% | ― | ― |
| Gross profit | 2,879,703 | 3,875,422 | (995,719) | (25.7%) | ― | ― |
| SG&A expenses | 1,158,046 | 1,269,070 | (111,024) | (8.7%) | ― | ― |
| Operating profit | 1,721,657 | 2,606,351 | (884,694) | (33.9%) | 2,100,000 | 82.0% |
| Ordinary profit | 1,692,138 | 2,608,474 | (916,335) | (35.1%) | 2,080,000 | 81.4% |
| Profit attributable to owners of parent | 1,107,622 | 1,782,293 | (674,671) | (37.9%) | 1,456,000 | 76.1% |
On the balance sheet, total assets were 7,383,191 JPY thousands (down 1.9%), including cash and deposits of 5,286,741 JPY thousands. Liabilities decreased 38.5% to 703,731 JPY thousands, mainly due to lower income taxes payable, consumption taxes payable and accounts payable, while net assets rose 4.7% to 6,679,460 JPY thousands. The equity ratio improved to 90.5% from 84.8%. Cash flows from operating activities were 775,258 JPY thousands, compared with 1,994,562 JPY thousands in FY2025, and cash dividends paid were △811,509 JPY thousands.
Business Highlights: Client Base Expansion
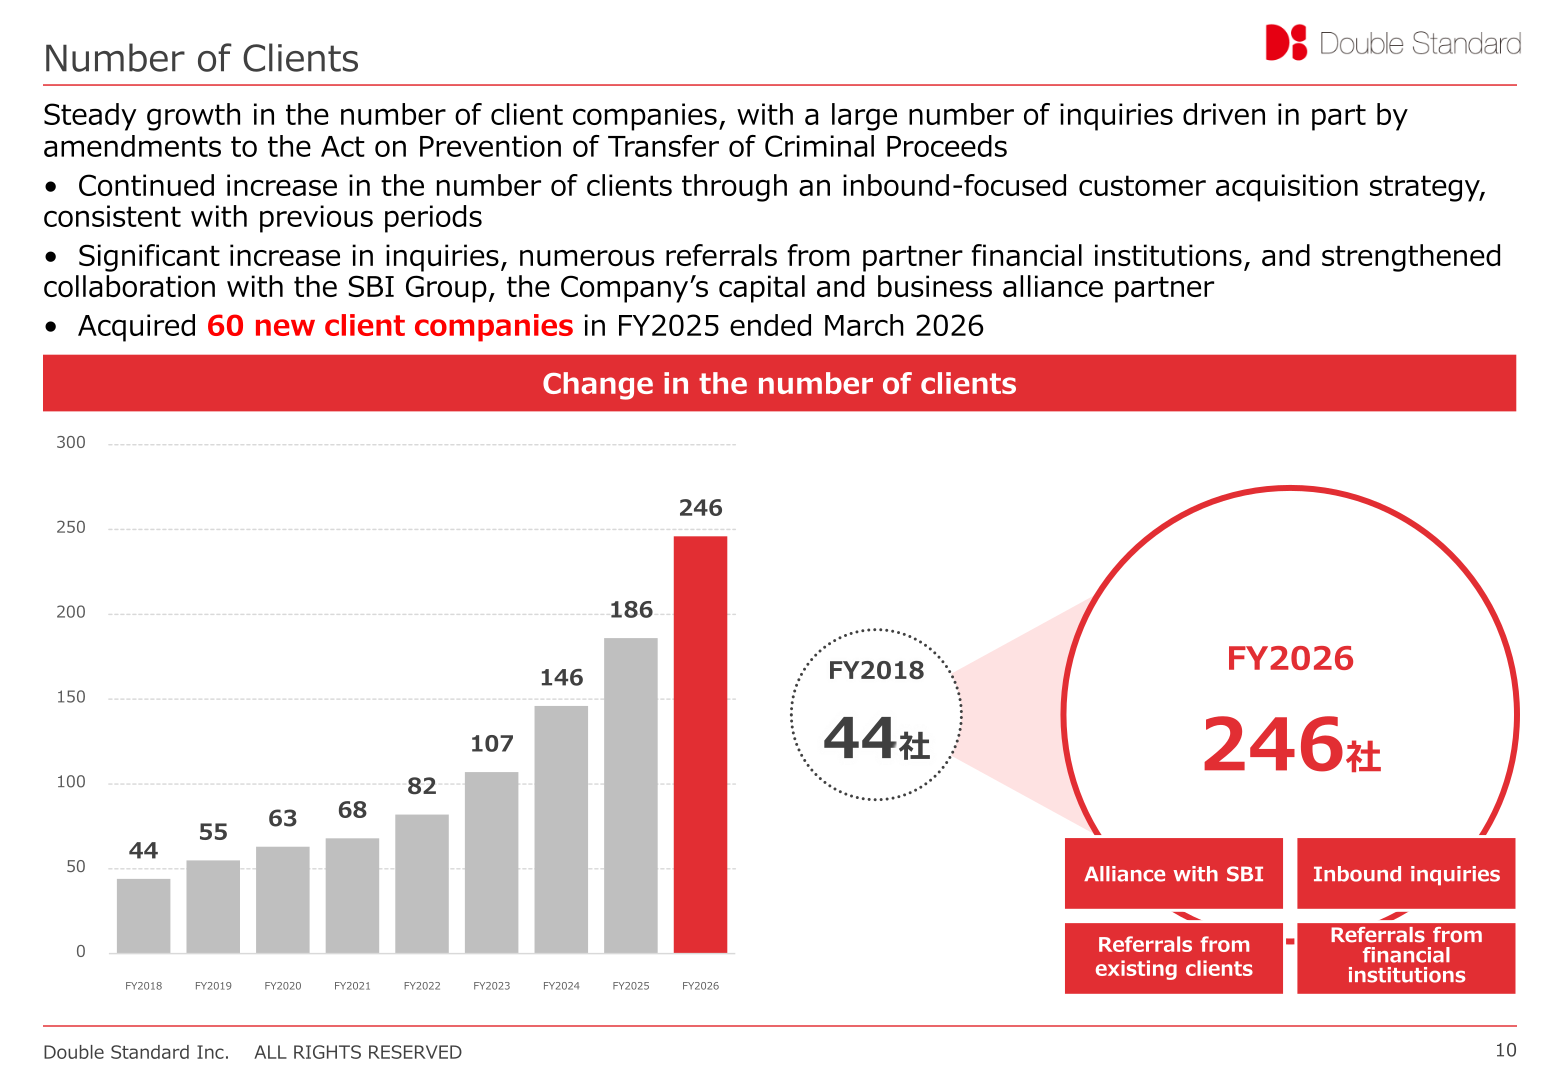
The company does not present segment-level results in the materials. As its key operating indicator, it reports that the number of client companies reached 246 in FY2026, up from 186 in FY2025 and 44 in FY2018, with 60 new client companies acquired. Growth was driven by an inbound-focused customer acquisition strategy, a significant increase in inquiries (driven in part by amendments to the Act on Prevention of Transfer of Criminal Proceeds), numerous referrals from partner financial institutions, and strengthened collaboration with the SBI Group, the company’s capital and business alliance partner. The company also states that it acquired customers with the potential to become major clients and will focus on upselling and cross-selling to them.
| Fiscal Year | Number of Clients |
|---|---|
| FY2018 | 44 |
| FY2019 | 55 |
| FY2020 | 63 |
| FY2021 | 68 |
| FY2022 | 82 |
| FY2023 | 107 |
| FY2024 | 146 |
| FY2025 | 186 |
| FY2026 | 246 |
Its service lineup includes a data generating system based on data cleansing and data enhancement, D-Fit and D-Just (manual data entry reduction services), D-Confia (an identity verification OCR service), D-Cleanse (a data preparation service covering collection, processing and record matching), and D-Check (a website update detection service).
FY2027 Forecast
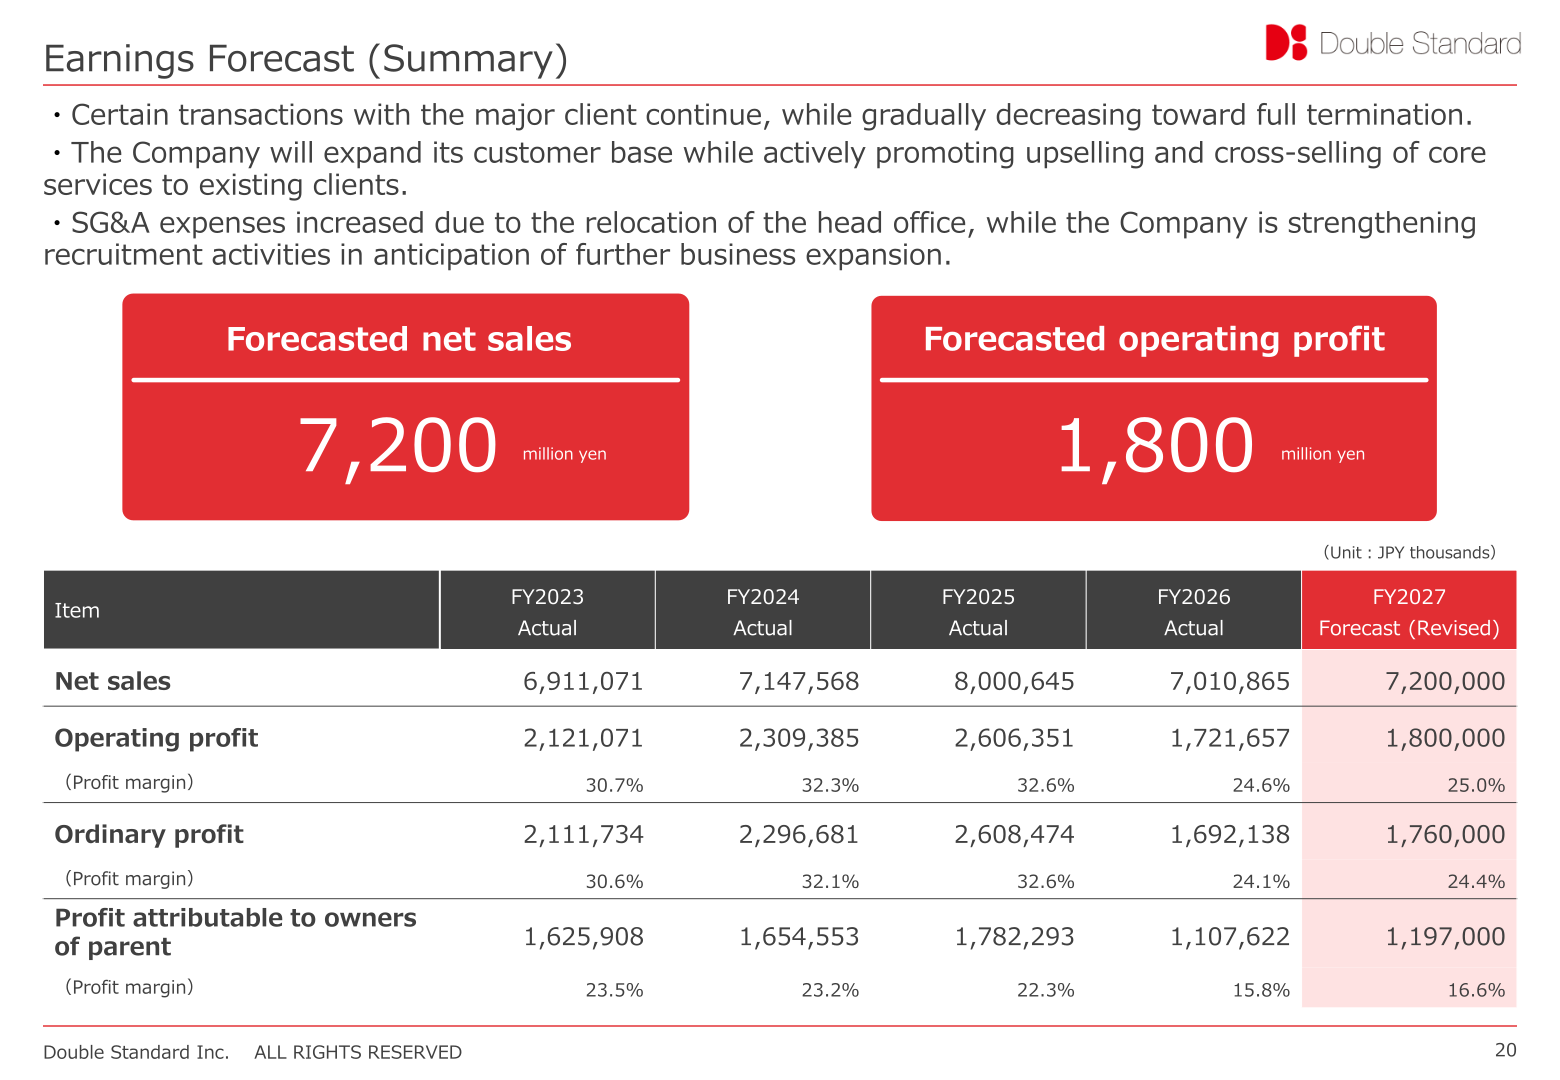
For FY2027, the company forecasts net sales of 7,200,000 JPY thousands, operating profit of 1,800,000 JPY thousands (margin 25.0%), ordinary profit of 1,760,000 JPY thousands (margin 24.4%) and profit attributable to owners of parent of 1,197,000 JPY thousands (margin 16.6%). The company notes that certain transactions with the major client continue while gradually decreasing toward full termination, that it will expand its customer base while promoting upselling and cross-selling of core services to existing clients, and that SG&A expenses increased due to the relocation of the head office while it strengthens recruitment in anticipation of further business expansion.
| Item (JPY thousands) | FY2027 Forecast (Revised) | FY2026 Actual | FY2025 Actual |
|---|---|---|---|
| Net sales | 7,200,000 | 7,010,865 | 8,000,645 |
| Operating profit | 1,800,000 | 1,721,657 | 2,606,351 |
| (Profit margin) | 25.0% | 24.6% | 32.6% |
| Ordinary profit | 1,760,000 | 1,692,138 | 2,608,474 |
| (Profit margin) | 24.4% | 24.1% | 32.6% |
| Profit attributable to owners of parent | 1,197,000 | 1,107,622 | 1,782,293 |
| (Profit margin) | 16.6% | 15.8% | 22.3% |
The basic management policy for FY2027 is to expand the customer base and relationships with existing clients following the termination of transactions with the major client. Priority items are acquiring new clients through efficiency-focused, inbound-driven sales activities (inquiries and referrals) and expanding business with existing clients by selling services not yet introduced to them. Regarding Daiwa Living Co., Ltd., the contract largely ended as of March 31, 2025, but the company entered into separate agreements to provide transition support services; certain transactions continue in FY2027, and all such transactions are expected to terminate in the future.
Shareholder Returns
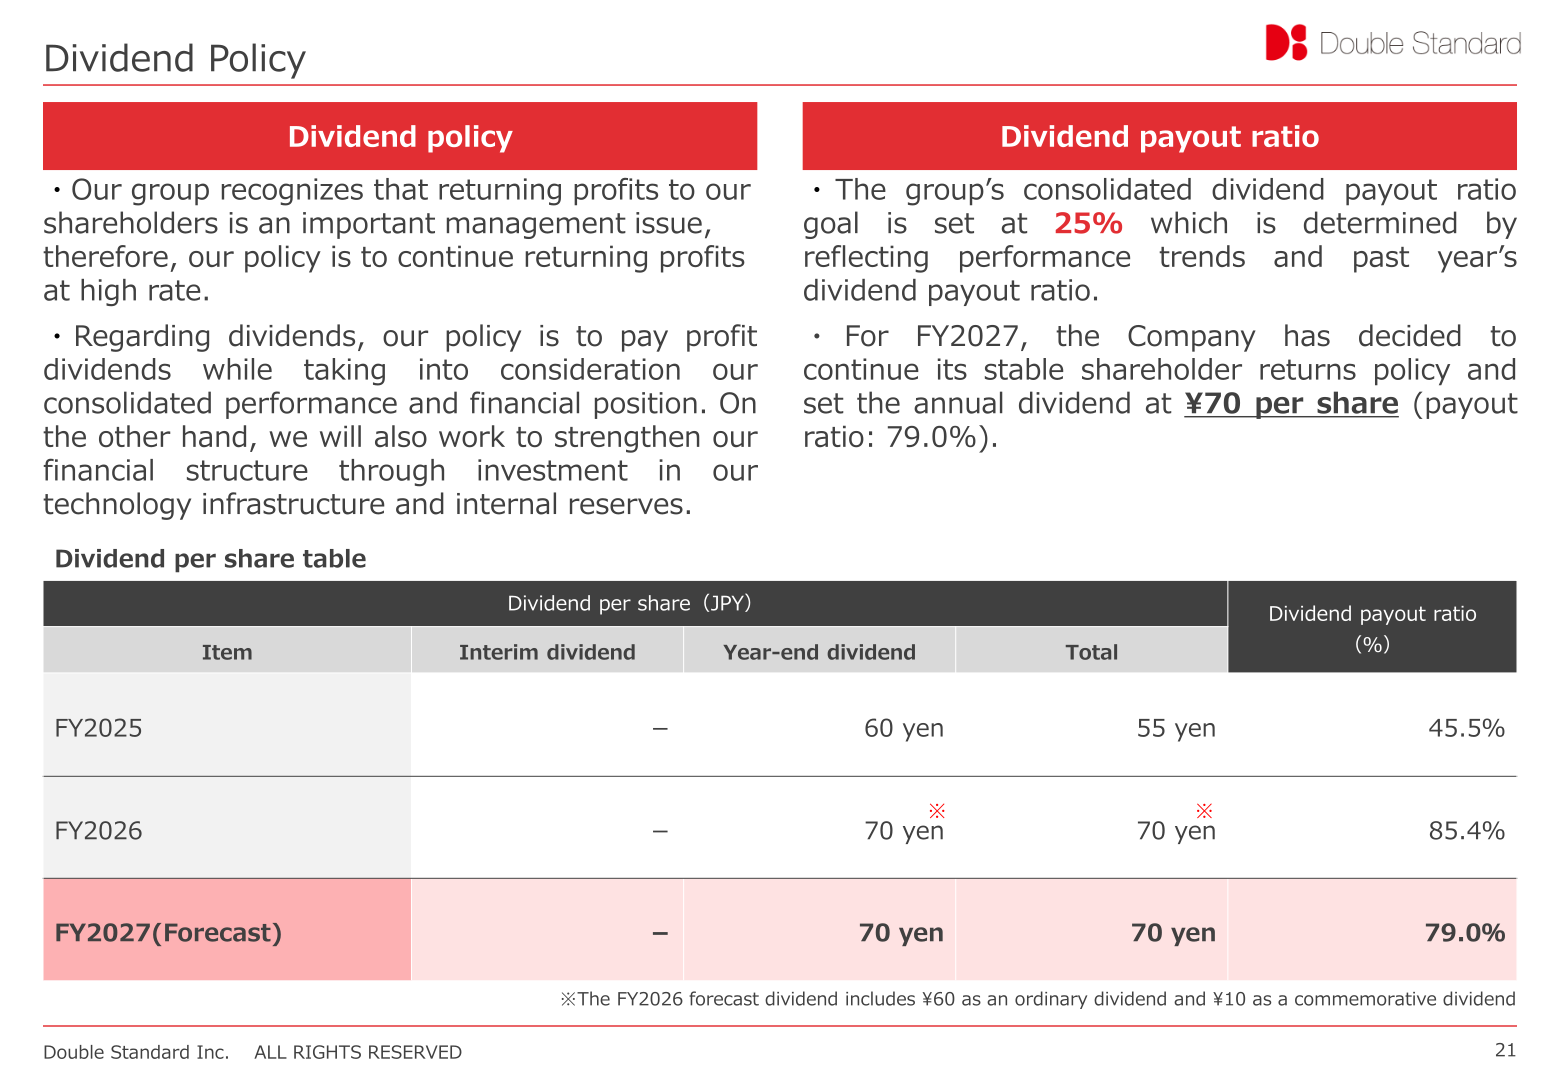
The company’s policy is to continue returning profits at a high rate while also strengthening its financial structure through investment in its technology infrastructure and internal reserves. Its consolidated dividend payout ratio goal is set at 25%. The FY2026 dividend was 70 yen per share (year-end only), comprising ¥60 as an ordinary dividend and ¥10 as a commemorative dividend, for a payout ratio of 85.4%. For FY2027, the company has decided to continue its stable shareholder returns policy and set the annual dividend at ¥70 per share (payout ratio: 79.0%).
| Item | Interim Dividend | Year-End Dividend | Total | Payout Ratio |
|---|---|---|---|---|
| FY2026 | - | 70 yen | 70 yen | 85.4% |
| FY2027 (Forecast) | - | 70 yen | 70 yen | 79.0% |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















