
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
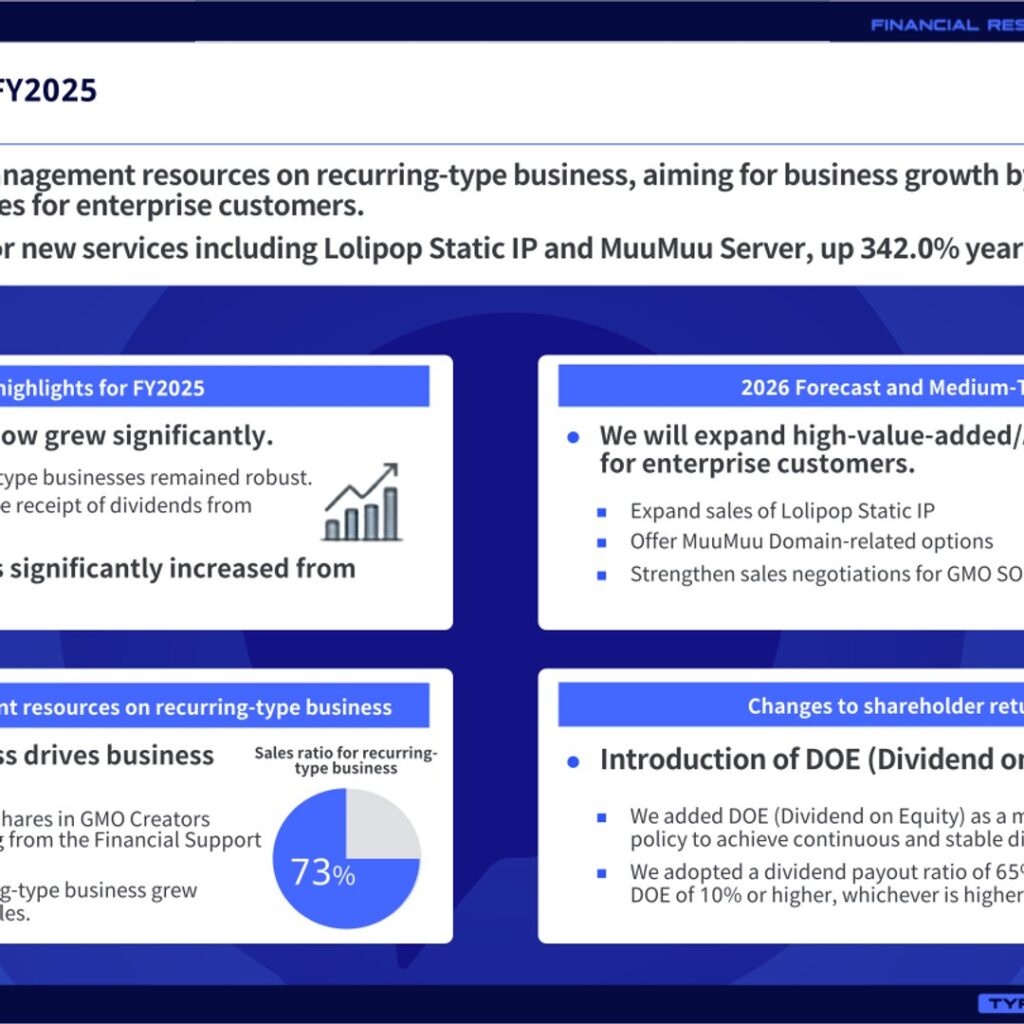
GMO Pepabo, Inc. reported results for the fiscal year ended December 31, 2025 (FY2025). Net sales were 10,959 million yen (100.3% year on year) and operating profit rose to 932 million yen (112.5%), while ordinary profit reached 1,229 million yen (131.1%) and profit attributable to owners of parent reached 878 million yen (148.5%). The company concentrated management resources on its recurring-type business, whose share of net sales rose to 73.0%, and withdrew from the Financial Support business through the transfer of shares in GMO Creators Network, Inc. Dividends per share were raised from 57.00 yen to 111.00 yen, including a special dividend.
Consolidated Results (Full-Year Actual)
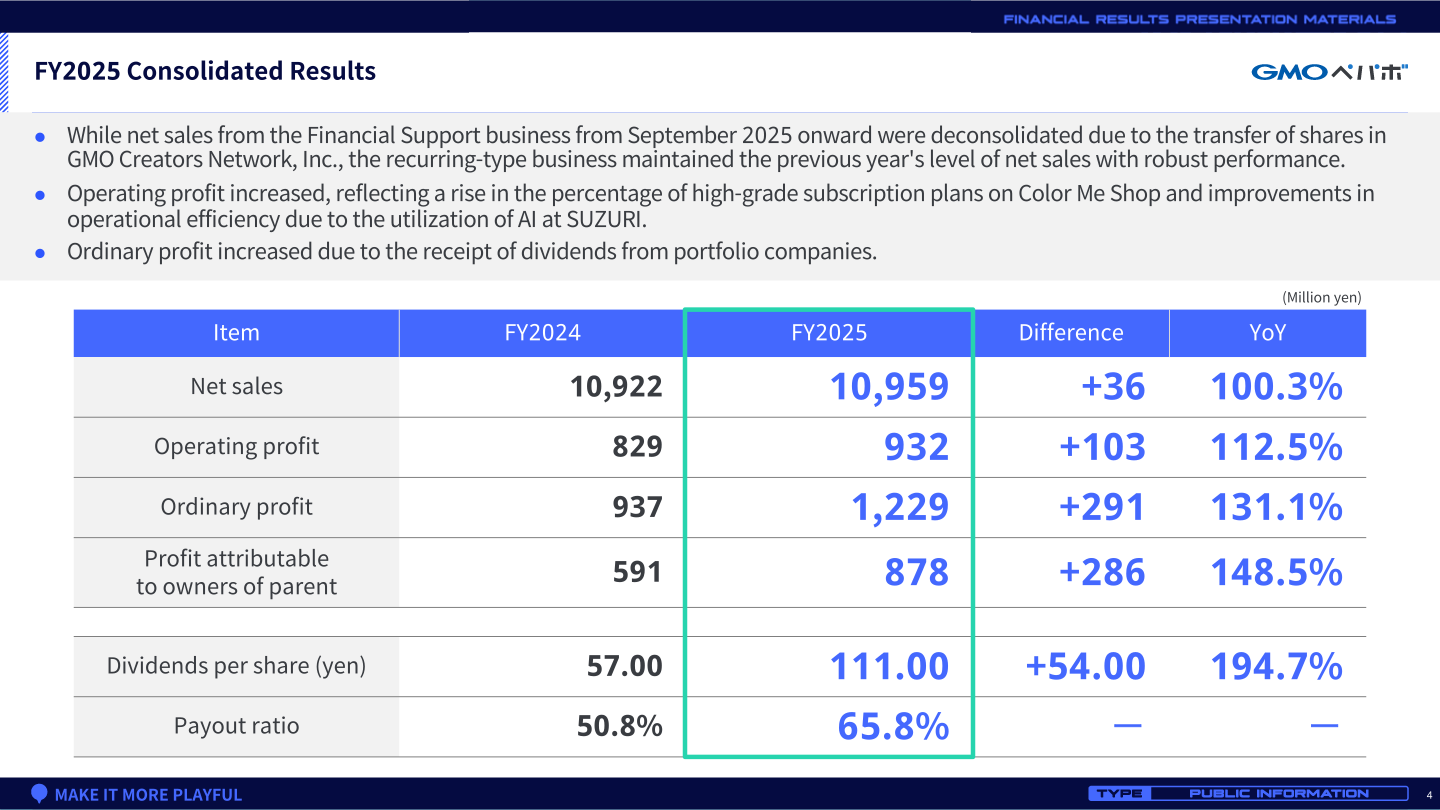
According to the company, net sales from the Financial Support business were deconsolidated from September 2025 onward due to the transfer of shares in GMO Creators Network, Inc., but the recurring-type business maintained the previous year’s level of net sales with robust performance. Operating profit increased, reflecting a rise in the percentage of high-grade subscription plans on Color Me Shop and improvements in operational efficiency due to the utilization of AI at SUZURI. Ordinary profit increased due to the receipt of dividends from portfolio companies.
| Item (million yen) | FY2024 | FY2025 | Difference | YoY |
|---|---|---|---|---|
| Net sales | 10,922 | 10,959 | +36 | 100.3% |
| Operating profit | 829 | 932 | +103 | 112.5% |
| Ordinary profit | 937 | 1,229 | +291 | 131.1% |
| Profit attributable to owners of parent | 591 | 878 | +286 | 148.5% |
| Dividends per share (yen) | 57.00 | 111.00 | +54.00 | 194.7% |
| Payout ratio | 50.8% | 65.8% | — | — |
Net sales from the recurring-type business grew 104.3% year on year due to an increase in the ratio of subscriptions to high unit price plans, and the recurring-type business sales ratio reached 73.0% (70.2% in the fiscal year ended December 31, 2024), up 2.8 percentage points. Net sales of new services in the Domain and Rental Server (Hosting) business (MuuMuu Domain-related options, Lolipop Static IP and Lolipop! for Gamers) were 156 million yen, up 342.0% year on year from 45 million yen.
Segment Results
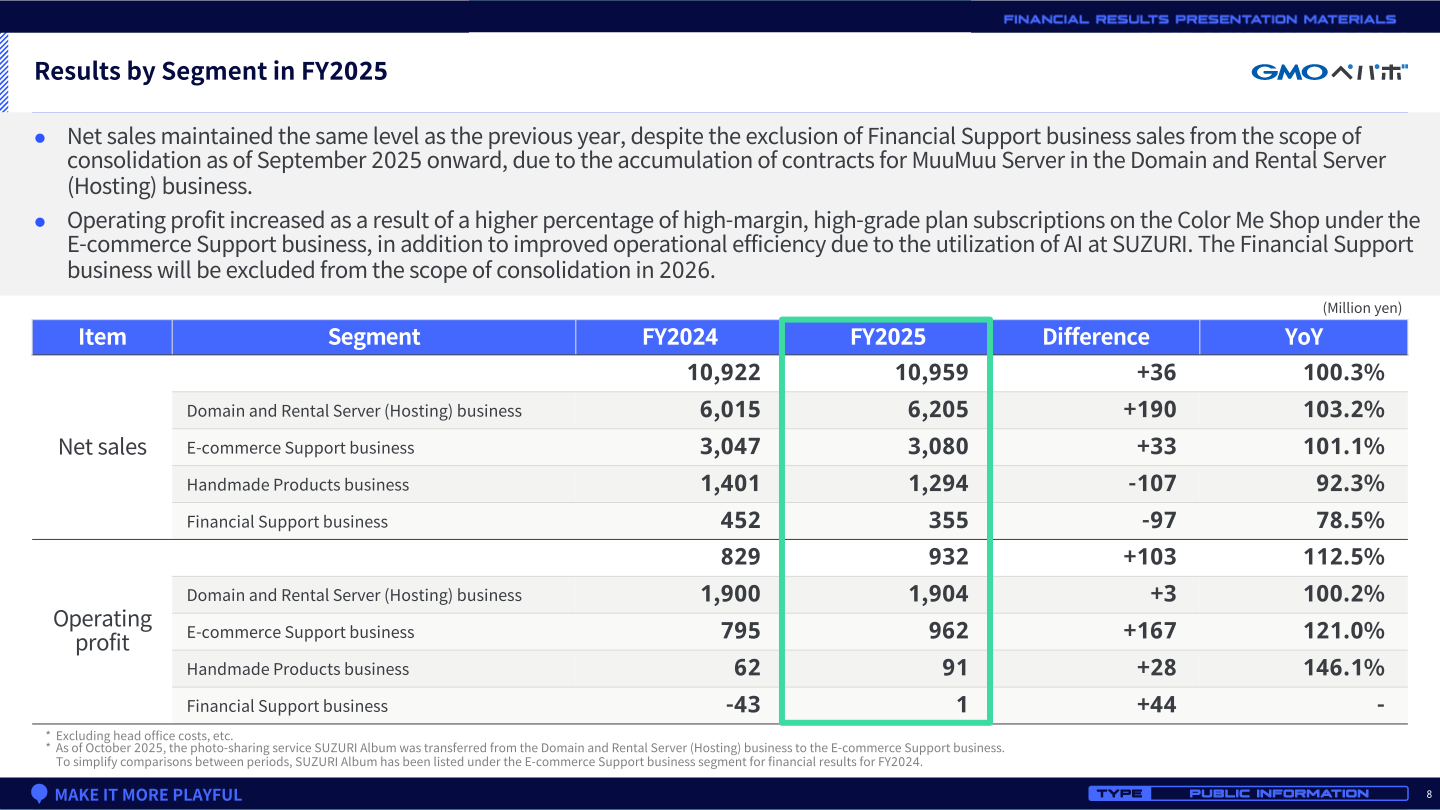
Net sales maintained the same level as the previous year, despite the exclusion of Financial Support business sales from the scope of consolidation as of September 2025 onward, due to the accumulation of contracts for MuuMuu Server in the Domain and Rental Server (Hosting) business. Operating profit increased as a result of a higher percentage of high-margin, high-grade plan subscriptions on Color Me Shop under the E-commerce Support business, in addition to improved operational efficiency due to the utilization of AI at SUZURI. The Financial Support business will be excluded from the scope of consolidation in 2026.
| Segment | Metric (million yen) | FY2024 | FY2025 | YoY |
|---|---|---|---|---|
| Domain and Rental Server (Hosting) business | Net sales | 6,015 | 6,205 | 103.2% |
| E-commerce Support business | Net sales | 3,047 | 3,080 | 101.1% |
| Handmade Products business | Net sales | 1,401 | 1,294 | 92.3% |
| Financial Support business | Net sales | 452 | 355 | 78.5% |
| Domain and Rental Server (Hosting) business | Operating profit | 1,900 | 1,904 | 100.2% |
| E-commerce Support business | Operating profit | 795 | 962 | 121.0% |
| Handmade Products business | Operating profit | 62 | 91 | 146.1% |
| Financial Support business | Operating profit | -43 | 1 | – |
Domain and Rental Server (Hosting): Net sales increased due to higher sales of new services such as Lolipop! for Gamers, MuuMuu Server and MuuMuu Domain-related options. Lolipop! net sales were 2,640 million yen (102.4%) and MuuMuu Domain net sales were 2,726 million yen (104.7%). Segment operating profit was 1,904 million yen; Lolipop! operating profit decreased to 1,136 million yen (94.6%) as expenses were posted for the development of Lolipop! for Gamers and Lolipop Static IP, while MuuMuu Domain operating profit rose to 465 million yen (104.9%).
E-commerce Support: Color Me Shop net sales were 2,185 million yen (101.7%) and operating profit 875 million yen (113.3%), as the percentage of subscriptions to high-grade plans rose despite a decline in revenue from website creation services. SUZURI net sales were 819 million yen (100.4%) and operating profit 122 million yen (283.2%), reflecting higher operational efficiency and reduced promotional costs enabled by AI utilization. Color Me Shop’s annual gross merchandise value for 2025 reached 209.9 billion yen, an increase of 5.0% year on year.
Handmade Products (minne): Net sales decreased to 1,294 million yen (92.3%) as commission sales declined due to a decline in gross merchandise value, while operating profit increased to 91 million yen (146.1%) following an increase in sales from pay-per-click advertising and the optimization of human resources. Financial Support (FREENANCE): Sales were excluded from posting as of September due to the transfer of shares; operating profit was 1 million yen, with one-time expenses incurred due to the share transfer but robust collection of receivables.
FY2026 Forecast
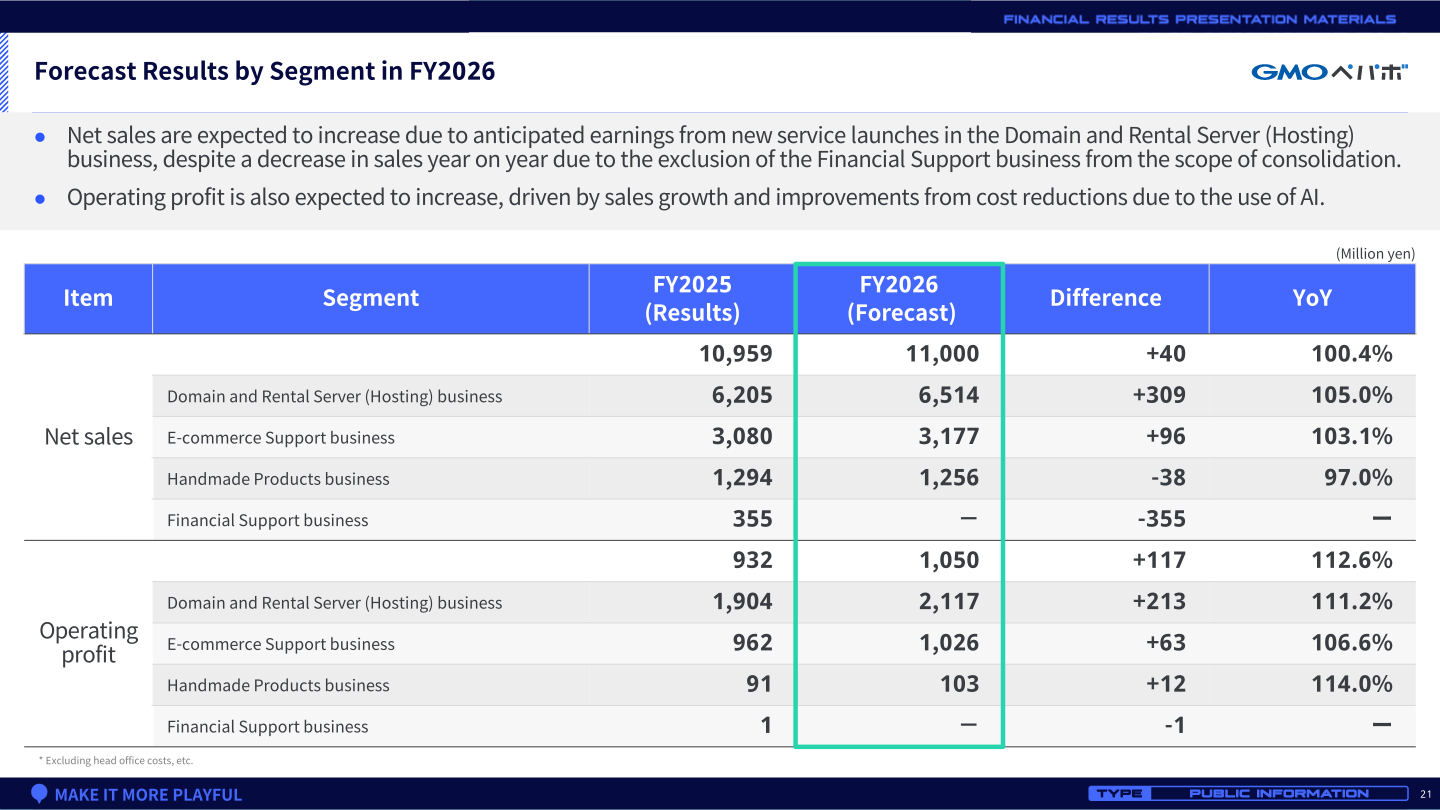
For FY2026, the company projects net sales of 11,000 million yen (100.4%) and operating profit of 1,050 million yen (112.6%). Ordinary profit is forecast at 1,050 million yen (85.4%) and profit attributable to owners of parent at 735 million yen (83.7%), as non-operating income and expenses are assumed at 0 versus 296 million yen in FY2025; the company states that ordinary profit is also forecast to increase year on year when excluding one-time non-operating income and expenses. By segment, net sales are expected to increase due to anticipated earnings from new service launches in the Domain and Rental Server (Hosting) business, despite the exclusion of the Financial Support business, and operating profit is expected to increase, driven by sales growth and cost reductions due to the use of AI.
| Item (million yen) | FY2025 (Actual) | FY2026 (Forecast) | YoY |
|---|---|---|---|
| Net sales | 10,959 | 11,000 | 100.4% |
| Operating profit | 932 | 1,050 | 112.6% |
| Ordinary profit | 1,229 | 1,050 | 85.4% |
| Profit attributable to owners of parent | 878 | 735 | 83.7% |
| EPS (yen) | 168.68 | 142.47 | 84.5% |
| Domain and Rental Server (Hosting) business – Net sales | 6,205 | 6,514 | 105.0% |
| E-commerce Support business – Net sales | 3,080 | 3,177 | 103.1% |
| Handmade Products business – Net sales | 1,294 | 1,256 | 97.0% |
| Domain and Rental Server (Hosting) business – Operating profit | 1,904 | 2,117 | 111.2% |
| E-commerce Support business – Operating profit | 962 | 1,026 | 106.6% |
| Handmade Products business – Operating profit | 91 | 103 | 114.0% |
Shareholder Returns
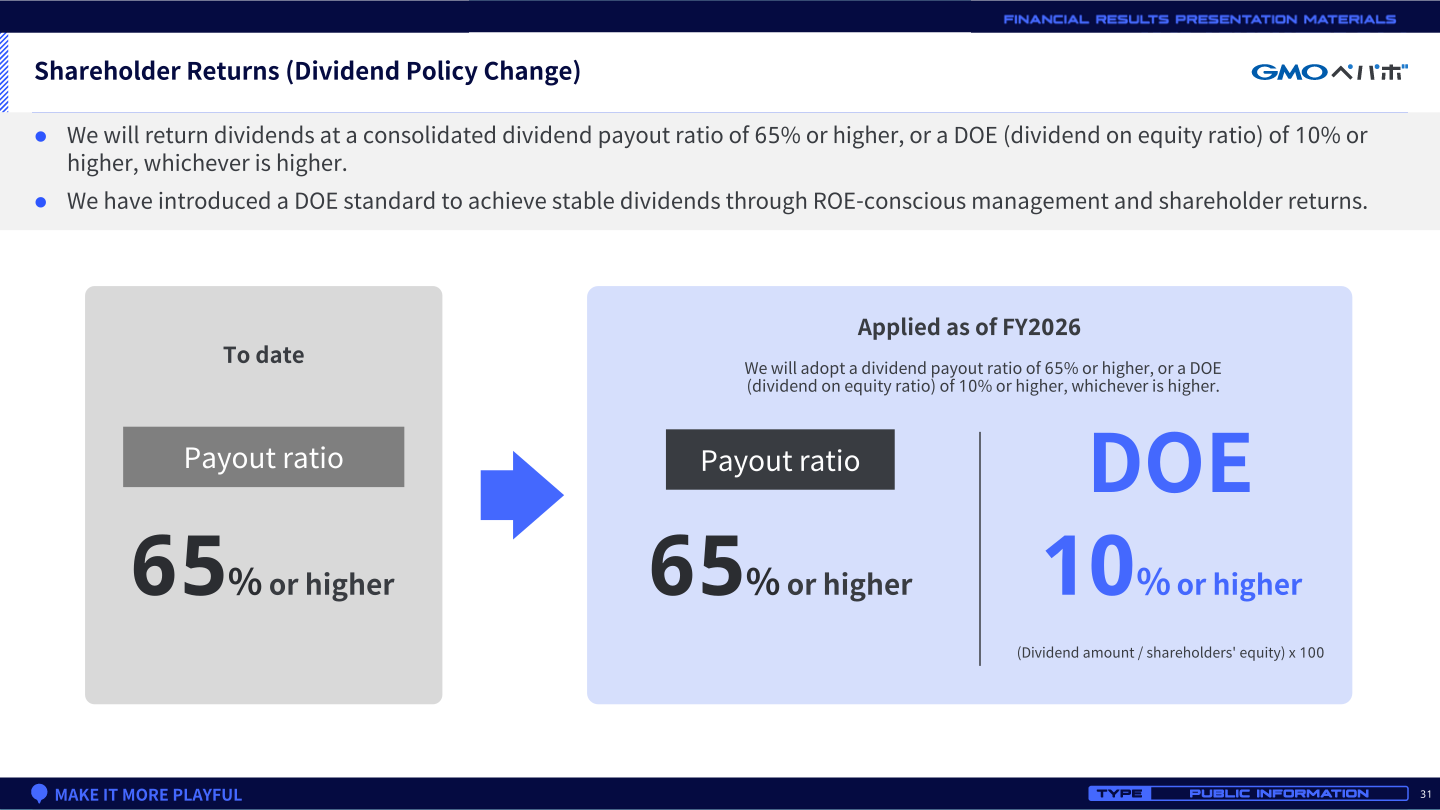
The FY2025 dividend per share was 111.00 yen (ordinary dividend of 67.00 yen plus a special dividend of 44.00 yen), with a payout ratio of 65.8%. For FY2026, the company forecasts a dividend of 93.00 yen per share (payout ratio of 65.3%), an increase from 67 yen to 93 yen based on the ordinary dividend excluding the special dividend. As of FY2026, the company has changed its basic dividend policy from a payout ratio of 65% or higher to a consolidated dividend payout ratio of 65% or higher or a DOE (dividend on equity ratio) of 10% or higher, whichever is higher, introducing the DOE standard to achieve stable dividends through ROE-conscious management.
| Item | FY2024 | FY2025 | FY2026 (Forecast) |
|---|---|---|---|
| Dividends per share (yen) | 57.00 | 111.00 | 93.00 |
| Ordinary dividend (yen) | 57.00 | 67.00 | 93.00 |
| Special dividend (yen) | 0 | 44.00 | 0 |
| Payout ratio (%) | 50.8 | 65.8 | 65.3 |
Medium-Term Policy
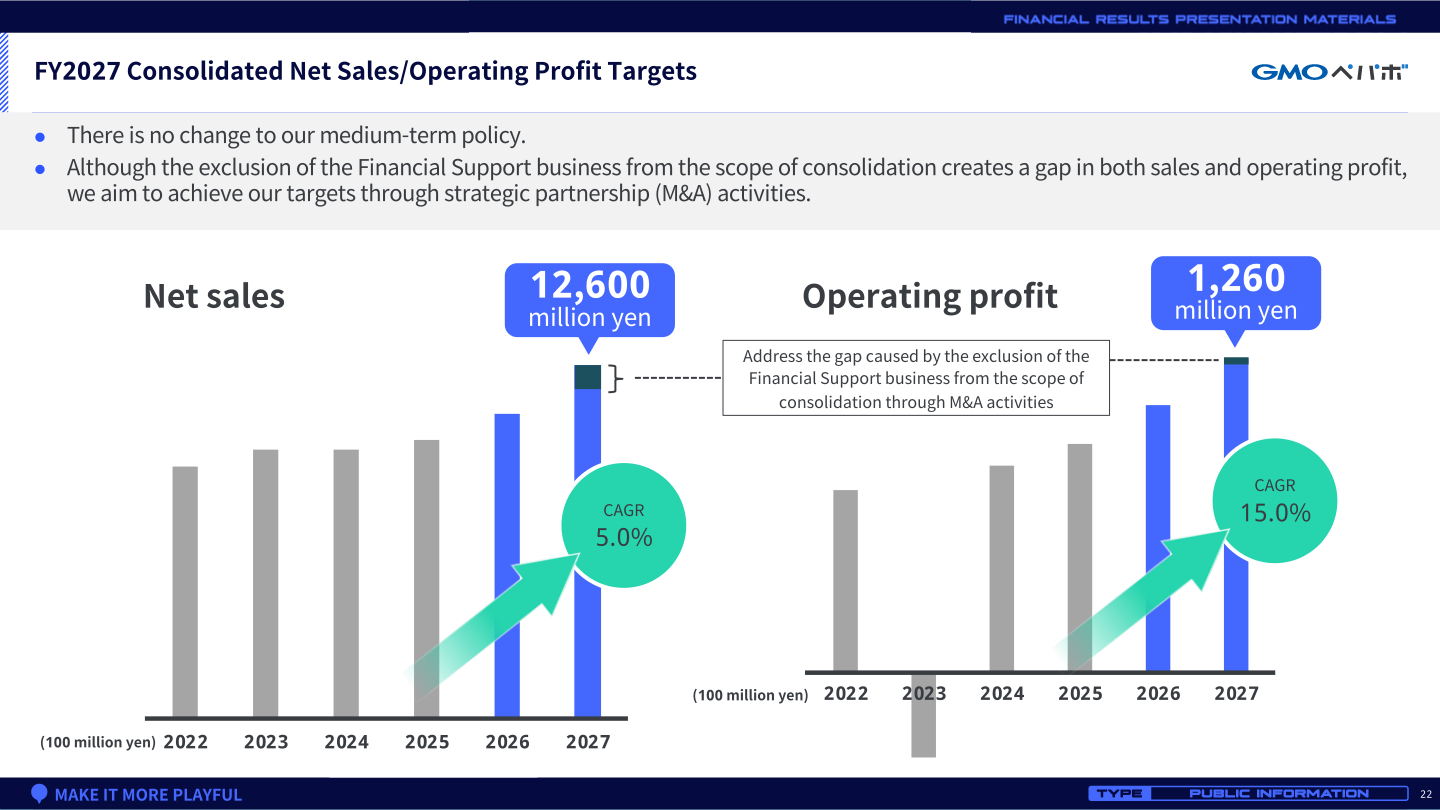
The company states there is no change to its medium-term policy, which targets consolidated net sales of 12,600 million yen (CAGR 5.0%) and operating profit of 1,260 million yen (CAGR 15.0%) in FY2027. Although the exclusion of the Financial Support business from the scope of consolidation creates a gap in both sales and operating profit, the company aims to achieve the targets through strategic partnership (M&A) activities, executing agile M&A at a scale of 3 billion yen in recurring-type businesses across the Domain and Rental Server (Hosting), EC/EC-related services and new areas.
In response to environmental changes driven by AI utilization and corporate DX, the company will expand high-value-added and AI-utilizing services for enterprise customers: expanding sales of Lolipop Static IP (2,200 licenses as of December 31, 2025, with an aim of over 8,000 cumulative licenses by 2026), offering MuuMuu Domain-related options such as MuuMuu Server and Google Workspace, and strengthening sales negotiations for GMO SOKURESU AI, which provides AI chatbot and AI agent introduction support.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















