
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
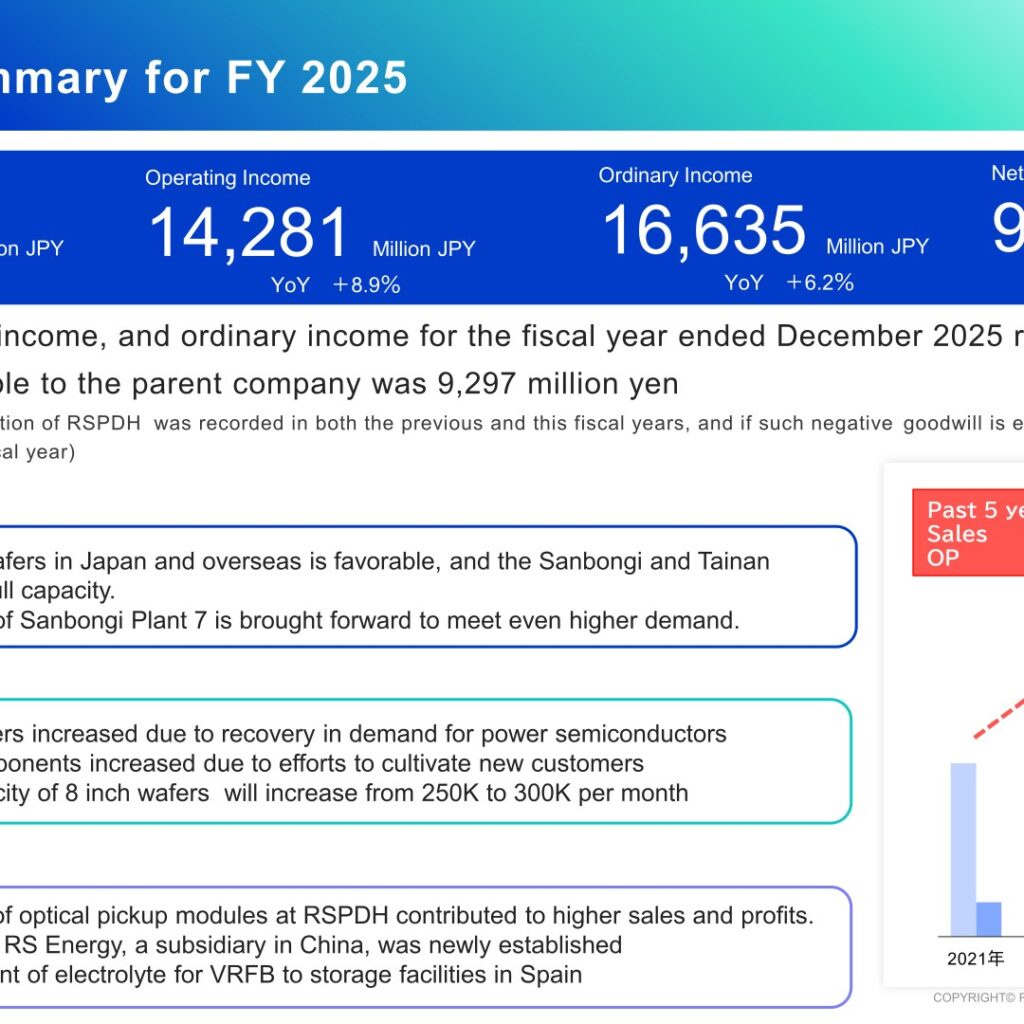
On February 13, 2026, RS Technologies Co., Ltd. released its financial results presentation for FY2025/12 (the fiscal year ended December 2025). Net sales, operating income and ordinary income reached record highs: sales were 76,707 million JPY (YoY +29.6%), operating income 14,281 million JPY (YoY +8.9%) and ordinary income 16,635 million JPY (YoY +6.2%). Net income attributable to the parent company was 9,297 million JPY (YoY △1.6%). The company states that negative goodwill due to the acquisition of RSPDH was recorded in both the previous and this fiscal years, and if such negative goodwill is eliminated, net income increased by 984 million JPY from the previous fiscal year.
Consolidated Results (Full-Year Actual)
According to the presentation, demand for reclaimed wafers in Japan and overseas was favorable, and the Sanbongi and Tainan plants operated at full capacity. Shipments of 8 inch wafers increased due to recovery in demand for power semiconductors, shipments of silicon components increased through efforts to cultivate new customers, and accelerated production of optical pickup modules at RSPDH contributed to higher sales and profits. Gross profit rose 21.7% to 23,585 million JPY, while SGA increased 48.3% to 9,303 million JPY.
In non-operating items, subsidy income (Gritek) rose from JPY 1.1 billion to JPY 2.1 billion, while a foreign exchange gain of JPY 726 million in the previous year turned into a foreign exchange loss of JPY 88 million. Equity in investment loss related to SGRS (the 12 inch prime wafer business in China) increased from JPY 685 million to JPY 1 billion; the company describes this as an investment phase that anticipates business growth.
| Item (Million JPY) | FY2025 | FY2024 | YoY | Difference |
|---|---|---|---|---|
| Net Sales | 76,707 | 59,200 | 29.6% | 17,507 |
| Cost of Sales | 53,122 | 39,820 | 33.4% | 13,302 |
| Gross Profit | 23,585 | 19,380 | 21.7% | 4,205 |
| SGA | 9,303 | 6,271 | 48.3% | 3,032 |
| Operating Income | 14,281 | 13,108 | 8.9% | 1,173 |
| Non-operating Income | 3,766 | 3,392 | 11.0% | 374 |
| Non-operating Expense | 1,412 | 833 | 69.5% | 579 |
| Ordinary Income | 16,635 | 15,668 | 6.2% | 967 |
| Net income attributable to owners of parent | 9,297 | 9,446 | △1.6% | △149 |
| Net Income per share (yen) | 351.40 | 358.21 | △1.9% | △6.8 |
On the balance sheet, total assets were 205,222 million JPY (FY2024: 182,146 million JPY), cash and deposits 96,771 million JPY and net assets 153,331 million JPY. Cash flows from operating activities were 14,836 million JPY, cash flows from investing activities △15,223 million JPY and cash from financing activities 10,302 million JPY. DER was 0.32x (FY2024: 0.20x) and Net D/E was △0.51x.
Segment Results
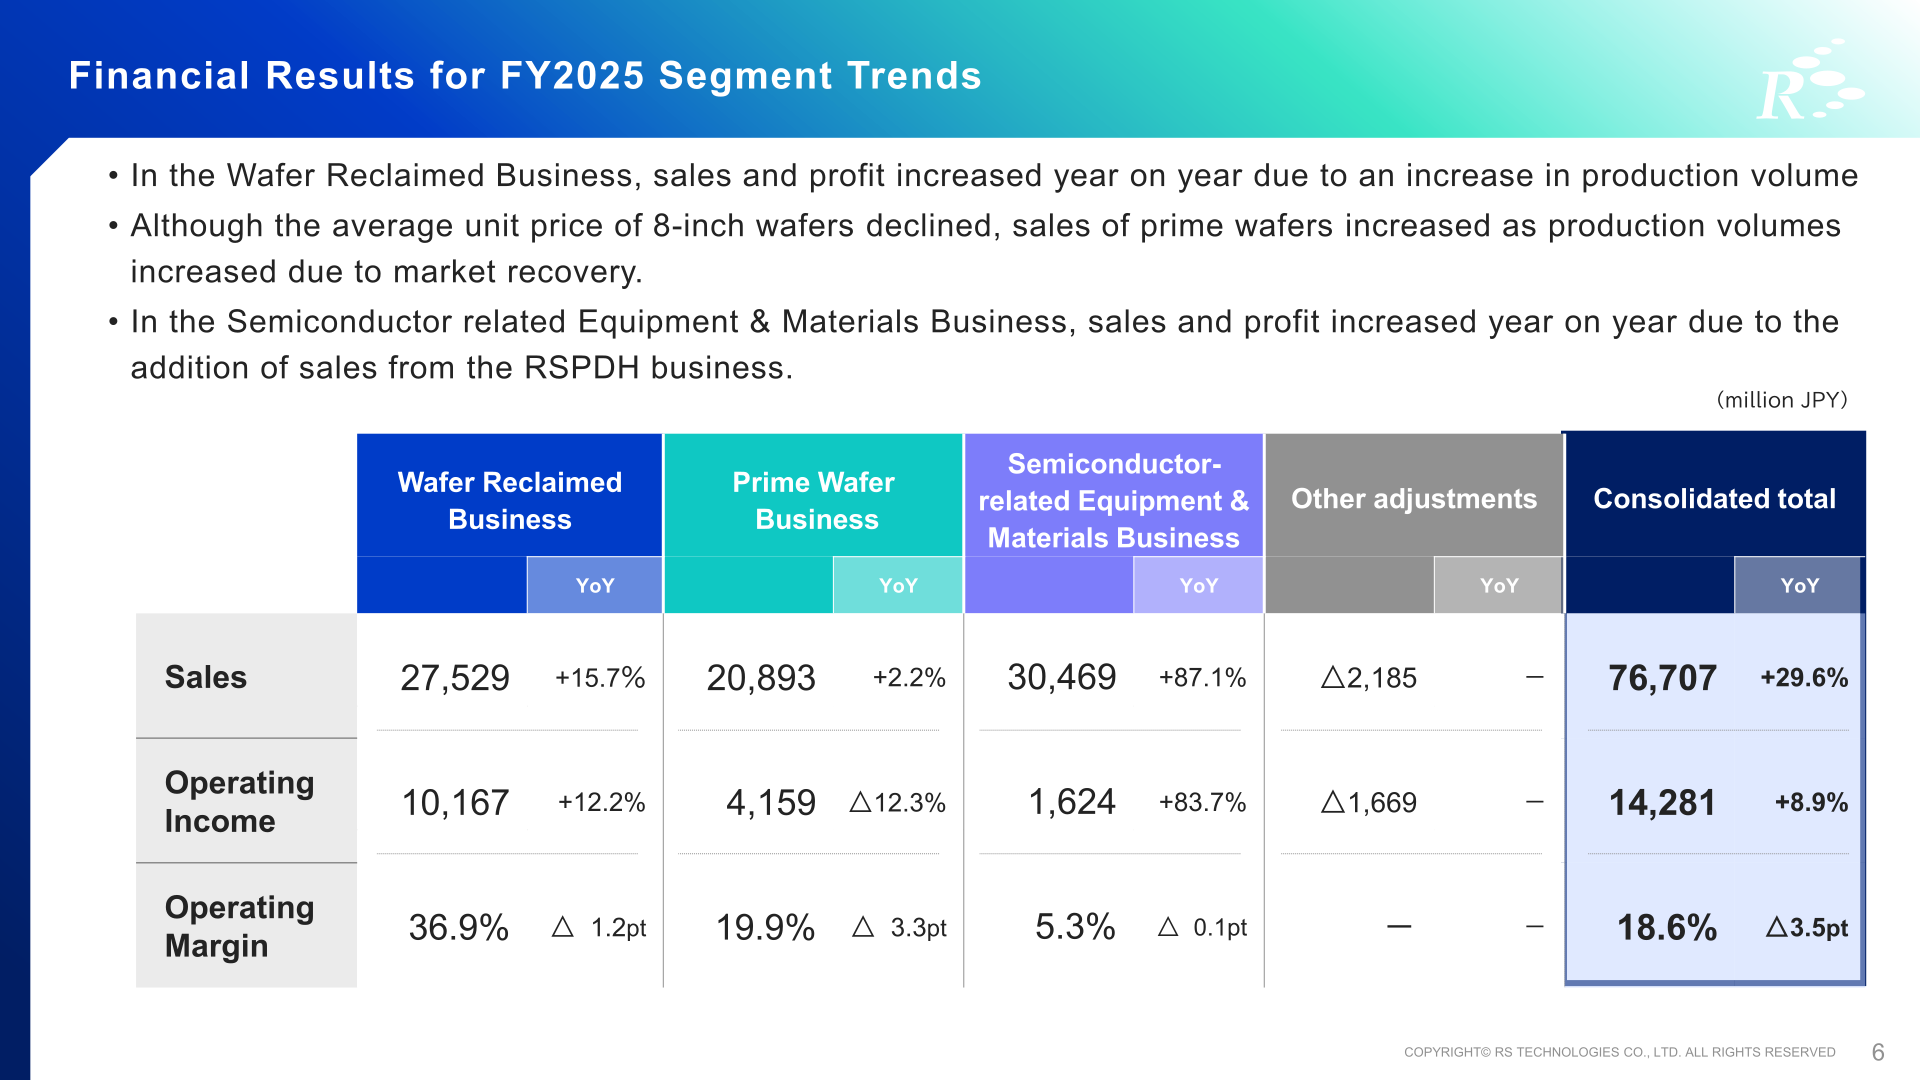
In the Wafer Reclaimed Business, sales and profit increased year on year due to an increase in production volume. In the Prime Wafer Business, although the average unit price of 8-inch wafers declined, sales increased as production volumes rose due to market recovery, while operating income decreased. In the Semiconductor-related Equipment & Materials Business, sales and profit increased year on year due to the addition of sales from the RSPDH business.
| Segment (Million JPY) | Sales | YoY | Operating Income | YoY | Operating Margin | YoY |
|---|---|---|---|---|---|---|
| Wafer Reclaimed Business | 27,529 | +15.7% | 10,167 | +12.2% | 36.9% | △1.2pt |
| Prime Wafer Business | 20,893 | +2.2% | 4,159 | △12.3% | 19.9% | △3.3pt |
| Semiconductor-related Equipment & Materials Business | 30,469 | +87.1% | 1,624 | +83.7% | 5.3% | △0.1pt |
| Other adjustments | △2,185 | - | △1,669 | - | - | - |
| Consolidated total | 76,707 | +29.6% | 14,281 | +8.9% | 18.6% | △3.5pt |
Within the Wafer Reclaimed Business, sales of reclaimed wafers were 18,105 million JPY and sales wafers 9,423 million JPY in 2025. In the Prime Wafer Business, the FY2025 sales mix was 70% prime wafers (5, 6 and 8 inch) and 30% silicon parts.
FY2026 Forecast and Medium-Term Management Plan (2026-2028)
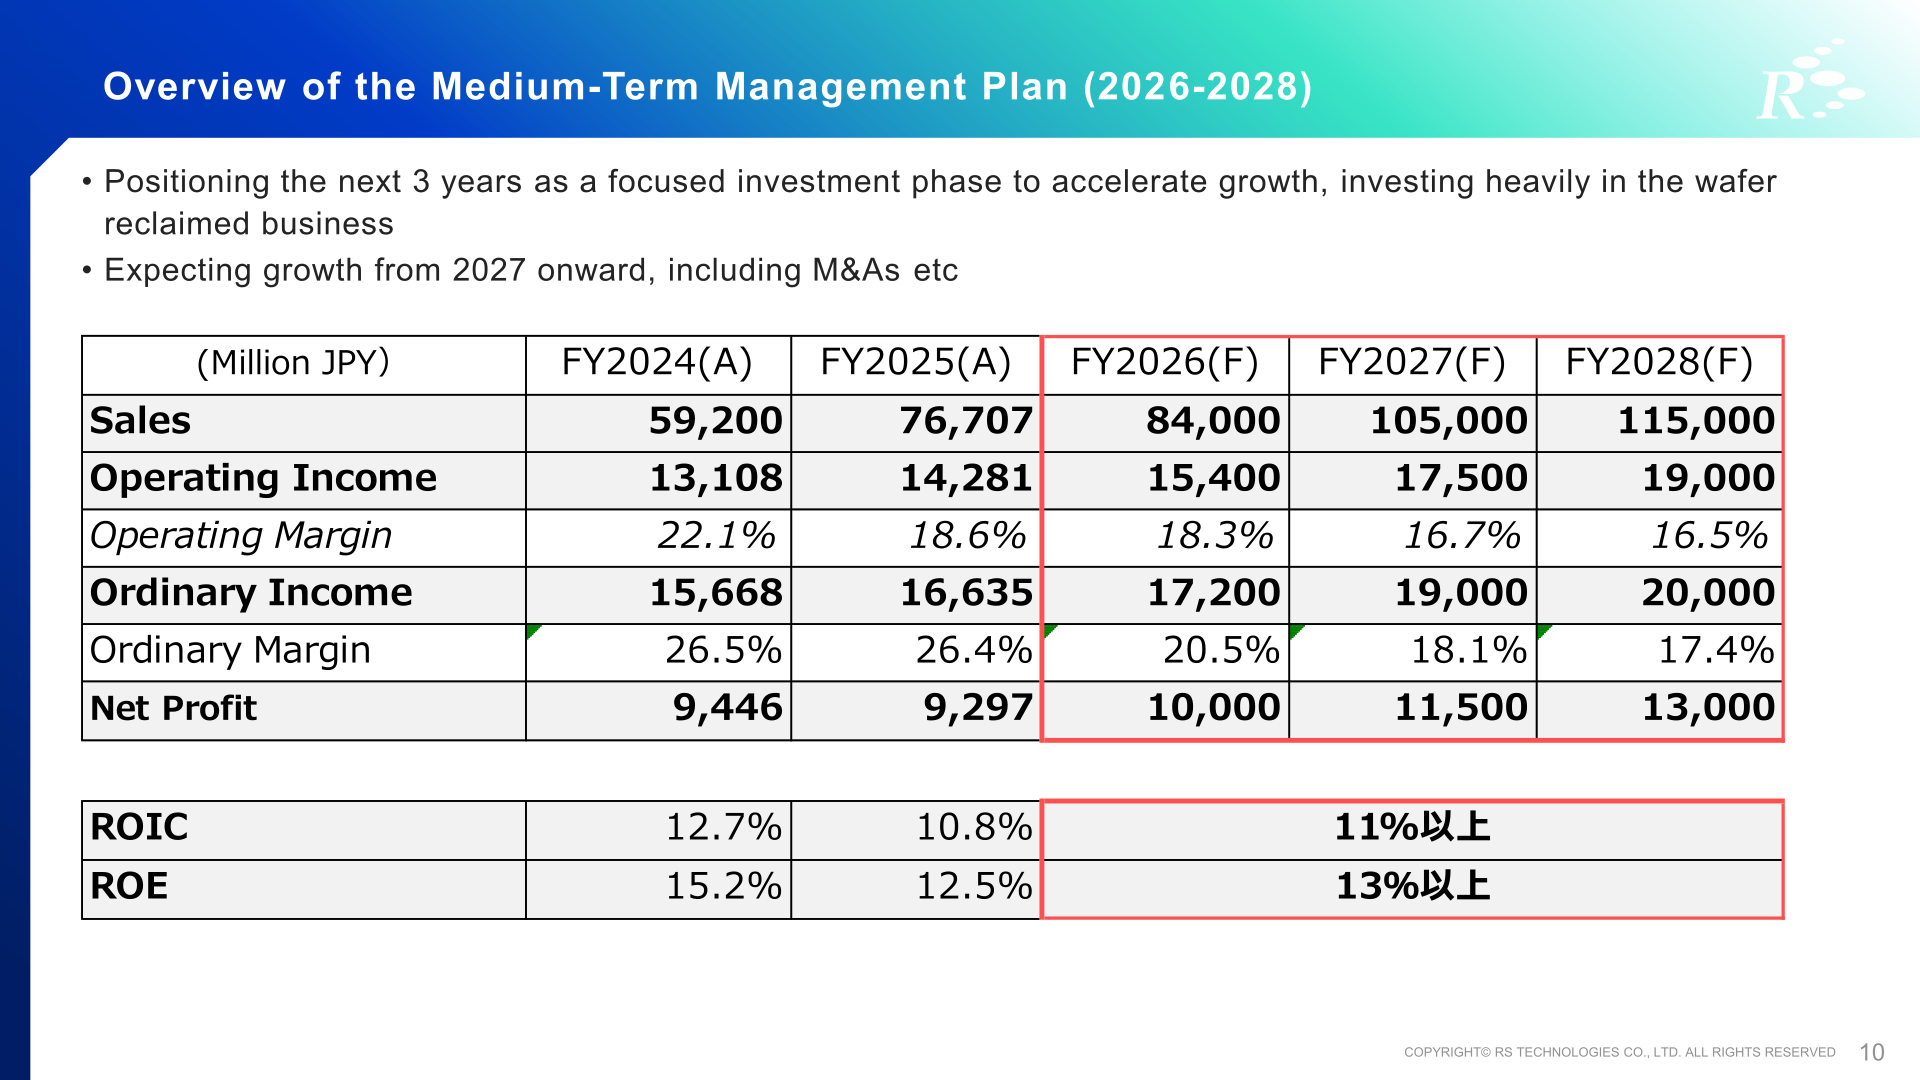
The company positions the next three years as a focused investment phase to accelerate growth, investing heavily in the wafer reclaimed business, and expects growth from 2027 onward, including M&As. For FY2026 it forecasts sales of 84,000 million JPY, operating income of 15,400 million JPY, ordinary income of 17,200 million JPY and net profit of 10,000 million JPY. The plan targets ROIC of 11% or more and ROE of 13% or more for 2026-2028 (FY2025 actual: ROIC 10.8%, ROE 12.5%).
| Item (Million JPY) | FY2025 (A) | FY2026 (F) | FY2027 (F) | FY2028 (F) |
|---|---|---|---|---|
| Sales | 76,707 | 84,000 | 105,000 | 115,000 |
| Operating Income | 14,281 | 15,400 | 17,500 | 19,000 |
| Operating Margin | 18.6% | 18.3% | 16.7% | 16.5% |
| Ordinary Income | 16,635 | 17,200 | 19,000 | 20,000 |
| Ordinary Margin | 26.4% | 20.5% | 18.1% | 17.4% |
| Net Profit | 9,297 | 10,000 | 11,500 | 13,000 |
For cash allocation over 2026-2028, the company expects cumulative operating cash flows of 53 billion JPY on top of net cash of 73.3 billion JPY (2025) and 3.4 billion JPY from the sale of a portion of an overseas subsidiary’s shares. It plans capital investment in existing business of 57 billion JPY, strategic investment of 36.5 billion JPY and shareholders’ return of 7.5 billion JPY (including GRITEK and others dividend), with business continuity working capital of 28.7 billion JPY. Planned investment in reclaimed wafers includes 40.5 billion JPY of plant capital investment (Japan, Taiwan, China).
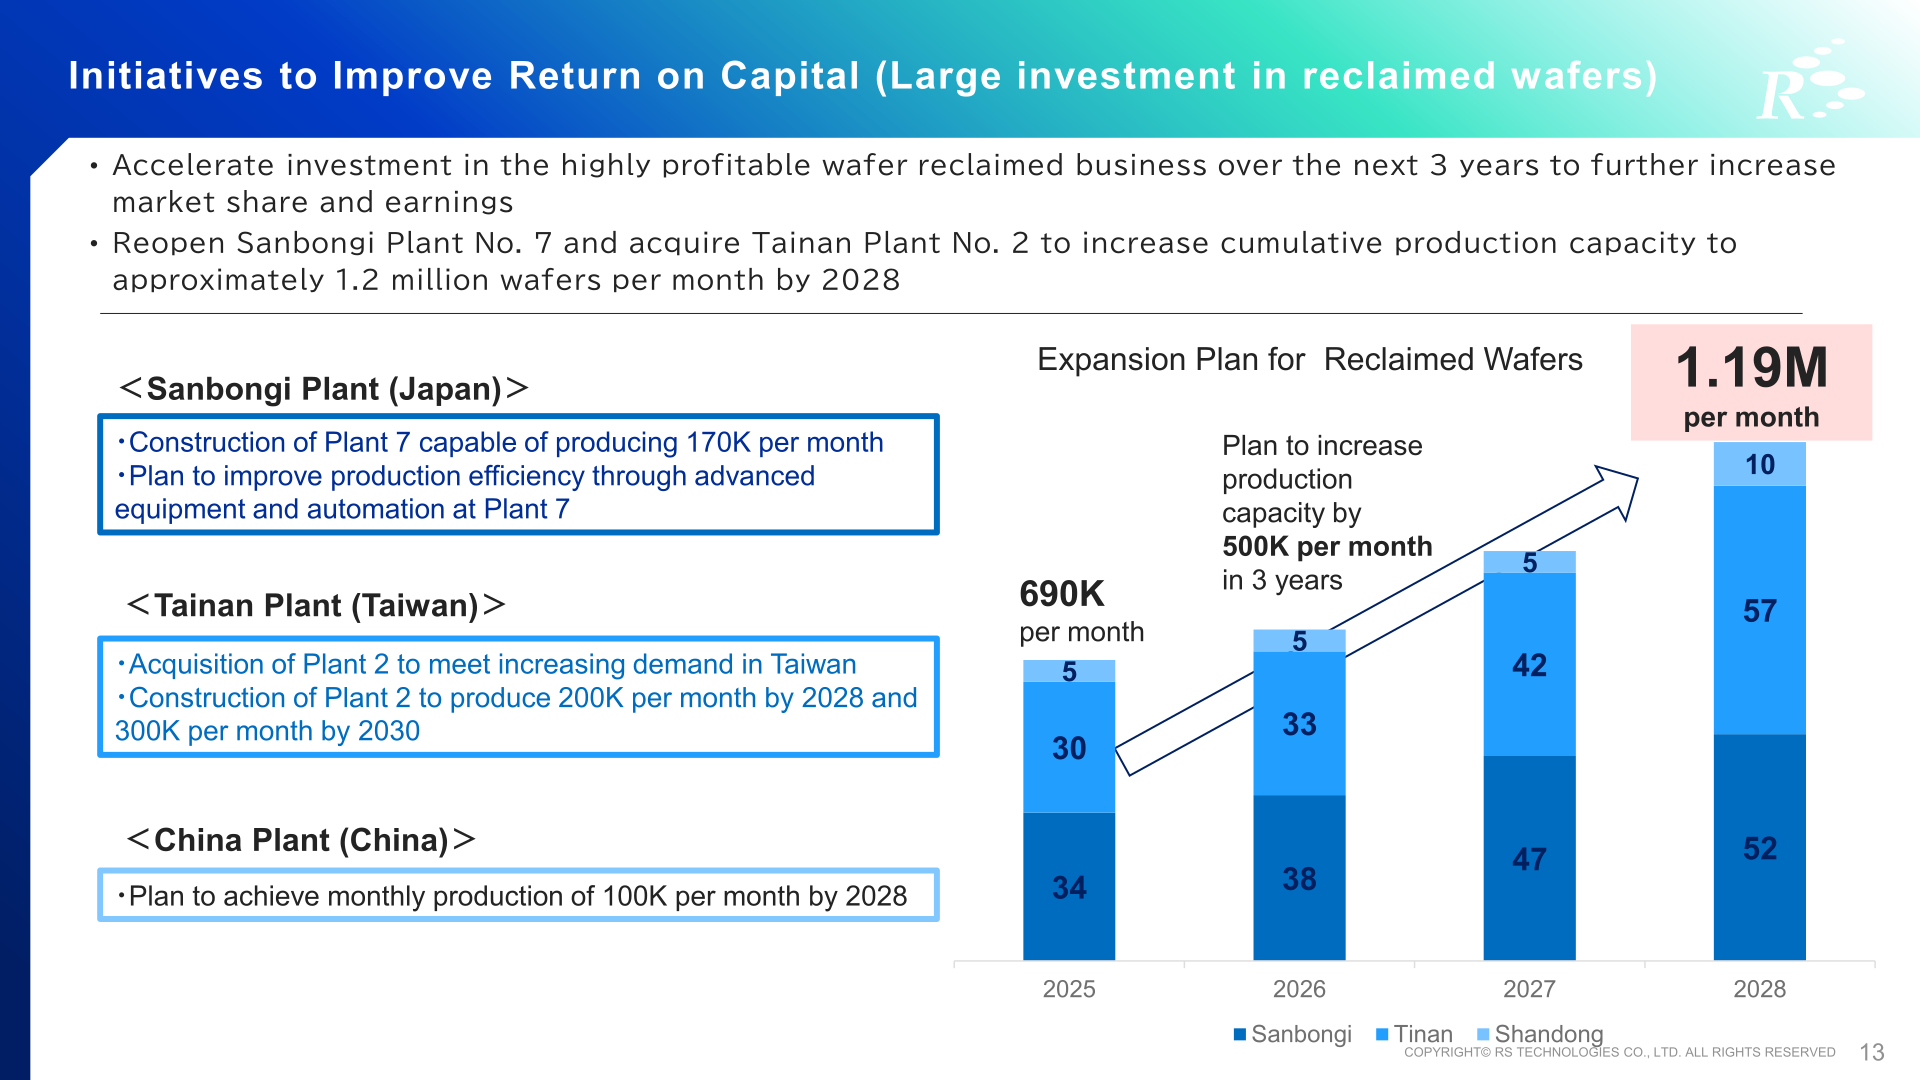
The company plans to reopen Sanbongi Plant No. 7 and acquire Tainan Plant No. 2, raising reclaimed wafer production capacity from 690K per month to 1.19M per month by 2028, an increase of 500K per month in three years. Total investment is 17.3 billion JPY+ in Japan, 24.7 billion JPY in Taiwan and 10 billion JPY in China. In the Prime Wafer Business, production capacity for 8 inch prime wafers will reach 300K per month in 2026, and capacity for 12 inch prime wafers will increase to 250K per month in 2028 (the 12 inch business will be invested by an equity method affiliate).
Shareholder Returns
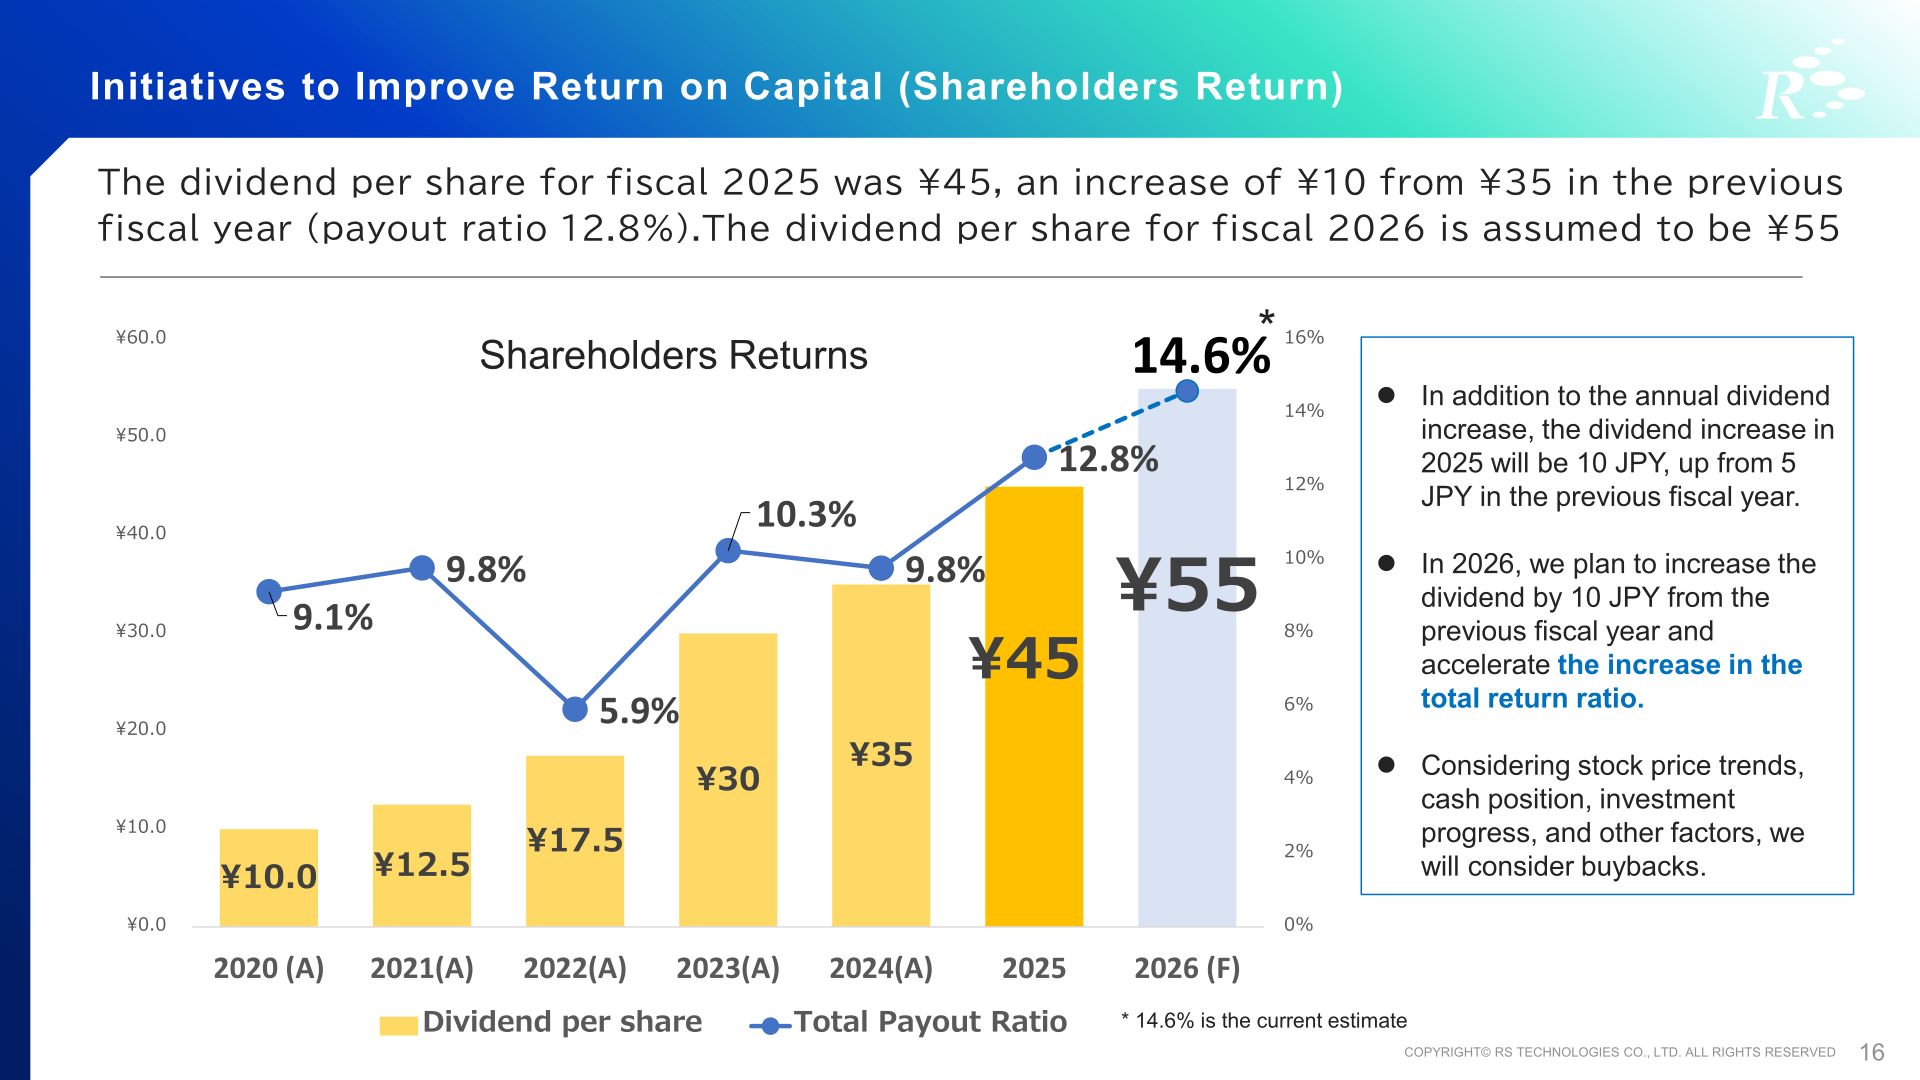
The dividend per share for fiscal 2025 was ¥45, an increase of ¥10 from ¥35 in the previous fiscal year (payout ratio 12.8%). The dividend per share for fiscal 2026 is assumed to be ¥55, an increase of 10 JPY, and the company plans to accelerate the increase in the total return ratio. It also states that it will consider buybacks, considering stock price trends, cash position, investment progress, and other factors.
| Item | FY2024 (A) | FY2025 | FY2026 (F) |
|---|---|---|---|
| Dividend per share | ¥35 | ¥45 | ¥55 |
| Total Payout Ratio | 9.8% | 12.8% | 14.6% (current estimate) |
Topics
In the energy business, RS Energy, a subsidiary in China, was newly established in June 2025, and the company made its first commercial shipment of electrolyte for VRFB to storage facilities in Spain. A completion ceremony for the Panzhihua Plant in China, established as a joint venture with a partner company, was held on January 28, 2026, with operation targeted to start in 2026. The company estimates its global market share in the reclaimed wafer business at 31%, based on SEMI data.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















