
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: YOKOREI does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. “FY2025” in the title follows this site’s convention for the most recent completed fiscal year; the materials label it the fiscal year ended September 2025 (the 78th fiscal term).
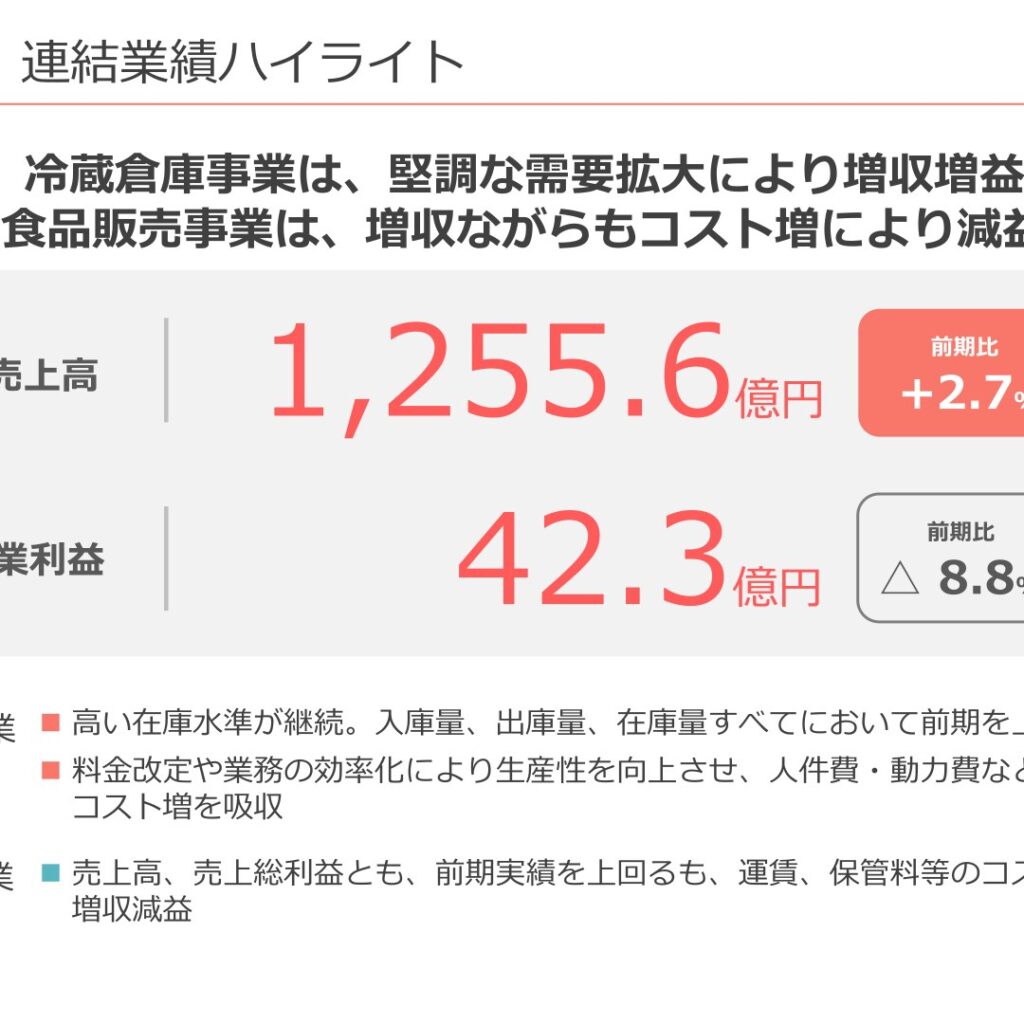
YOKOREI’s consolidated results for the fiscal year ended September 2025 (the 78th term) were net sales of 125,563 million yen (+2.7% year on year, 125.56 billion yen), operating profit of 4,238 million yen (△8.8% year on year, 4.23 billion yen), ordinary profit of 3,658 million yen (△23.9% year on year) and profit attributable to owners of parent of 1,978 million yen (△49.7% year on year) — higher sales but lower profit. The Refrigerated Warehousing Business posted increases in both sales and profit on solid demand expansion, while the Food Sales Business increased sales but saw profit decline because it could not fully absorb higher freight, storage and other costs. Against the full-year forecast (net sales of 127,000 million yen, operating profit of 4,250 million yen), net sales and operating profit came to 98.9% and 99.7% of plan, respectively.
Consolidated Results (Fiscal Year Ended September 2025, Actual)
Net sales were 125,563 million yen (+2.7% year on year) and gross profit was 14,136 million yen (+3.5% year on year, gross margin 11.3%). Operating profit was 4,238 million yen (△8.8% year on year, operating margin 3.4%), ordinary profit was 3,658 million yen (△23.9% year on year) and profit attributable to owners of parent was 1,978 million yen (△49.7% year on year), all down year on year. Capital expenditure was 16,900 million yen (△21.6% year on year), depreciation was 8,263 million yen (+12.2% year on year), EBITDA was 12,501 million yen (+4.1% year on year), and the capital adequacy ratio was 38.6% (+0.1pt year on year).
| Item (millions of yen) | FY ended Sep 2024 | FY ended Sep 2025 | YoY |
|---|---|---|---|
| Net sales | 122,282 | 125,563 | +2.7% |
| Gross profit | 13,664 | 14,136 | +3.5% |
| Operating profit | 4,647 | 4,238 | △8.8% |
| Ordinary profit | 4,808 | 3,658 | △23.9% |
| Profit attributable to owners of parent | 3,933 | 1,978 | △49.7% |
Segment Results
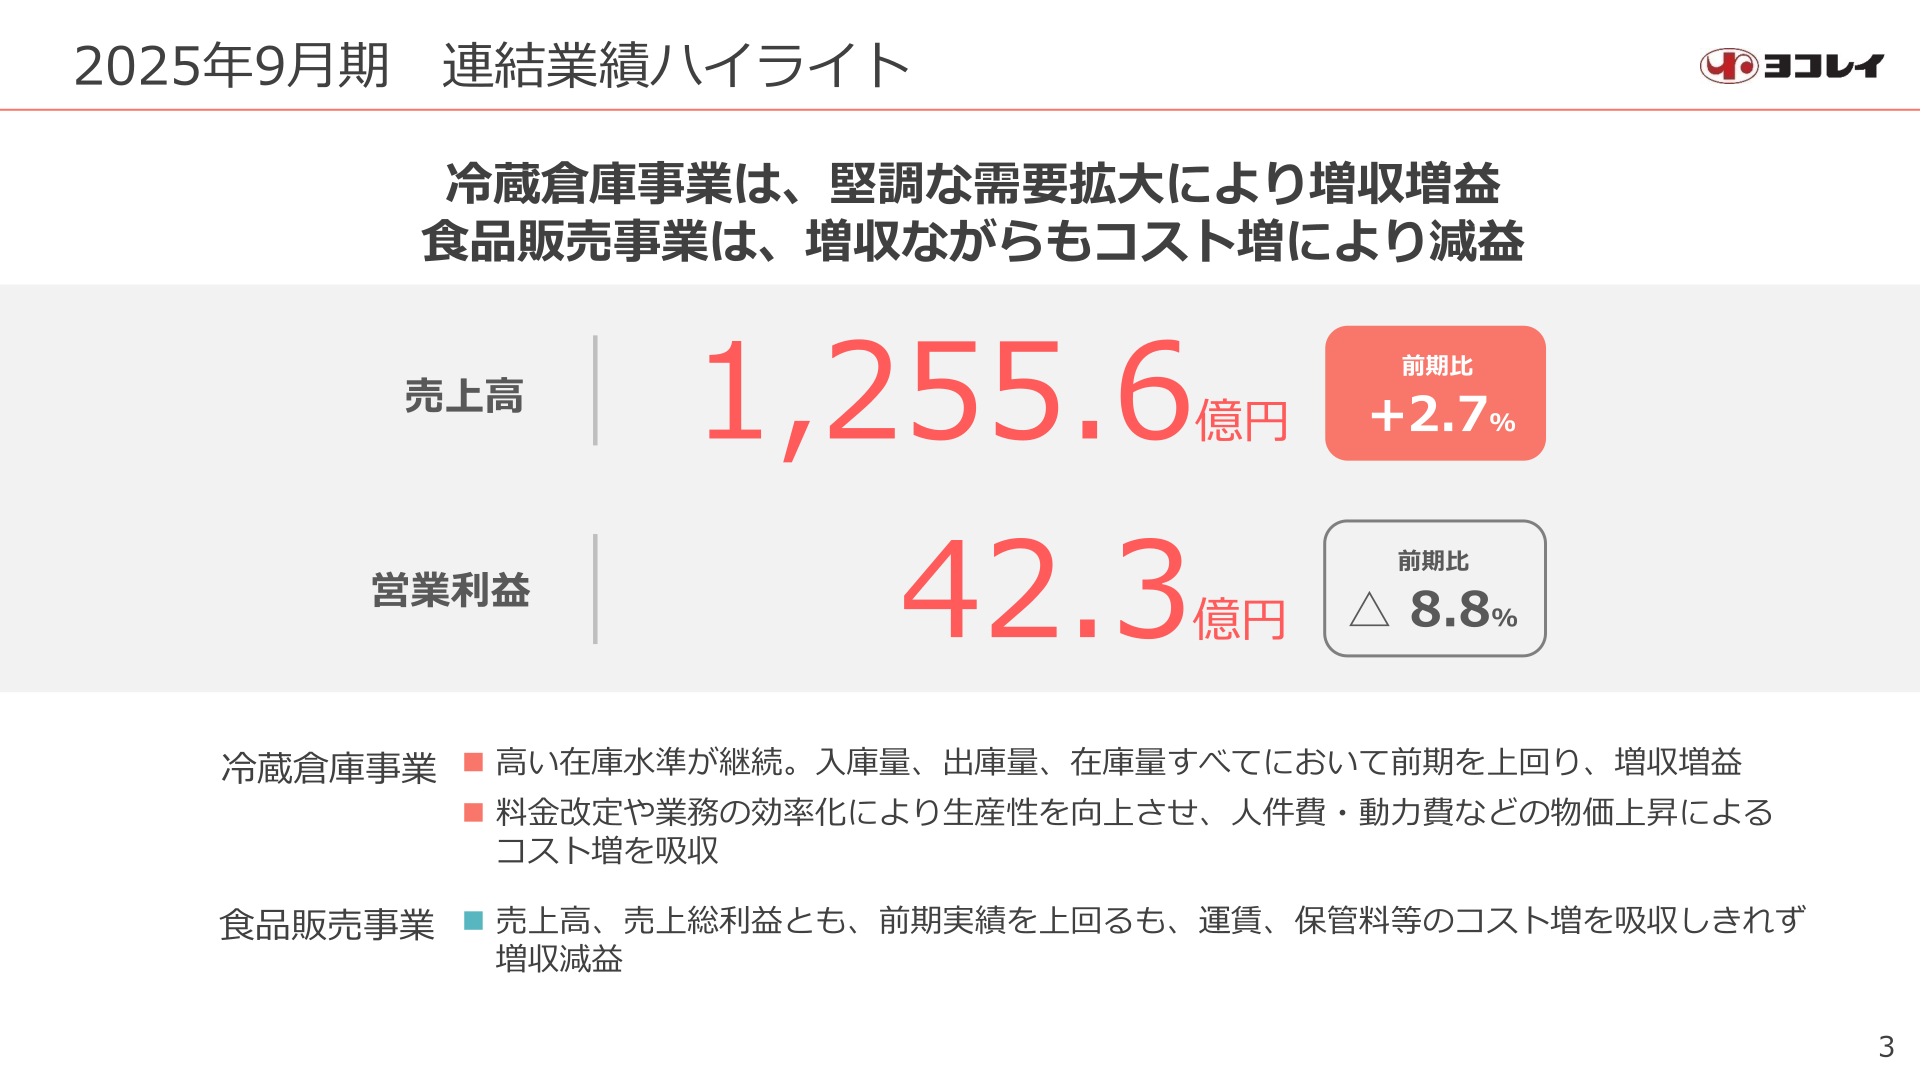
In the Refrigerated Warehousing Business, against a backdrop of solid demand expansion, volumes of goods received, goods shipped and inventory all exceeded the previous fiscal year. Net sales were 37,724 million yen (+7.4% year on year) and segment profit was 7,436 million yen (+3.3% year on year), an increase in both sales and profit. Rate revisions and improved operational efficiency absorbed higher personnel, power and other costs. In the Food Sales Business, net sales rose to 87,807 million yen (+0.8% year on year), helped by higher handling volumes from abundant catches of marine products such as sardines and mackerel, but the business could not fully absorb higher freight, storage and other costs, and segment profit declined to 1,217 million yen (△17.4% year on year). Note that each segment profit is stated before deduction of unallocated operating expenses (expenses relating to administrative divisions).
| Segment | Metric (millions of yen) | FY ended Sep 2024 | FY ended Sep 2025 |
|---|---|---|---|
| Refrigerated Warehousing Business | Net sales | 35,127 | 37,724 |
| Refrigerated Warehousing Business | Segment profit | 7,198 | 7,436 |
| Food Sales Business | Net sales | 87,095 | 87,807 |
| Food Sales Business | Segment profit | 1,473 | 1,217 |
Full-Year Forecast (Fiscal Year Ending September 2026)
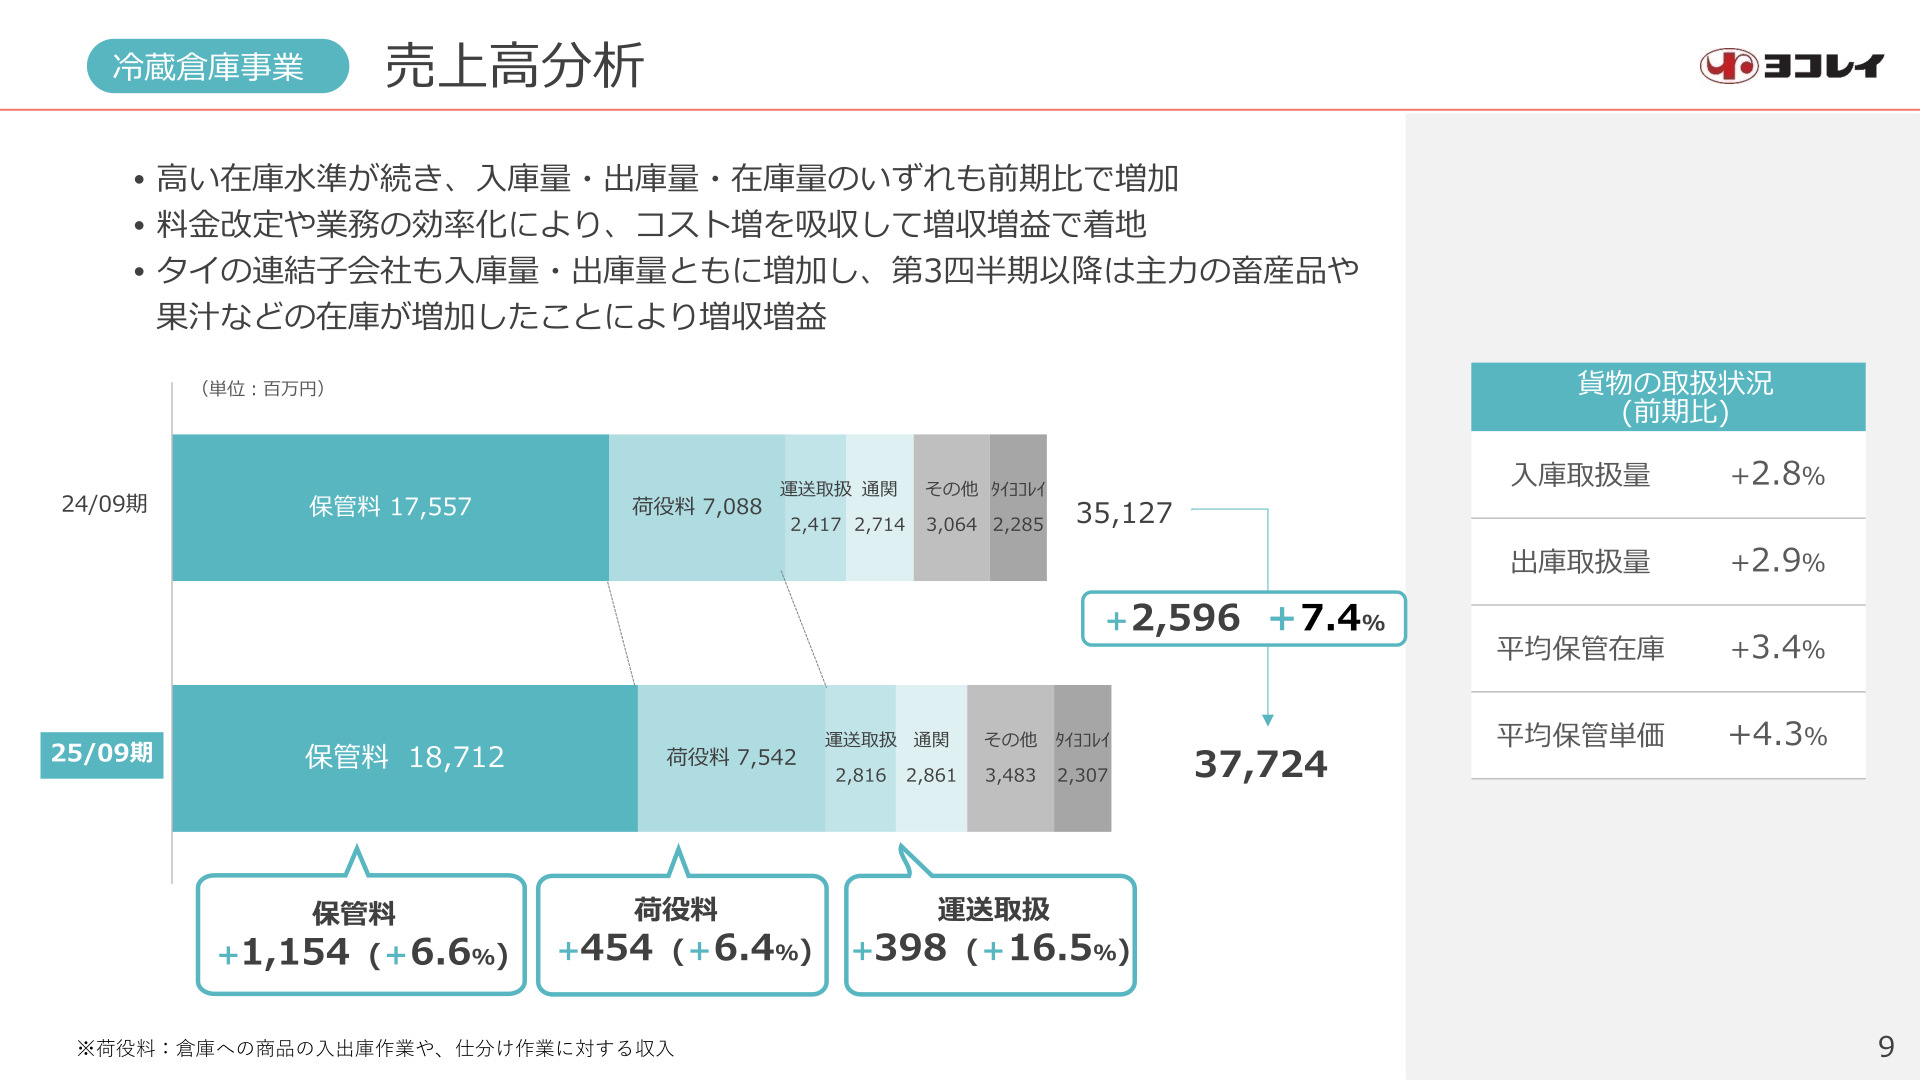
For the fiscal year ending September 2026, the company forecasts net sales of 118,000 million yen (△6.0% year on year), operating profit of 4,800 million yen (+13.3% year on year), ordinary profit of 4,600 million yen (+25.7% year on year) and profit attributable to owners of parent of 3,000 million yen (+51.6% year on year). By shifting the Food Sales Business to a business structure that emphasizes profitability, the company expects double-digit profit growth year on year despite lower sales. By segment, it expects the Refrigerated Warehousing Business to post net sales of 38,000 million yen (+0.7% year on year) and operating profit of 7,300 million yen (△1.8% year on year), and the Food Sales Business to post net sales of 80,000 million yen (△8.9% year on year) and operating profit of 1,800 million yen (+47.9% year on year).
| Item (millions of yen) | FY ended Sep 2025 (Actual) | FY ending Sep 2026 (Forecast) | YoY |
|---|---|---|---|
| Net sales | 125,563 | 118,000 | △6.0% |
| Refrigerated Warehousing Business | 37,724 | 38,000 | +0.7% |
| Food Sales Business | 87,807 | 80,000 | △8.9% |
| Operating profit | 4,238 | 4,800 | +13.3% |
| Ordinary profit | 3,658 | 4,600 | +25.7% |
| Profit attributable to owners of parent | 1,978 | 3,000 | +51.6% |
Shareholder Returns
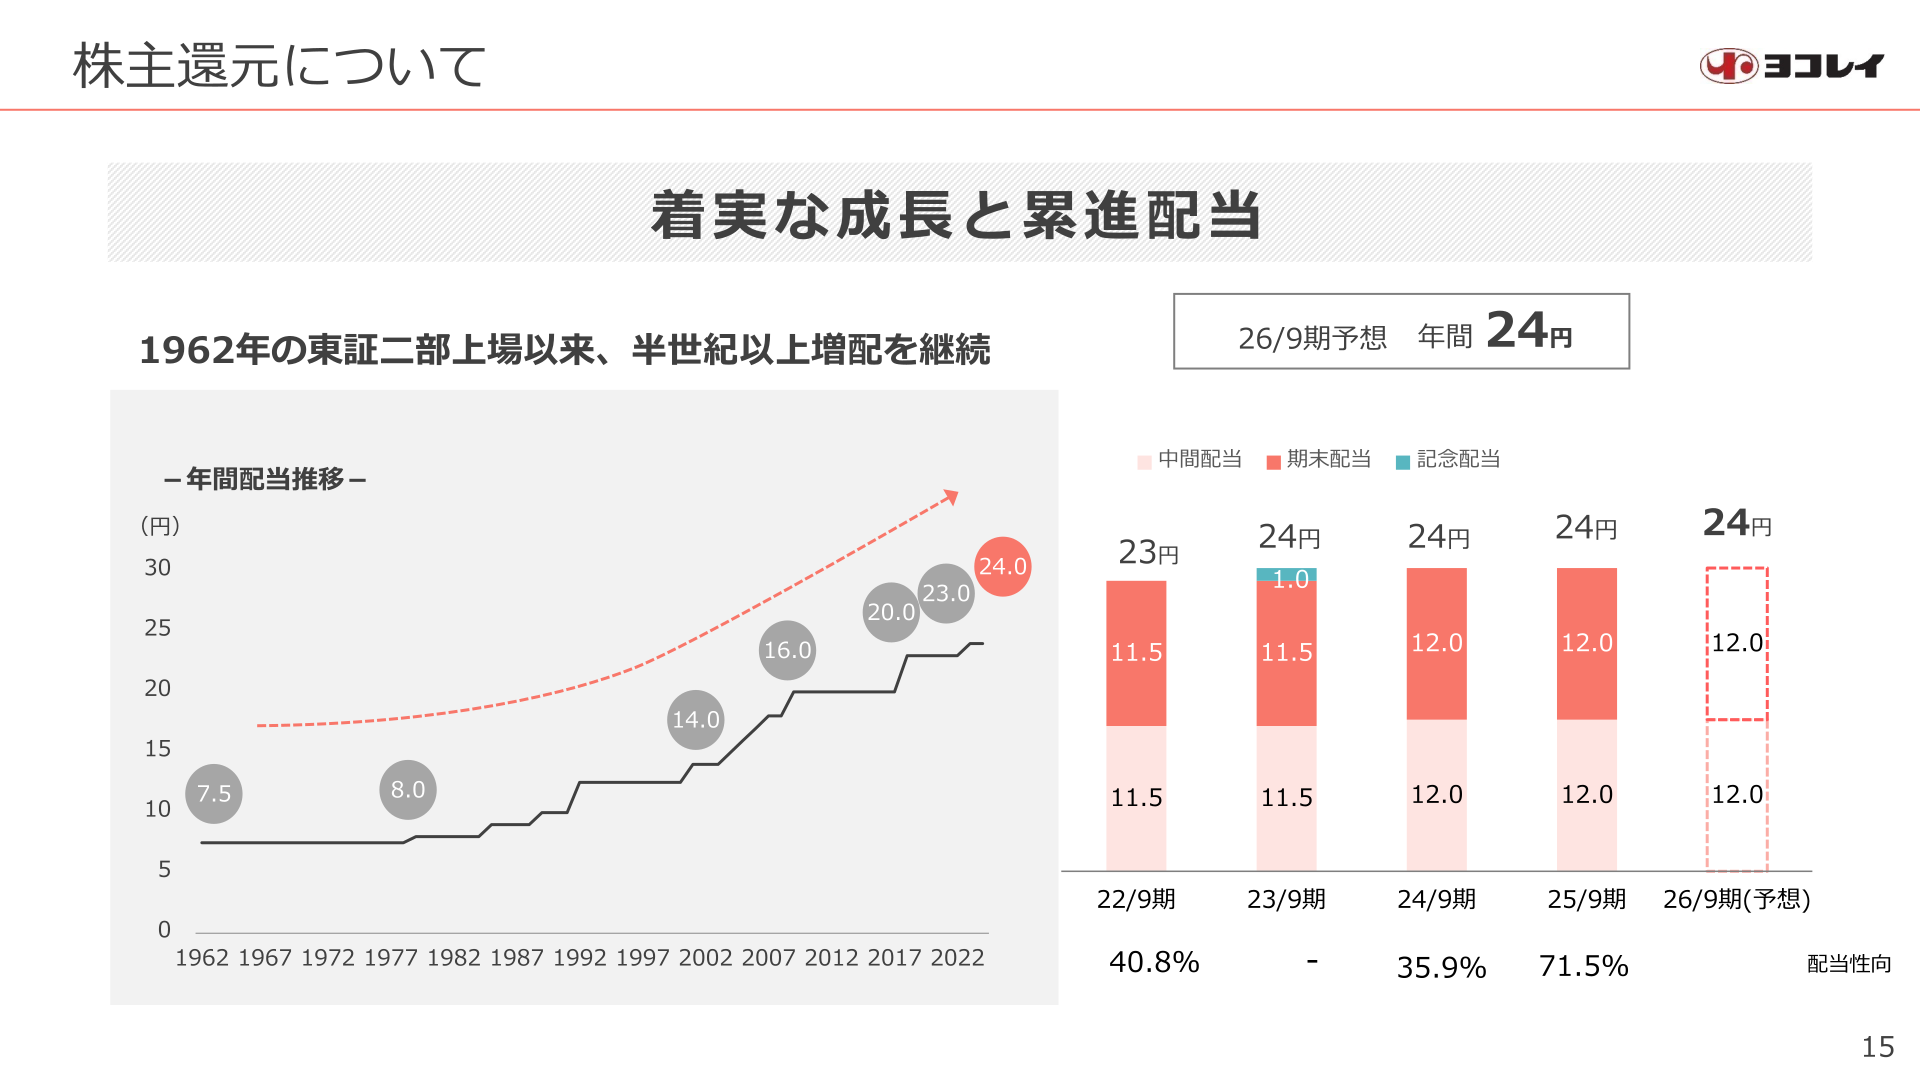
On shareholder returns, the company states that it has continued to increase its dividend for more than half a century since its listing on the Second Section of the Tokyo Stock Exchange in 1962, and it forecasts an annual dividend of 24 yen for the fiscal year ending September 2026. The payout ratio was 35.9% for the fiscal year ended September 2024 and 71.5% for the fiscal year ended September 2025, and is projected at 40.8% for the fiscal year ending September 2026.
| Item | FY ended Sep 2024 | FY ended Sep 2025 | FY ending Sep 2026 (Forecast) |
|---|---|---|---|
| Annual dividend | 24 yen | 24 yen | 24 yen |
| Payout ratio | 35.9% | 71.5% | 40.8% |
Progress of the Medium-Term Management Plan
Regarding the medium-term management plan, the company revised its numerical targets to factor in the impact of cost increases and of the structural reform of the Food Sales Business. In the Refrigerated Warehousing Business, segment operating profit is expected to fall short of the initial plan because increased depreciation accompanying soaring construction costs and rising energy costs ran above the assumed level. In the Food Sales Business, net sales and segment operating profit are expected to fall short of the initial plan due to the review of low-margin transactions, and the company is promoting a shift to a business structure that emphasizes profitability. Among the numerical targets for 2026, the EBITDA target of 13.0 billion yen is unchanged. ROE was lowered from the initial target of “5% or more” to “4% or more,” while the capital adequacy ratio target of “maintaining the 40% level” is unchanged. In addition, in 2025 three facilities were completed — the Ben Luc Logistics Center, the company’s first base in Vietnam, together with the Okayama CONNECT Logistics Center and the Tokachi Food Valley Logistics Center — advancing the expansion of environmentally conscious centers and ASEAN global development.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















