
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
WDB Holdings Co., Ltd. (TSE Prime, 2475) reported FY2025 sales of 50,304 million yen, down 1.6% year on year, with ordinary income of 4,597 million yen (-9.8%) and net income of 2,755 million yen (-9.7%). The Human Resources business grew sales by 1.3% and segment profit by 6.4%, but the CRO business saw sales fall 17.1% and segment profit fall 30.7%, which the company attributes to a major client bringing previously outsourced operations in-house and to the divestiture of unprofitable overseas business. For FY2026 the company forecasts sales of 51,439 million yen (+2.3%) and net income of 2,772 million yen (+0.6%), and it has revised its dividend payout ratio criteria, targeting a payout ratio of 65%.
Consolidated Results (Full-Year Actual)
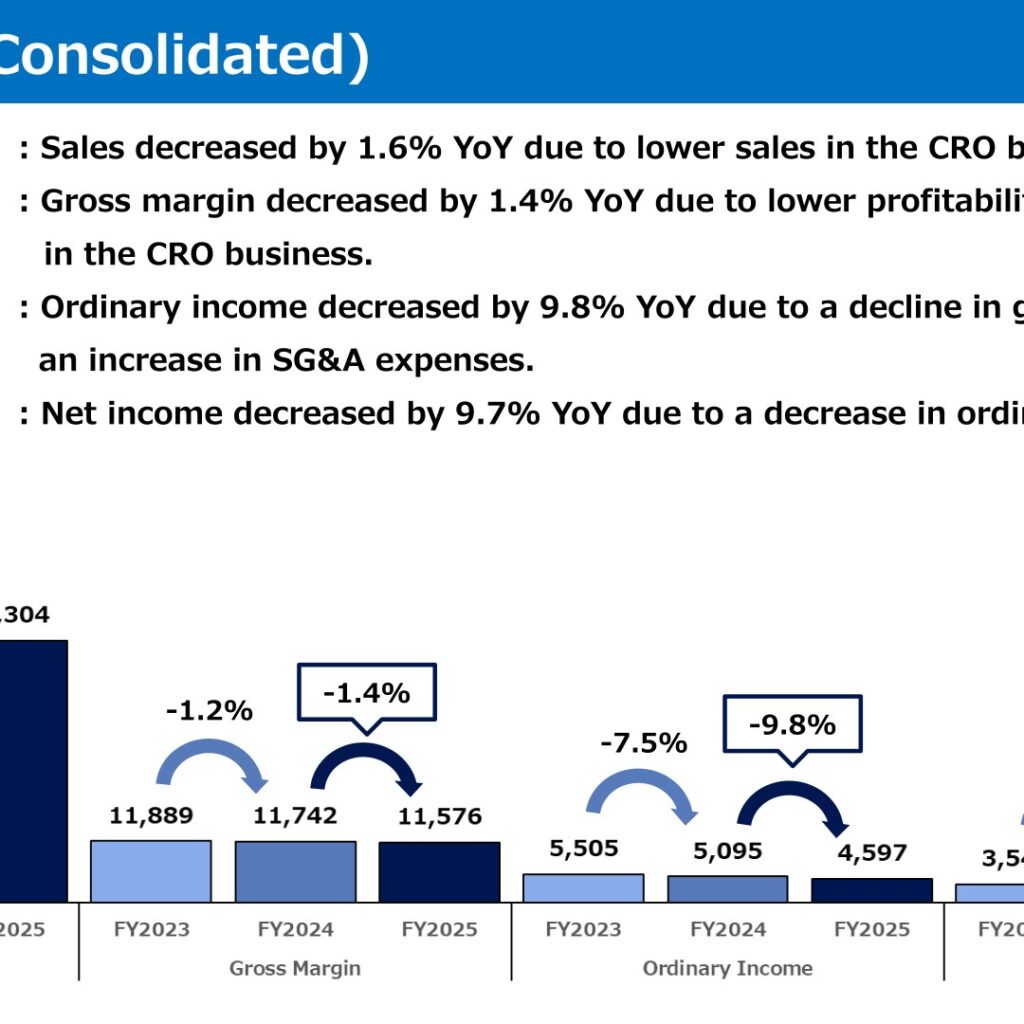
Sales decreased by 831 million yen year on year to 50,304 million yen (-1.6%). Gross margin decreased by 165 million yen to 11,576 million yen (-1.4%), while the gross margin ratio remained unchanged year on year at 23.0%. Ordinary income decreased 498 million yen to 4,597 million yen (-9.8%), with the ordinary income ratio down 0.8 point to 9.1%. Net income decreased by 296 million yen to 2,755 million yen (-9.7%), with the net income ratio down 0.5 point to 5.5%. The company explains that sales fell due to lower sales in the CRO business, gross margin fell due to lower profitability in the CRO business, and ordinary income fell due to the decline in gross margin and an increase in SG&A expenses.
| Item (millions of yen) | FY2025 | Sales ratio | FY2024 | Sales ratio | Increase ratio |
|---|---|---|---|---|---|
| Sales | 50,304 | 100.0% | 51,136 | 100.0% | -1.6% |
| Cost | 38,728 | 77.0% | 39,394 | 77.0% | -1.7% |
| Gross Margin | 11,576 | 23.0% | 11,742 | 23.0% | -1.4% |
| SG(&)A | 7,112 | 14.1% | 6,673 | 13.1% | 6.6% |
| Operating Income | 4,464 | 8.9% | 5,068 | 9.9% | -11.9% |
| Ordinary Income | 4,597 | 9.1% | 5,095 | 10.0% | -9.8% |
| Net Income | 2,755 | 5.5% | 3,051 | 6.0% | -9.7% |
Segment Results
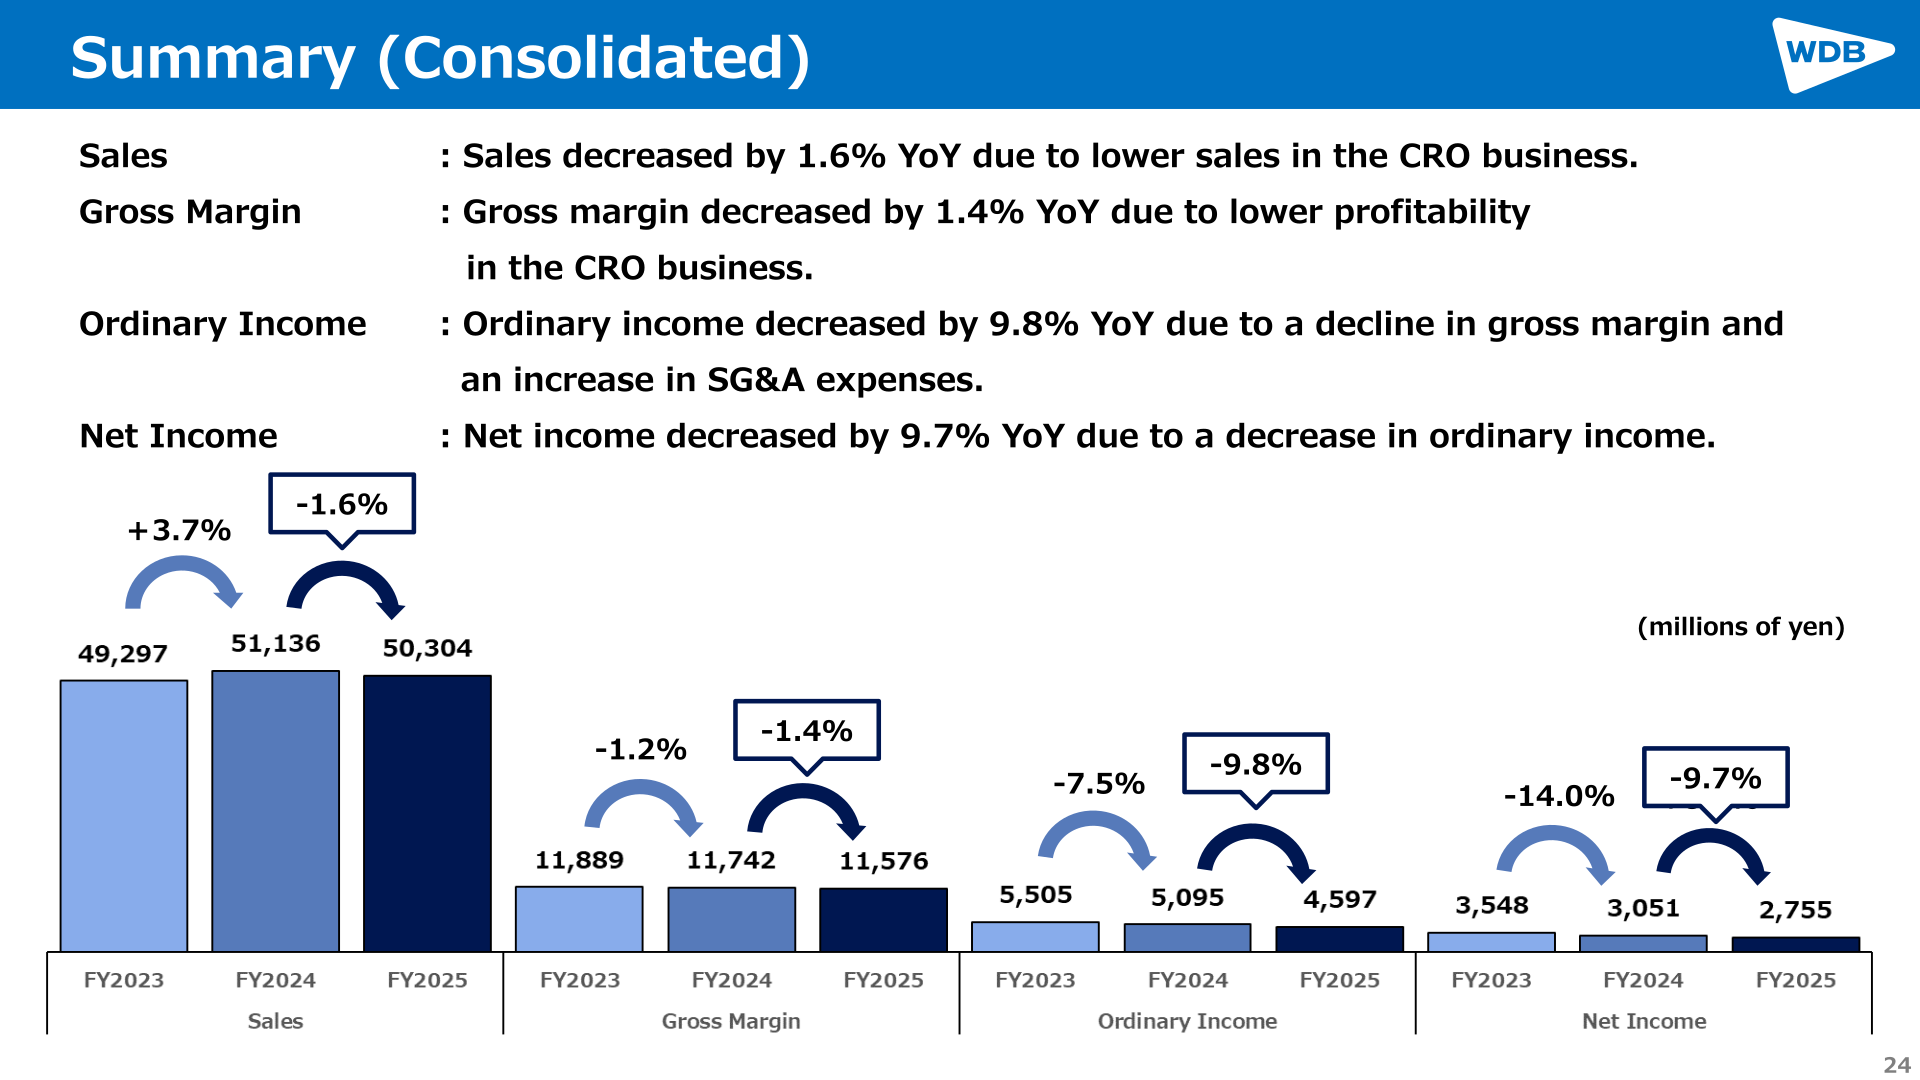
In the Human Resources business, sales increased by 1.3% year on year to 43,547 million yen due to an increase in temporary staffing fees and a decrease in the number of permanent-type temporary employees who could not be dispatched to clients. Segment profit increased by 6.4% to 4,301 million yen, with the operating income ratio at 9.9%; the company states that operating income increased due to the offset of increased SG&A expenses while increasing compensation for temporary staff. In the CRO business, sales decreased by 17.1% to 6,757 million yen due to the impact of the internalization of operations previously outsourced to the company by a major client and the divestiture of unprofitable overseas business. Segment profit decreased by 30.7% to 1,047 million yen, with the operating income ratio at 15.5%, because the company retained the workforce responsible for contract operations in anticipation of future orders despite the decrease in sales. For FY2025, the Human Resources business accounted for 86.6% of sales composition and 80.5% of profit composition, with CRO at 13.4% and 19.5% respectively.
| Segment | Metric (millions of yen) | FY2025 | Sales ratio | FY2024 | Sales ratio | Increase ratio |
|---|---|---|---|---|---|---|
| Human resources | Sales | 43,547 | – | 42,985 | – | 1.3% |
| Human resources | Segment profit | 4,301 | 9.9% | 4,041 | 9.4% | 6.4% |
| CRO | Sales | 6,757 | – | 8,150 | – | -17.1% |
| CRO | Segment profit | 1,047 | 15.5% | 1,512 | 18.6% | -30.7% |
FY2026 Forecast
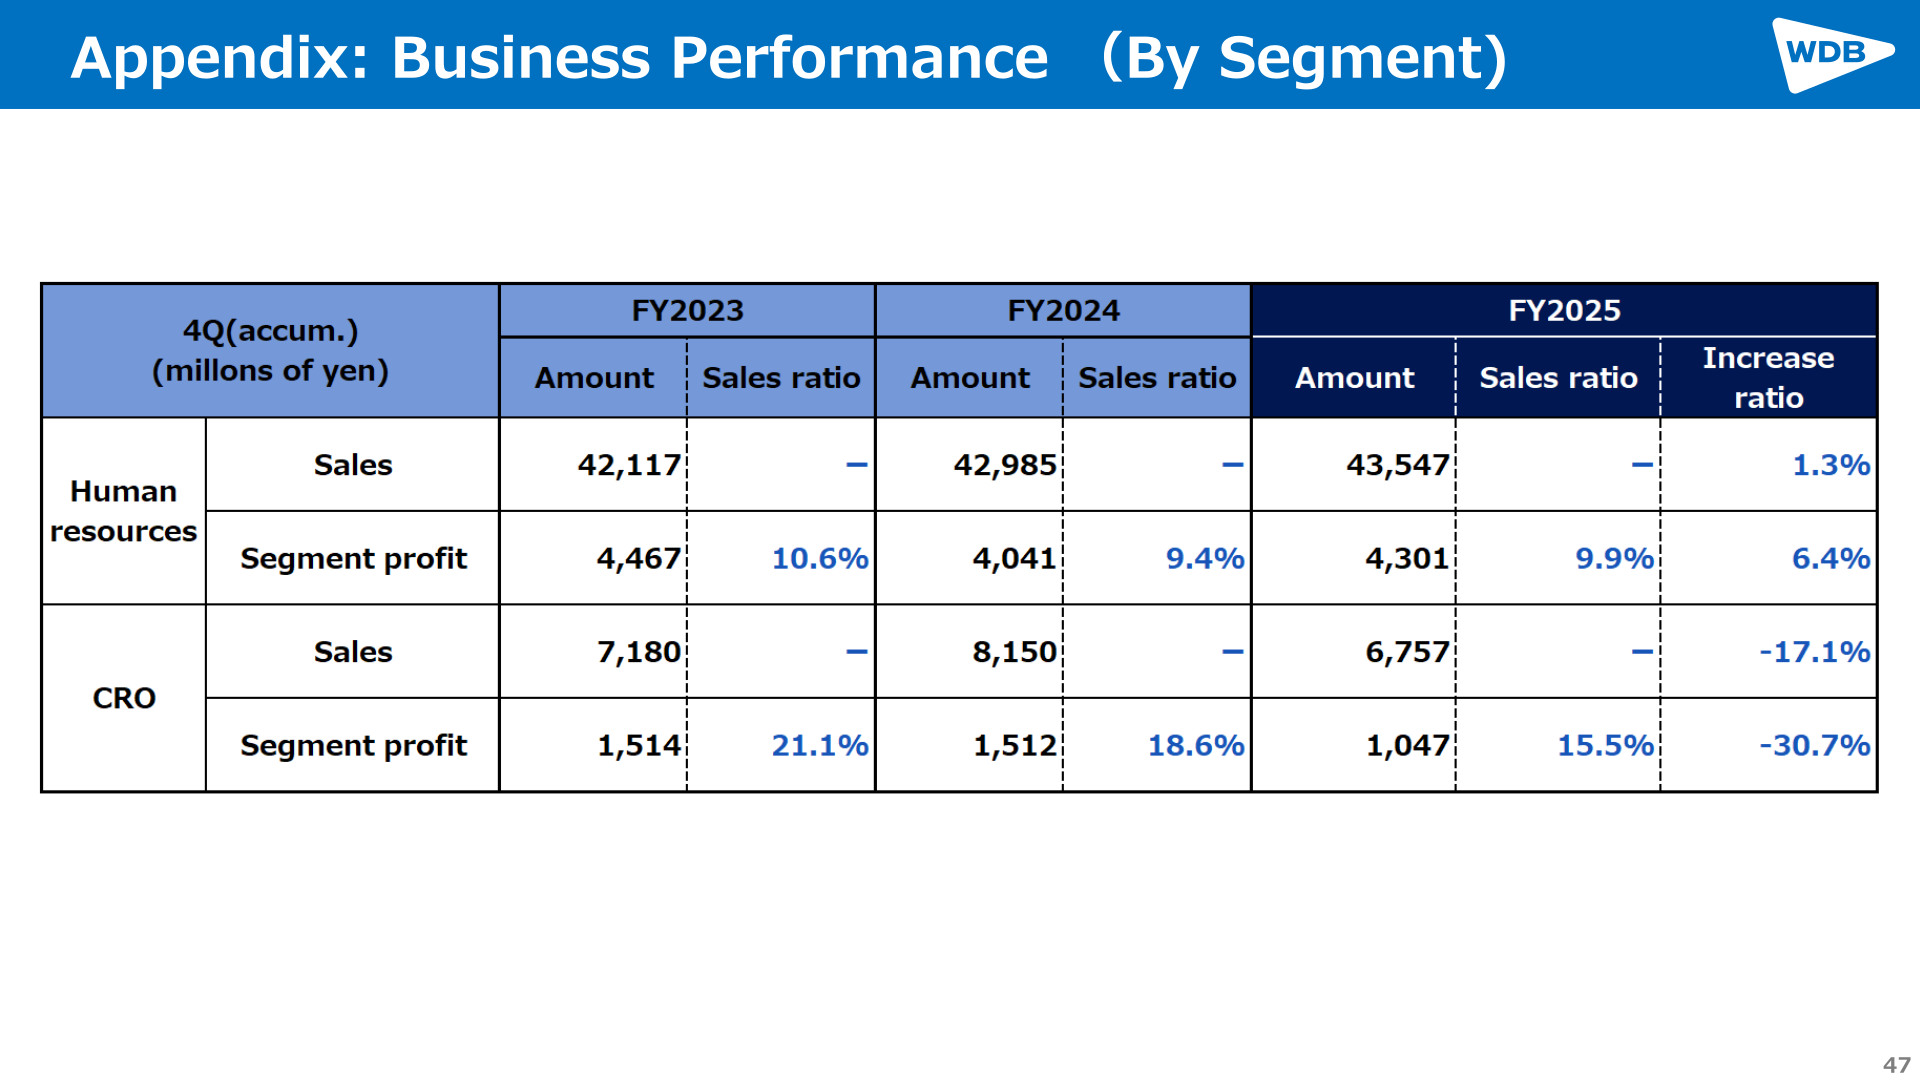
For FY2026 the company forecasts net sales of 51,439 million yen (+2.3%), gross margin of 12,178 million yen (+5.2%, 23.7% of sales), SG&A of 7,539 million yen (+6.0%), operating income of 4,639 million yen (+3.9%), ordinary income of 4,663 million yen (+1.4%) and net income of 2,772 million yen (+0.6%).
| Item (millions of yen) | FY2026 (Forecast) | Sales ratio | Growth rate | FY2025 | Sales ratio |
|---|---|---|---|---|---|
| Net Sales | 51,439 | 100.0% | 2.3% | 50,304 | 100.0% |
| Gross Margin | 12,178 | 23.7% | 5.2% | 11,576 | 23.0% |
| SG(&)A | 7,539 | 14.7% | 6.0% | 7,112 | 14.1% |
| Operating Income | 4,639 | 9.0% | 3.9% | 4,464 | 8.9% |
| Ordinary Income | 4,663 | 9.1% | 1.4% | 4,597 | 9.1% |
| Net Income | 2,772 | 5.4% | 0.6% | 2,755 | 5.5% |
Shareholder Returns
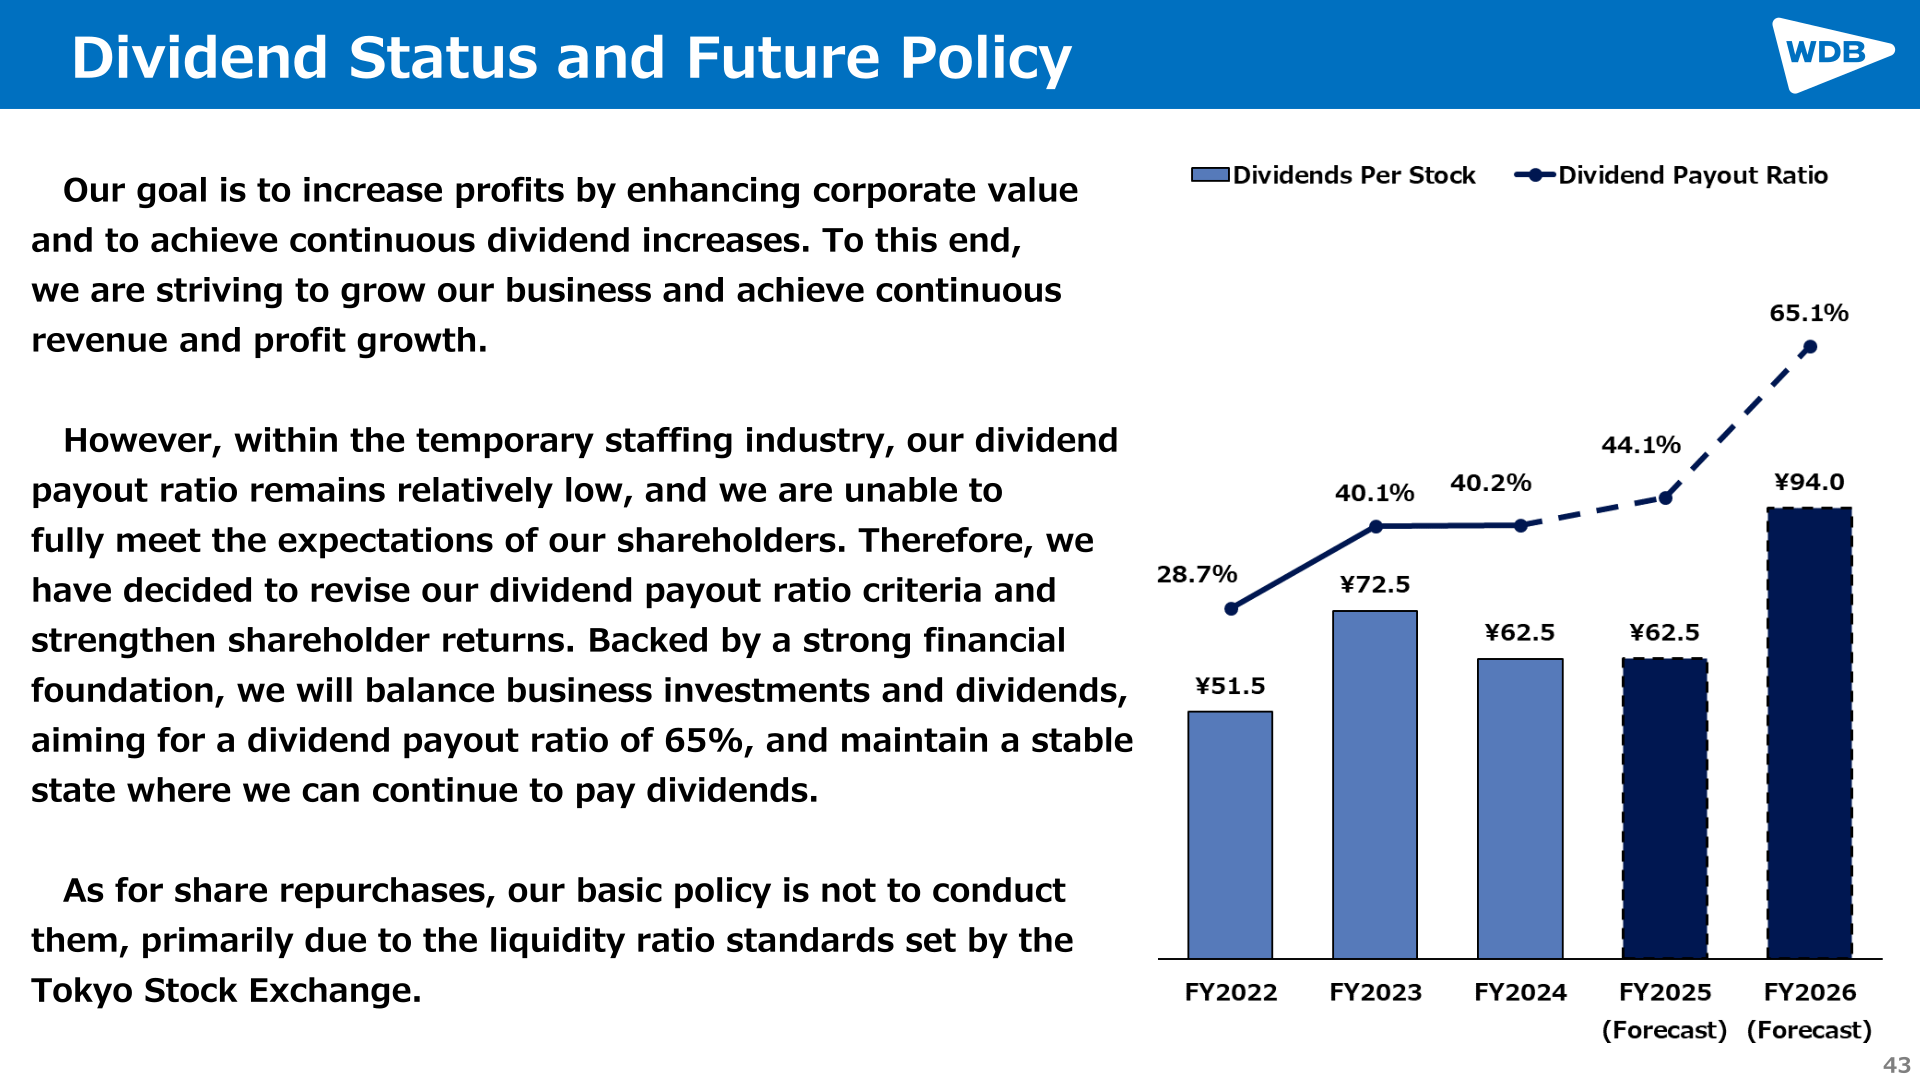
The company states that its goal is to increase profits by enhancing corporate value and to achieve continuous dividend increases. It notes that within the temporary staffing industry its dividend payout ratio remains relatively low and that it is unable to fully meet the expectations of its shareholders; it has therefore decided to revise its dividend payout ratio criteria and strengthen shareholder returns. Backed by a strong financial foundation, it will balance business investments and dividends, aiming for a dividend payout ratio of 65%, and maintain a stable state where it can continue to pay dividends. As for share repurchases, its basic policy is not to conduct them, primarily due to the liquidity ratio standards set by the Tokyo Stock Exchange.
| Fiscal year | Dividends Per Stock | Dividend Payout Ratio |
|---|---|---|
| FY2022 | ¥51.5 | 28.7% |
| FY2023 | ¥72.5 | 40.1% |
| FY2024 | ¥62.5 | 40.2% |
| FY2025 (Forecast) | ¥62.5 | 44.1% |
| FY2026 (Forecast) | ¥94.0 | 65.1% |
Medium-to-Long Term Management Policy and Topics
Based on its “Medium-to-Long Term Management Policy 2025,” the company operates under three policies: (1) pursue value as a staffing agency, (2) expand into new business domains as a “platform company,” and (3) establish a CRO business model that coexists with AI. In the Human Resources business, the company raised staff compensation and increased temporary staffing fees in April 2025 to maintain profit margins, strengthened its sales and selection systems so that its acceptance rate for staffing requests improved, and slightly reduced the turnover rate. In the platform area, it launched the centralized staffing operations management platform “DOCO1” in May 2025 alongside the existing human resources service platform “doconico” and the CRO contract management platform “CoCoPos,” and states that the number of DOCO1 customers is steadily increasing; it plans to continue development of a new platform aiming to launch the service in one to two years. In the CRO business, it worked on automating and standardizing processes, introduced an AI-powered document creation support tool, redefined its customer value proposition as a new document support service, and completed the sale of unprofitable overseas operations. The company also relocated its head office from Himeji-shi, Hyogo, to Kobe-shi, Hyogo, on October 1, 2025.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















