
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
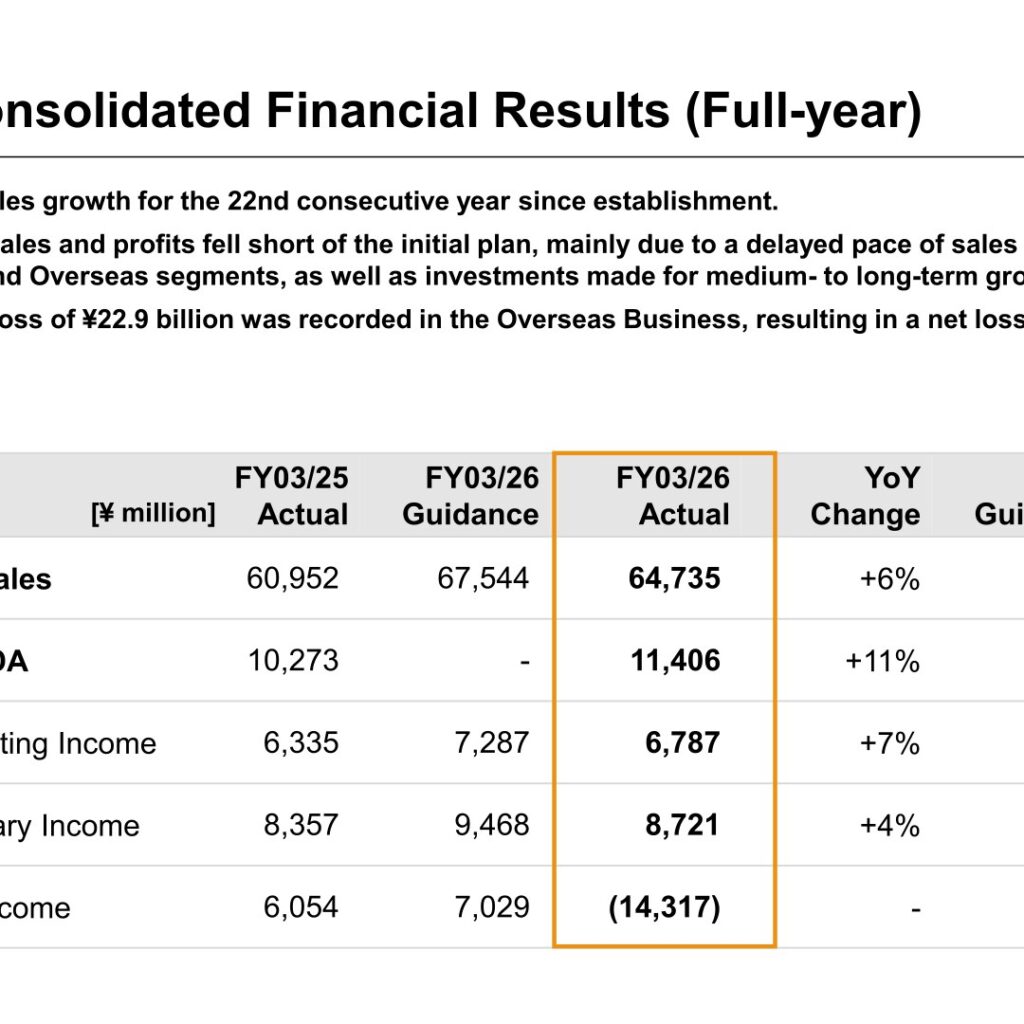
Note: SMS labels this fiscal year “FY03/26” (the year ended March 31, 2026); on this site it is classified as FY2025, and all labels in the text, tables and segment data below follow the company’s own materials. SMS Co., Ltd. reported net sales of 64,735 million yen (+6% YoY), EBITDA of 11,406 million yen (+11% YoY) and operating income of 6,787 million yen (+7% YoY) for FY03/26. Both sales and profits nevertheless fell short of the initial plan, mainly due to a delayed pace of sales recovery centered on the Career and Overseas segments as well as investments made for medium- to long-term growth. An impairment loss of 22.9 billion yen was recognized in the Overseas Business, resulting in a net loss of 14,317 million yen. The dividend forecast for FY03/26 was left unchanged at 29.5 yen per share, up 1.0 yen from the prior fiscal year.
Consolidated Results (Full-Year Actual)
SMS achieved net sales growth for the 22nd consecutive year since establishment. Against the FY03/26 guidance, net sales came in 4% lower, operating income 7% lower and ordinary income 8% lower. Net income turned negative because of the impairment loss recorded in the Overseas Business. In the company’s historical series, net sales rose from 60,952 million yen in FY24 to 64,735 million yen in FY25, while EPS moved from 71.0 yen to (173.7) yen.
| Item [¥ million] | FY03/25 Actual | FY03/26 Guidance | FY03/26 Actual | YoY Change | vs Guidance |
|---|---|---|---|---|---|
| Net Sales | 60,952 | 67,544 | 64,735 | +6% | (4%) |
| EBITDA | 10,273 | – | 11,406 | +11% | – |
| Operating Income | 6,335 | 7,287 | 6,787 | +7% | (7%) |
| Ordinary Income | 8,357 | 9,468 | 8,721 | +4% | (8%) |
| Net Income | 6,054 | 7,029 | (14,317) | – | – |
Impairment Loss in the Overseas Business
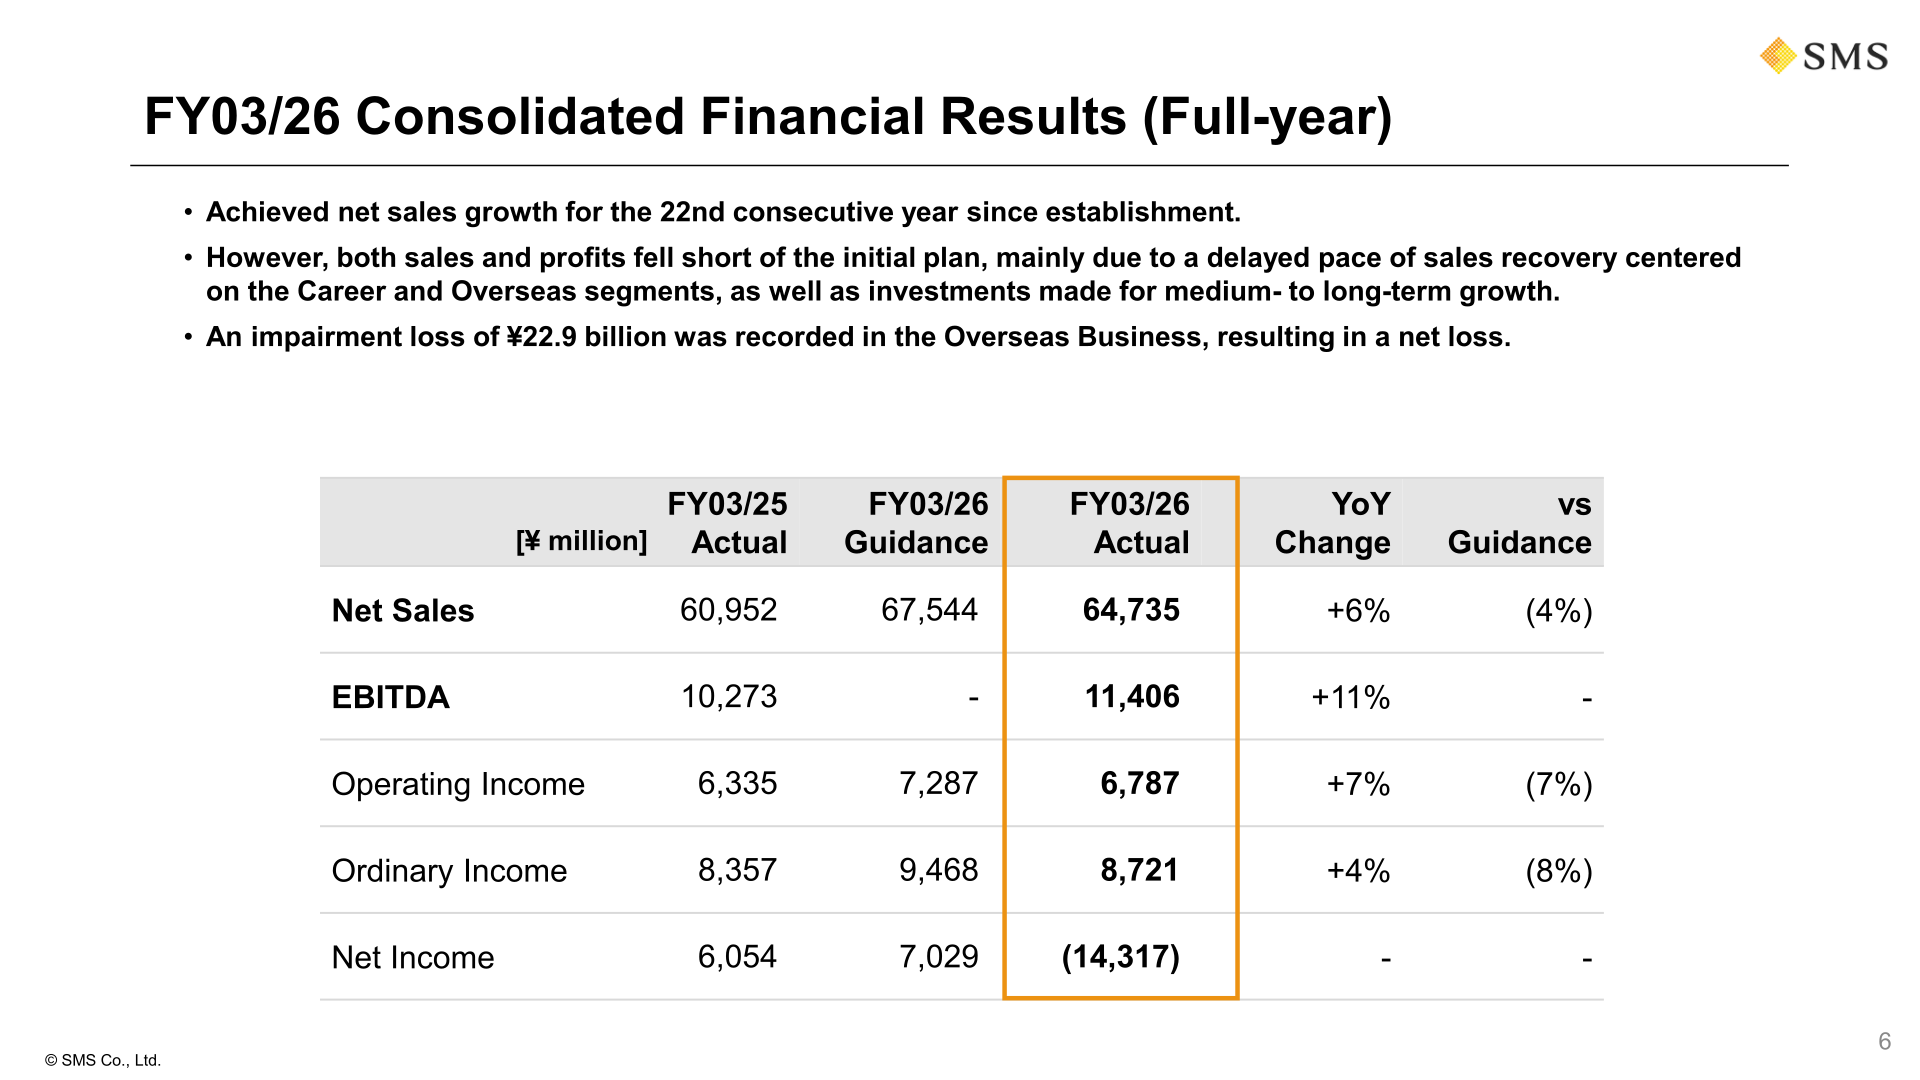
In the Overseas Business, SMS conducted an impairment test under conservative assumptions reflecting recent operational performance and market conditions, resulting in an impairment loss of 22.9 billion yen. The breakdown is trademark rights of 13,041 million yen, goodwill of 8,649 million yen, software of 677 million yen and customer-related assets of 589 million yen; the figure includes an FX impact of approximately 5.4 billion yen compared with the time of acquisition. Going forward, this will reduce annual intangible asset amortization by approximately 1.5 billion yen from FY03/27 onward. The background cited is prolonged budget reductions at major pharmaceutical companies, including patent cliffs of key drugs, which depressed the order environment for the company’s marketing support services, together with partially revised future plans in the Global Career Business in response to the deteriorating geopolitical environment in the Middle East. Because the impairment loss is a non-cash item, there is no change to the FY03/26 dividend forecast of 29.5 yen per share. The company states that it is executing a fundamental review of the business centered on future growth potential and profitability, and will explore all strategic options including alliances with third parties and the utilization of external capital.
Segment Results
In the Career segment, demand for hiring professionals by medical, elderly and disability care business operators remained strong, but net sales growth was limited by operational challenges including prolonged lead times to job placement in the RAG business and the impact of the abolition of “continuous service allowances” in the DR business; in Q4, initiatives addressing prolonged lead times made progress and the sales growth rate improved. In the Elderly Care / Disability Care Management Support segment, Kaipoke memberships increased steadily to 60,800 service offices (27,000 companies) as of April 1, 2026, an increase of 5,250 service offices (2,100 companies) during FY03/26, and growth was also supported by increased usage of optional add-ons such as factoring, tablets and smartphones as well as the M&A matching business and RAG for persons with disabilities. In the Overseas segment, the Medical Platform Business saw net sales growth constrained by reduced marketing spend among certain clients, while the Global Career Business declined year on year as deteriorating Middle East geopolitical conditions reduced cross-border mobility of healthcare professionals.
| Business / Segment — Net Sales [¥ million] | FY03/25 Actual | FY03/26 Actual | YoY Change |
|---|---|---|---|
| Elderly Care Career | 19,320 | 20,487 | +6% |
| Medical Care Career | 16,891 | 17,788 | +5% |
| Career Total | 36,211 | 38,276 | +6% |
| Elderly/Disability Care Operators (Kaipoke) | 11,957 | 13,715 | +15% |
| Overseas | 9,385 | 8,851 | (6%) |
FY03/27 Guidance
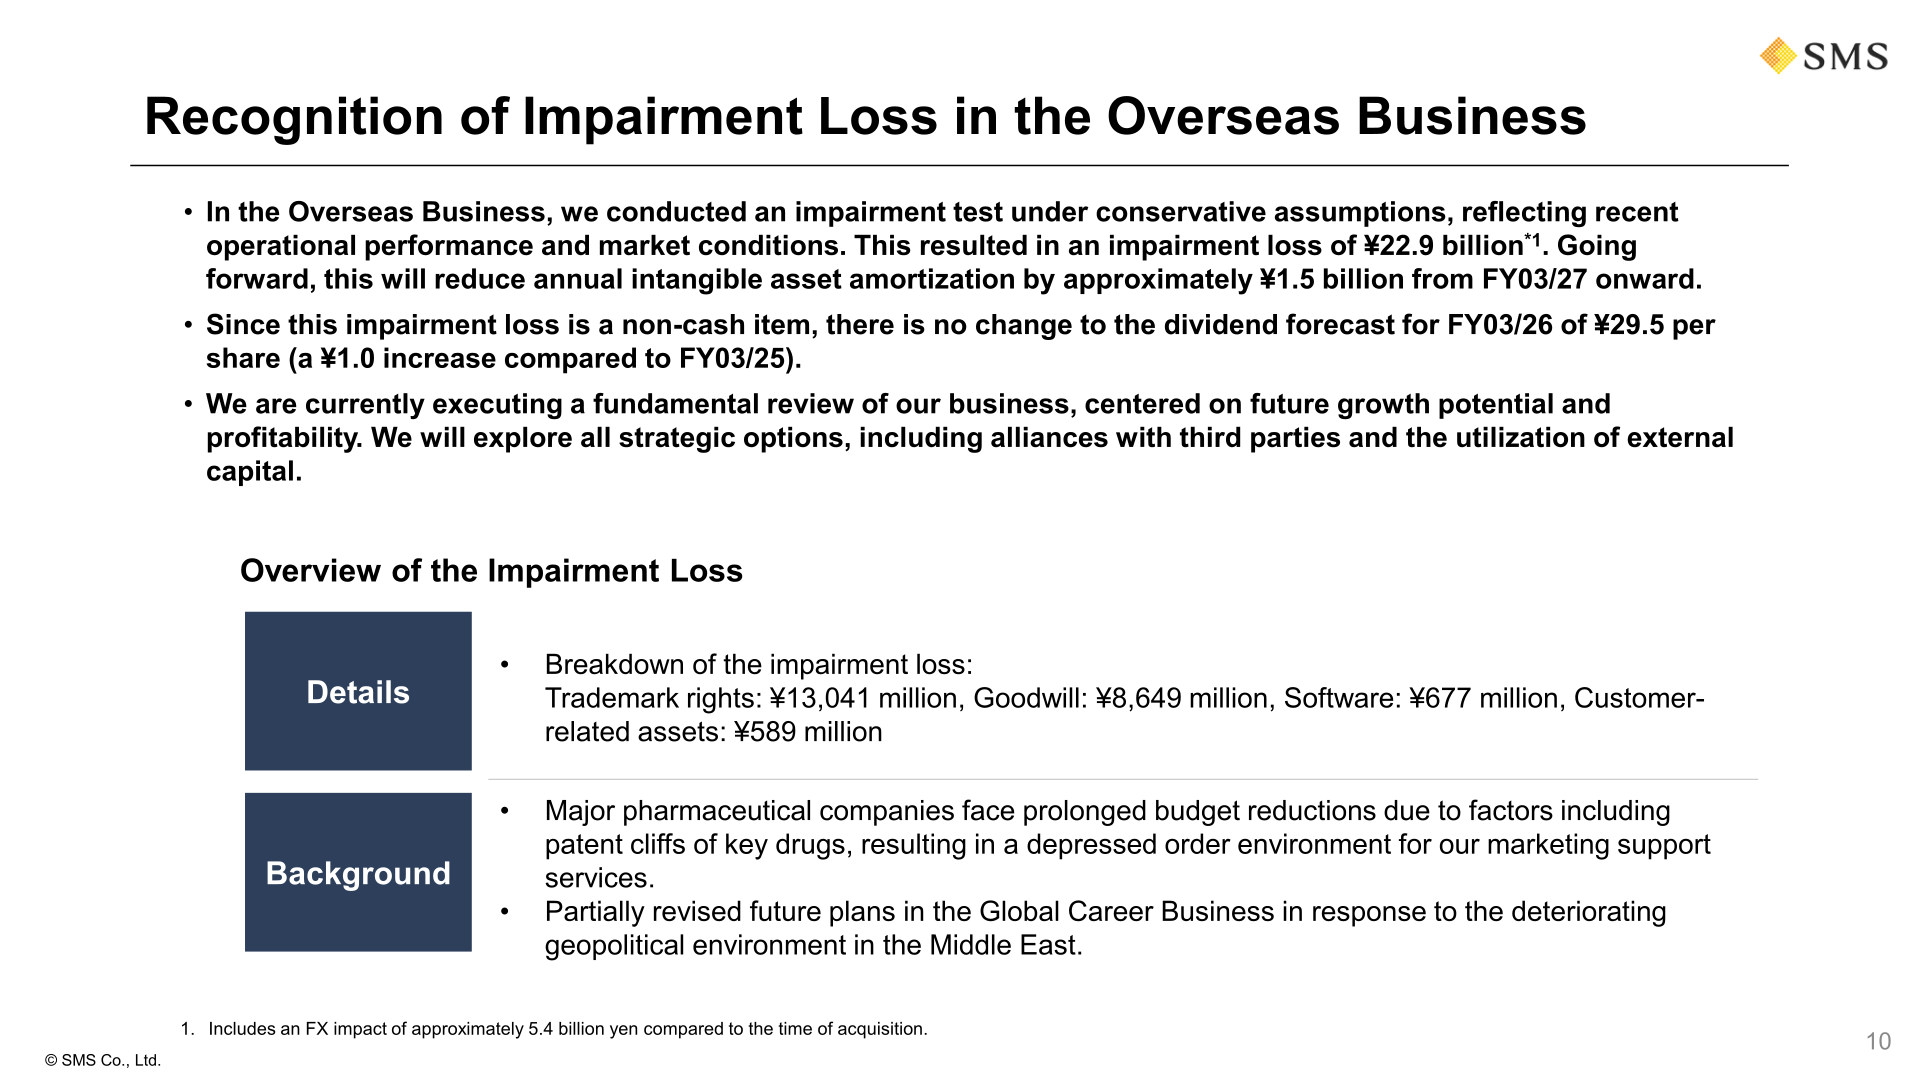
SMS positions FY03/27 as a foundation-building year that prioritizes strategic investments for future growth, with EBITDA projected to decline year on year as the company invests in establishing its future earnings base. Growth investments of approximately 2.0 billion yen are planned, focused on year-round aggressive recruitment of CPs, strengthening sales and customer success functions and brand awareness initiatives for DR, and reinforcing the sales capability for Kabenashi Cloud. The company also plans to strengthen initiatives to transition to a capital-intensive model, including the AI platformization of Career and the development of Kaipoke Connect.
| Item [¥ millions] | FY03/26 Actual | FY03/27 Guidance | Difference (Amount) | YoY Change |
|---|---|---|---|---|
| Net Sales | 64,735 | 71,834 | 7,099 | +11% |
| EBITDA | 11,406 | 10,431 | (975) | (9%) |
| Operating Income | 6,787 | 6,801 | 14 | +0% |
| Ordinary Income | 8,721 | 8,731 | 9 | +0% |
| Net Income | (14,317) | 6,165 | 20,483 | – |
New Segment Structure and Pro-Forma Figures
Effective FY03/27, SMS transitions from a single reportable segment to a three-segment structure: “Career,” “Elderly/Disability Care Management Support” and “Overseas.” The RAG service for persons with disabilities, previously included in the Elderly/Disability Care Management Support segment, has been reclassified to “Others,” and additional segment boundaries have been optimized. The company presented pro-forma figures under the new structure; in addition to the segments shown, total net sales include “Others,” while EBITDA includes “Others” and “Adjustments,” the latter mainly comprising various administrative expenses of corporate departments and accounting for approximately 7% of total net sales.
| Pro-Forma [¥ millions] | FY03/2025 Actual | FY03/2026 Actual | FY03/2027 Guidance |
|---|---|---|---|
| Net Sales — Career | 36,214 | 38,279 | 41,914 |
| Net Sales — Elderly/Disability Care Management Support | 11,868 | 13,471 | 15,190 |
| Net Sales — Overseas | 9,385 | 8,851 | 9,786 |
| EBITDA — Career | 7,104 | 7,815 | 7,556 |
| EBITDA — Elderly/Disability Care Management Support | 5,188 | 6,091 | 6,420 |
| EBITDA — Overseas | 1,653 | 1,336 | 1,271 |
| EBITDA Margin — Career | 19.6% | 20.4% | 18.0% |
| EBITDA Margin — Elderly/Disability Care Management Support | 43.7% | 45.2% | 42.3% |
| EBITDA Margin — Overseas | 17.6% | 15.1% | 13.0% |
Shareholder Returns
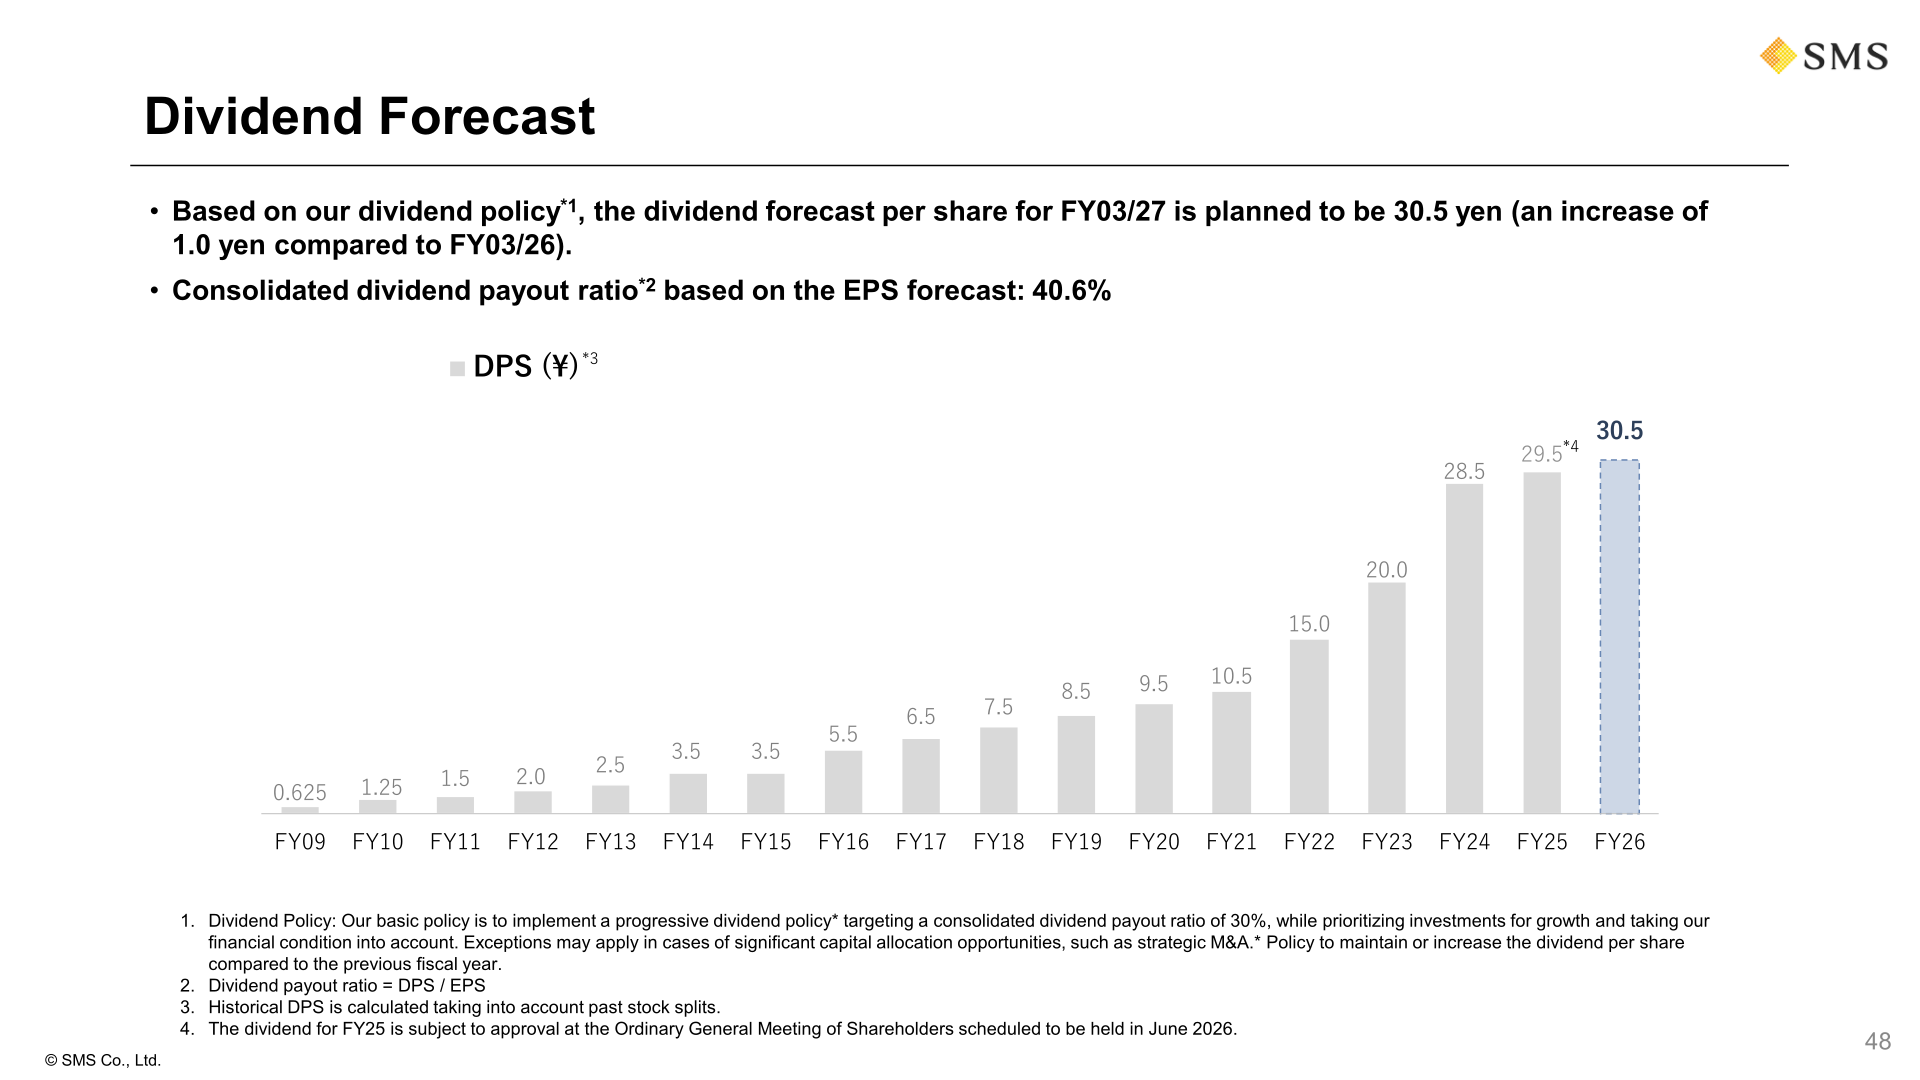
SMS’s basic policy is a progressive dividend policy targeting a consolidated dividend payout ratio of 30%, while prioritizing investments for growth and taking its financial condition into account, with exceptions possible in cases of significant capital allocation opportunities such as strategic M&A. The dividend per share for FY03/26 is 29.5 yen, up 1.0 yen from FY03/25 and subject to approval at the Ordinary General Meeting of Shareholders scheduled for June 2026. The dividend forecast per share for FY03/27 is 30.5 yen, an increase of 1.0 yen compared with FY03/26, giving a consolidated dividend payout ratio of 40.6% based on the EPS forecast. Under its capital allocation plan for FY03/27 to FY03/31, the company assumes operating cash flow of 75.0 billion yen or more and states that it will prioritize investments for growth and flexibly return excess cash to shareholders through progressive dividends targeting a 30% payout ratio and agile share repurchases depending on financial conditions and stock price levels.
Corporate Value Creation Roadmap
SMS disclosed a roadmap for maximizing corporate value, targeting net sales of over 122.0 billion yen (5-year CAGR of 14%), EBITDA of over 28.0 billion yen (5-year CAGR of 20%) and ROE of 30% or more in FY03/31, with the ROE target to be achieved as early as possible by FY03/31; the numerical plan excludes the potential impact of M&A transactions that have not yet been executed. The company changed its profit metric to EBITDA in order to accurately assess business profitability during a phase of expanding investments in M&A and software, and notes that EBITDA growth in FY03/27 to FY03/28 will be limited due to investments for medium- to long-term growth. Management cites four challenges behind the share price stagnation: missed growth opportunities from over-reliance on internal capabilities, a short-term profit focus with inadequate future investment, growth stagnation from labor-intensive model dependency, and miscommunication with the capital markets. It has decided to strengthen governance structures, including the establishment of the Corporate Value Improvement Committee (CVIC), and plans to disclose a detailed medium-term management plan by the time of the FY03/27 full-year earnings announcement at the latest.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















