
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: NITTOC CONSTRUCTION does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. The company refers to this period as the fiscal year ended March 31, 2026 (fiscal 2025), which this site classifies as FY2025; the labels used in the text and tables below follow the source materials.
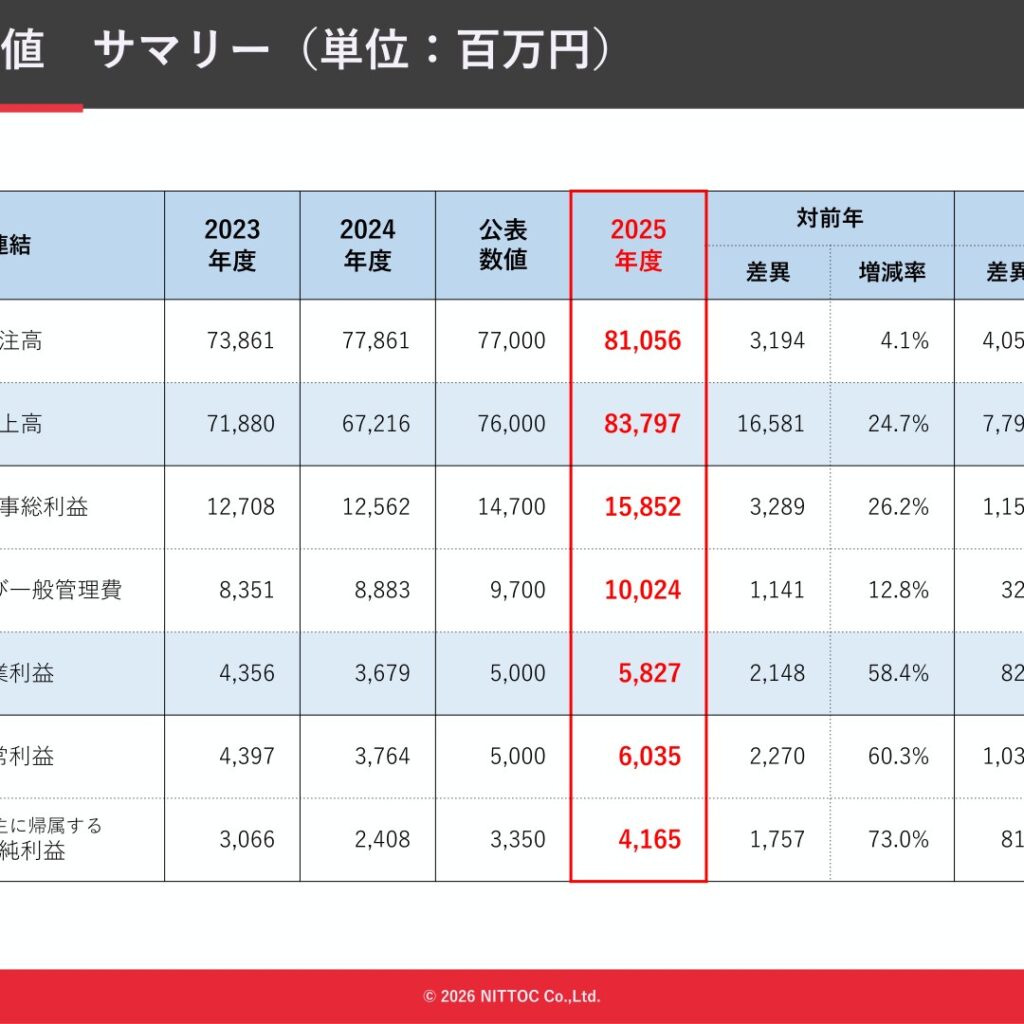
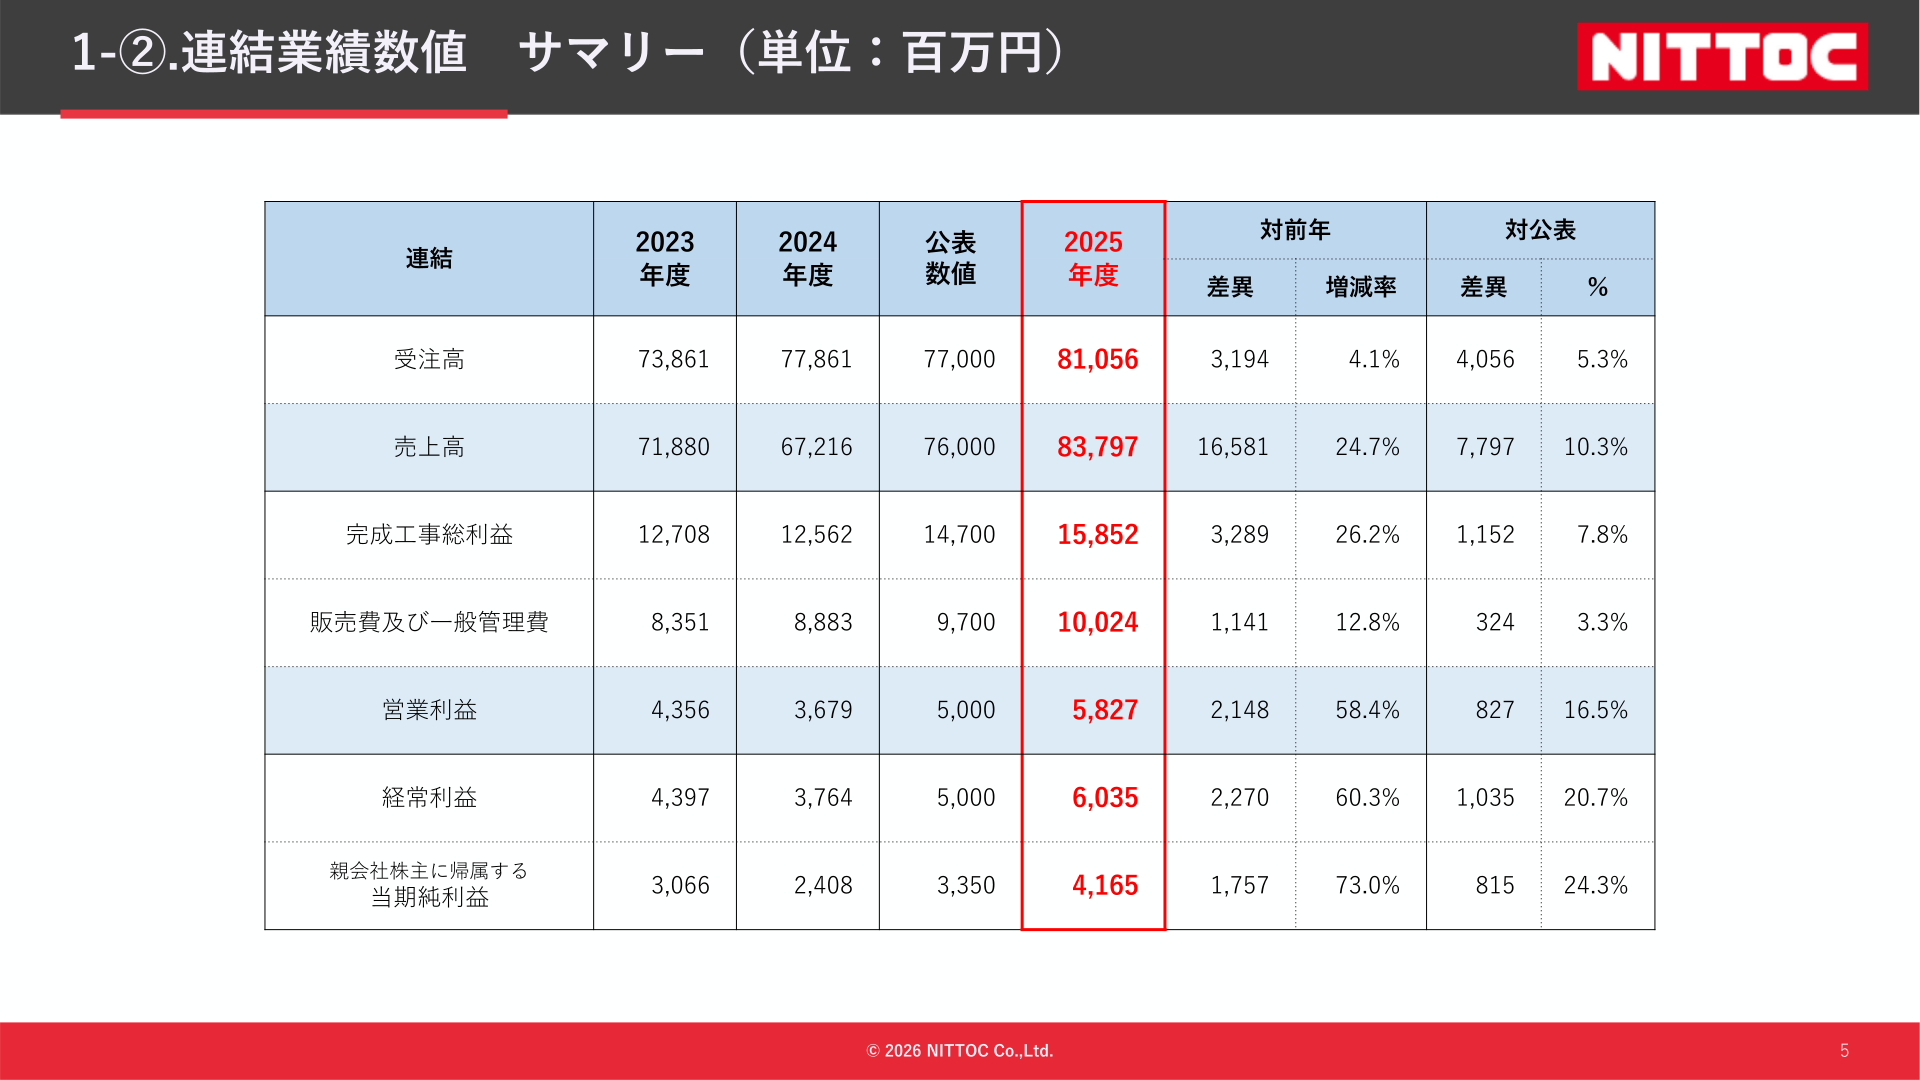
For the fiscal year ended March 31, 2026 (fiscal 2025), NITTOC CONSTRUCTION (1929) reported consolidated orders received of 81,056 million yen (+4.1% year on year), net sales of 83,797 million yen (+24.7%), operating profit of 5,827 million yen (+58.4%), ordinary profit of 6,035 million yen (+60.3%), and profit attributable to owners of parent of 4,165 million yen (+73.0%). Recovery and reconstruction work following the Noto Peninsula Earthquake in slope protection works, erosion-control and landslide countermeasure works in Nara Prefecture, and the recognition of the Hokkaido Shinkansen extension project in foundation and ground improvement works pushed net sales higher, and the company also landed +10.3% above its published net sales figure and +16.5% above its published operating profit figure. For fiscal 2026 (the fiscal year ending March 31, 2027), the company factors in variability from large-scale projects and expects net sales of 80,500 million yen and operating profit of 5,500 million yen.
Consolidated Results (Fiscal Year Ended March 31, 2026, Actual)
Orders received rose +4.1% year on year, reflecting increased orders for Noto Peninsula Earthquake reconstruction work in slope protection works and orders for the Hokkaido Shinkansen extension project in foundation and ground improvement works, together with the contribution of Aso Foam Crete Co., Ltd., which joined the consolidated subsidiaries. Net sales rose +24.7%, driven by Noto Peninsula Earthquake reconstruction work and erosion-control and landslide countermeasure works in Nara Prefecture within slope protection works and by the recognition of the Hokkaido Shinkansen extension project within foundation and ground improvement works, as well as by the larger number of projects contributing in the period. Operating profit rose +58.4% as the profit margin and gross profit improved on higher net sales and on the continued confirmation of profitability from the order stage, cost control at the construction stage, and appropriate handling of design changes and additional work. Gross profit on completed construction contracts was 15,852 million yen (+26.2%) and selling, general and administrative expenses were 10,024 million yen (+12.8%). The gross profit margin was 18.9% for the full year (up 0.2 points year on year); the fourth-quarter gross profit margin was 1.9% below the year-earlier level owing to project mix, while the full-year figure improved 0.2 points from the previous fiscal year. In the fourth quarter (January to March), orders received were 22.0 billion yen (up 2.9 billion yen, or +15.3%, year on year), net sales were 22.5 billion yen (up 5.1 billion yen, or +29.4%), and operating profit was 1.4 billion yen (+7.4%).
| Item | Fiscal 2025 (FY ended March 31, 2026) | Fiscal 2024 (FY ended March 31, 2025) | YoY change |
|---|---|---|---|
| Orders received | 81,056 million yen | 77,861 million yen | 4.1% |
| Net sales | 83,797 million yen | 67,216 million yen | 24.7% |
| Gross profit on completed construction contracts | 15,852 million yen | 12,562 million yen | 26.2% |
| Selling, general and administrative expenses | 10,024 million yen | 8,883 million yen | 12.8% |
| Operating profit | 5,827 million yen | 3,679 million yen | 58.4% |
| Ordinary profit | 6,035 million yen | 3,764 million yen | 60.3% |
| Profit attributable to owners of parent | 4,165 million yen | 2,408 million yen | 73.0% |
On the balance sheet, total assets were 62,395 million yen (56,946 million yen for the fiscal year ended March 31, 2025), total liabilities were 24,434 million yen (22,378 million yen), and total net assets were 37,961 million yen (34,567 million yen). The increase in total assets mainly reflected higher machinery, vehicles, tools, furniture and fixtures resulting from facility construction to support Noto Peninsula Earthquake reconstruction work and from purchases of machinery aimed at expanding orders for ground improvement work. Cash flows were 3,471 million yen from operating activities, -1,766 million yen from investing activities, and -2,192 million yen from financing activities, leaving cash and cash equivalents of 17,699 million yen.
Results by Work Category
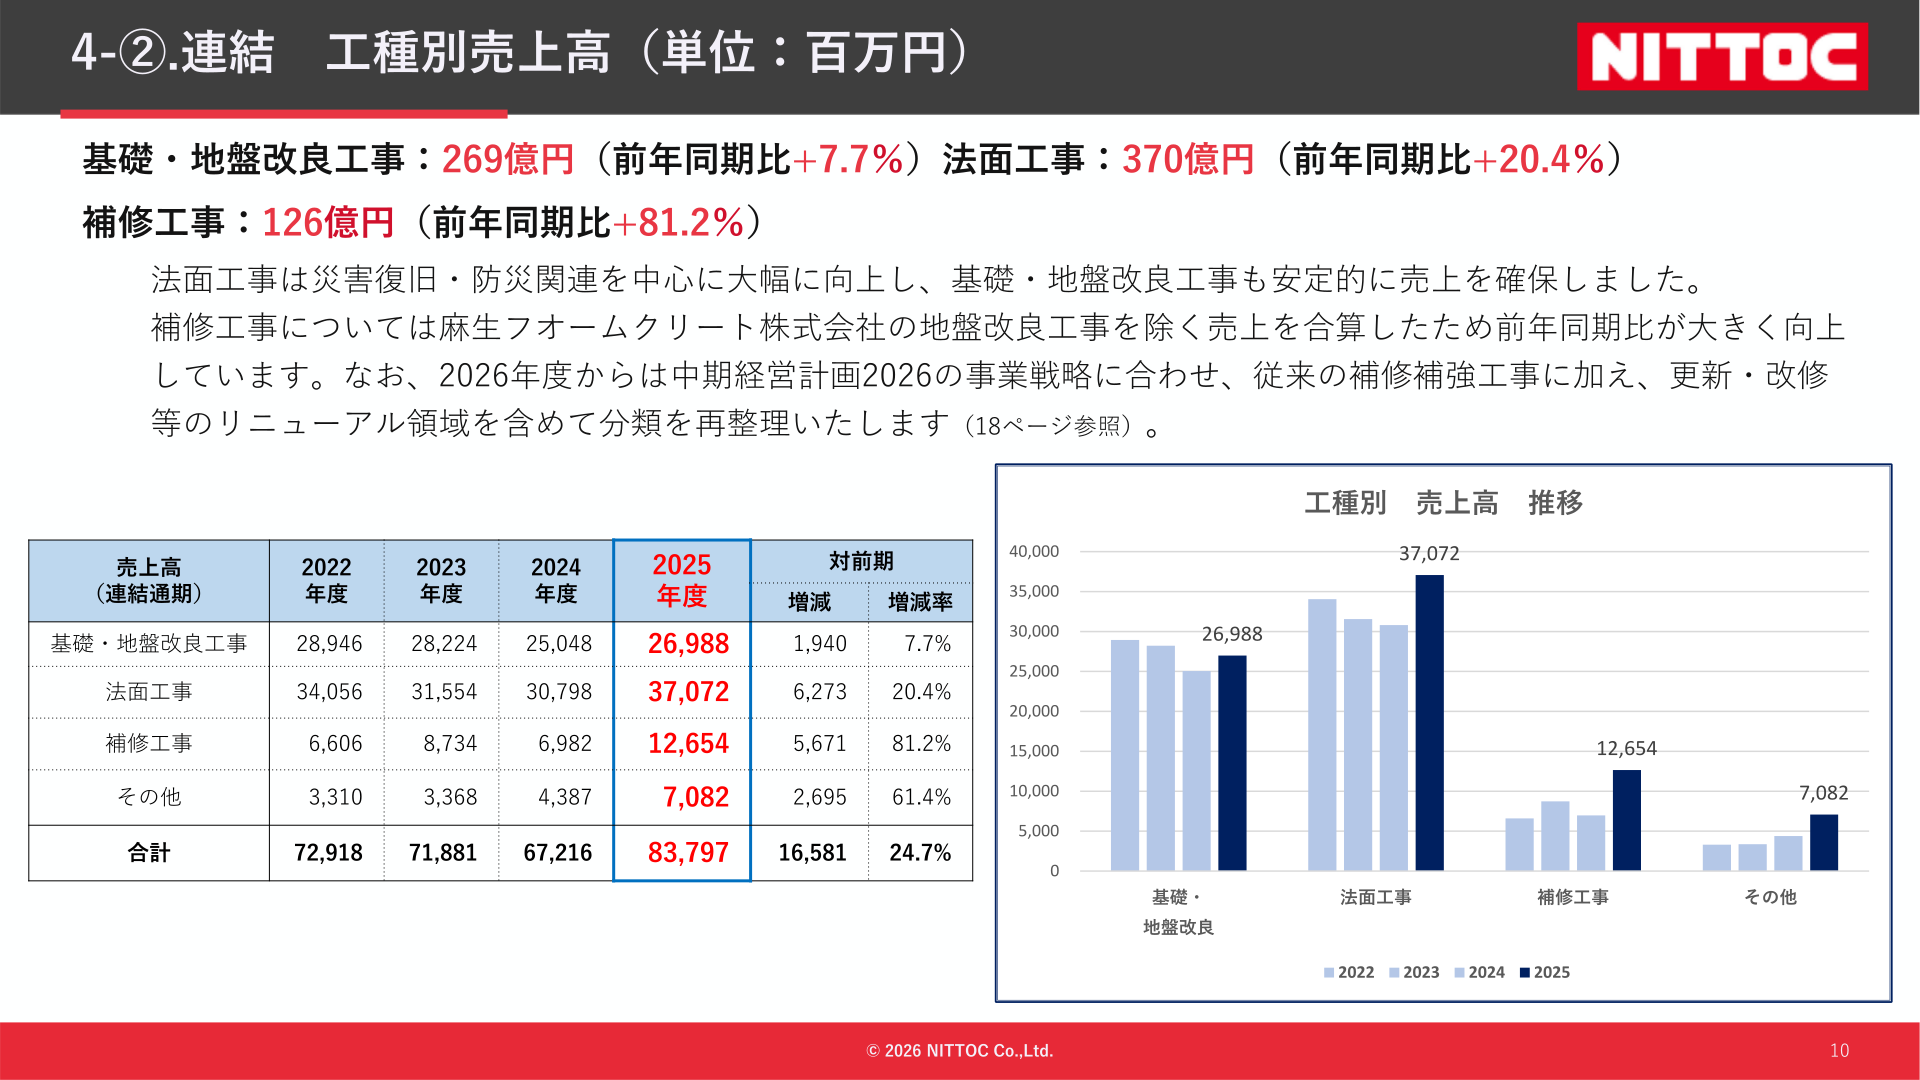
Orders received by work category were 25,970 million yen for foundation and ground improvement works (-4.4% year on year), 38,971 million yen for slope protection works (+3.5%), 9,632 million yen for repair works (+29.3%), and 6,481 million yen for other works, including pipe jacking (+16.4%). Foundation and ground improvement works came in at -4.4% because other foundation work (dam foundations and pile foundations) decreased even though ground improvement work edged up, while slope protection works rose 3.5% from the previous fiscal year on large-scale projects and on orders for disaster recovery and reconstruction work related to the Noto Peninsula Earthquake. Net sales by work category were 26,988 million yen for foundation and ground improvement works (+7.7%), 37,072 million yen for slope protection works (+20.4%), 12,654 million yen for repair works (+81.2%), and 7,082 million yen for other works (+61.4%). Slope protection works improved substantially, centered on disaster recovery and disaster prevention, and foundation and ground improvement works also secured sales steadily. Repair works showed a large year-on-year gain because the sales of Aso Foam Crete Co., Ltd. excluding ground improvement work were aggregated in this category. Carryover construction backlog was 17,715 million yen for foundation and ground improvement works (-5.4%), 29,848 million yen for slope protection works (+6.8%), 4,835 million yen for repair works (-38.5%), and 5,776 million yen for other works (-9.4%), for a total of 58,176 million yen (-4.5%); the materials state that the company secured 58.1 billion yen, on a par with the strong year-earlier level.
| Work category | Orders received, fiscal 2025 | Orders received, YoY | Net sales, fiscal 2025 | Net sales, YoY |
|---|---|---|---|---|
| Foundation and ground improvement works | 25,970 million yen | -4.4% | 26,988 million yen | 7.7% |
| Slope protection works | 38,971 million yen | 3.5% | 37,072 million yen | 20.4% |
| Repair works | 9,632 million yen | 29.3% | 12,654 million yen | 81.2% |
| Other | 6,481 million yen | 16.4% | 7,082 million yen | 61.4% |
| Total | 81,056 million yen | 4.1% | 83,797 million yen | 24.7% |
Full-Year Forecast
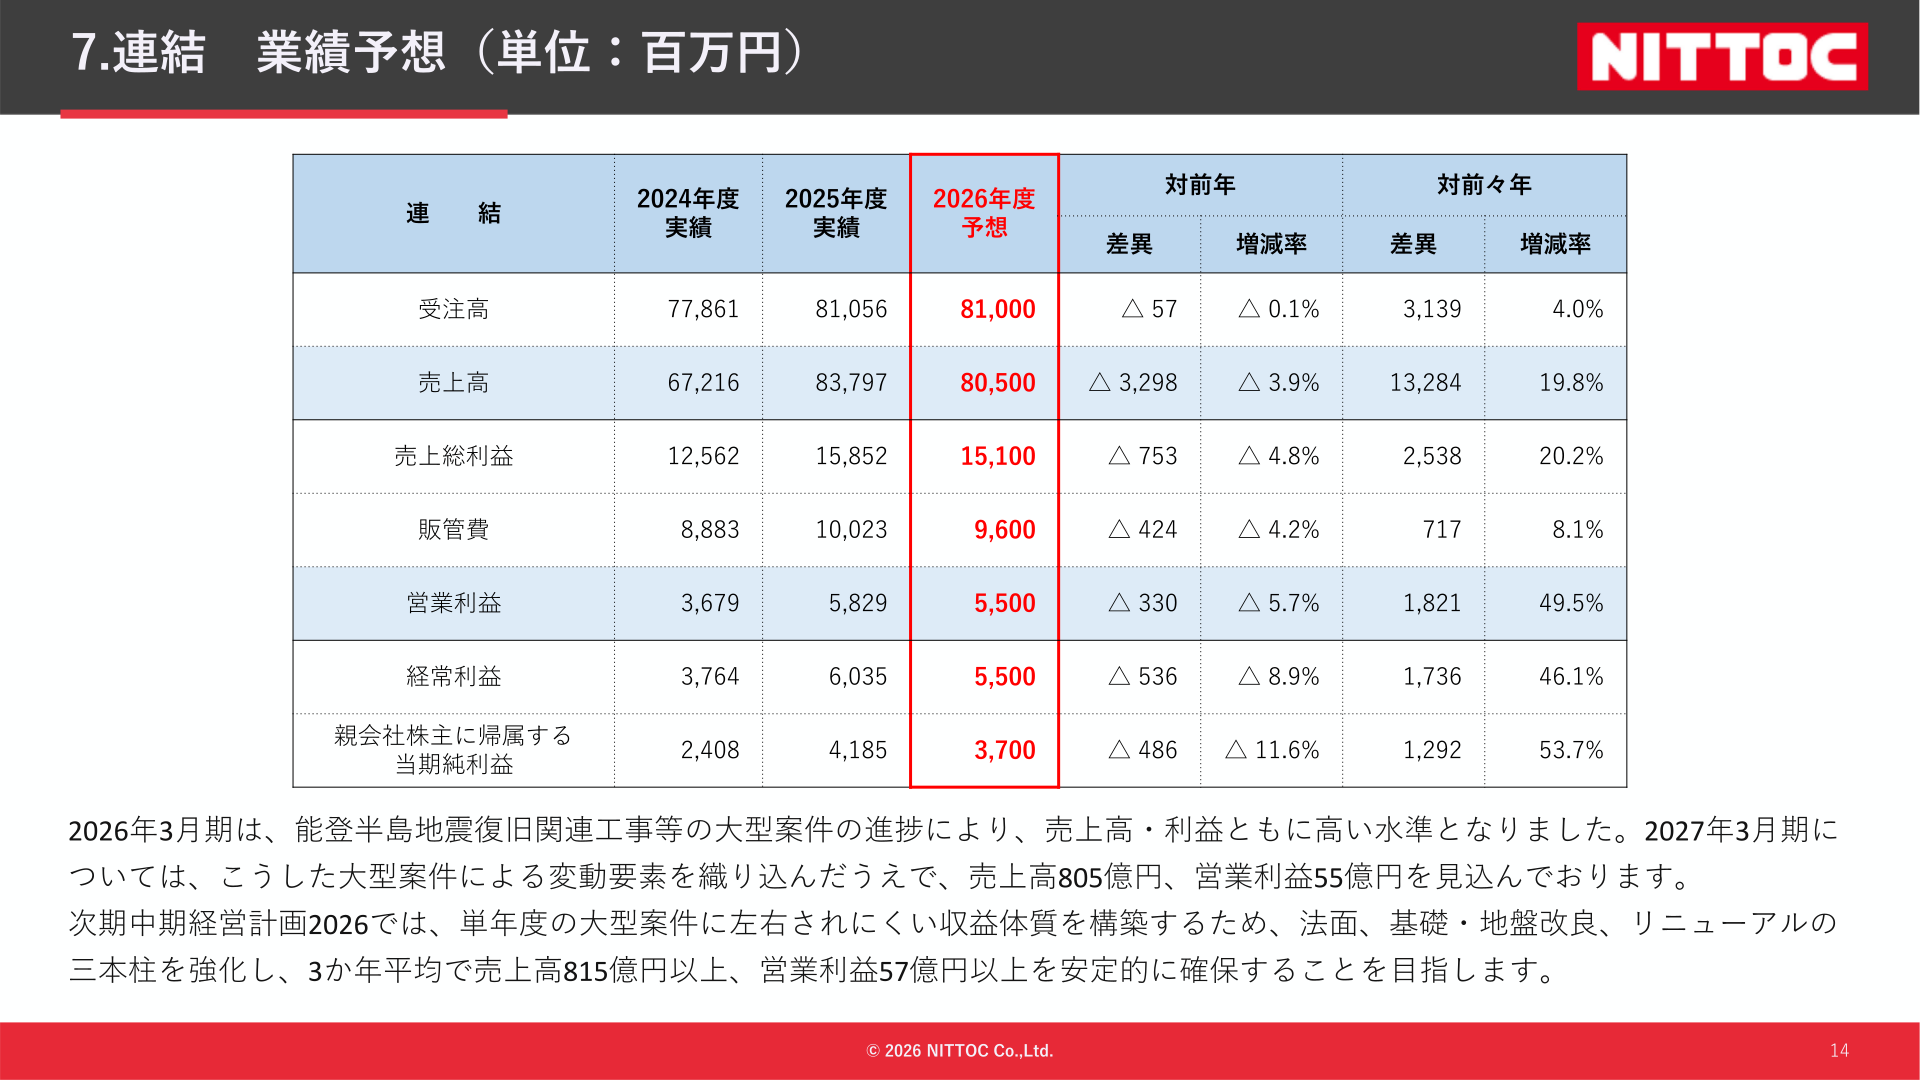
In the fiscal year ended March 31, 2026, both net sales and profits reached high levels as large-scale projects such as Noto Peninsula Earthquake recovery-related work progressed. For the fiscal year ending March 31, 2027, the company factors in the variability arising from such large-scale projects and expects net sales of 80.5 billion yen and operating profit of 5.5 billion yen. The consolidated forecast for fiscal 2026 (the fiscal year ending March 31, 2027) comprises orders received of 81,000 million yen (-0.1% year on year), net sales of 80,500 million yen (-3.9%), gross profit of 15,100 million yen (-4.8%), selling, general and administrative expenses of 9,600 million yen (-4.2%), operating profit of 5,500 million yen (-5.7%), ordinary profit of 5,500 million yen (-8.9%), and profit attributable to owners of parent of 3,700 million yen (-11.6%).
| Item | Fiscal 2026 forecast (FY ending March 31, 2027) | YoY change |
|---|---|---|
| Orders received | 81,000 million yen | -0.1% |
| Net sales | 80,500 million yen | -3.9% |
| Gross profit | 15,100 million yen | -4.8% |
| Selling, general and administrative expenses | 9,600 million yen | -4.2% |
| Operating profit | 5,500 million yen | -5.7% |
| Ordinary profit | 5,500 million yen | -8.9% |
| Profit attributable to owners of parent | 3,700 million yen | -11.6% |
Shareholder Returns
As the financial and investment strategy of Medium-Term Management Plan 2026, the company sets out strengthening and reviewing shareholder returns, putting into practice management that is conscious of capital efficiency, and making effective growth investments. For shareholder returns, it has adopted a progressive dividend policy for dividends and states that DOE will be maintained at the current level. In the consolidated statement of cash flows for the fiscal year ended March 31, 2026, dividends paid were 2,004 million yen (1,960 million yen for the fiscal year ended March 31, 2025). The dividend per share is not stated in these materials.
Medium-Term Management Plan 2026 and the Change in Work Category Classification
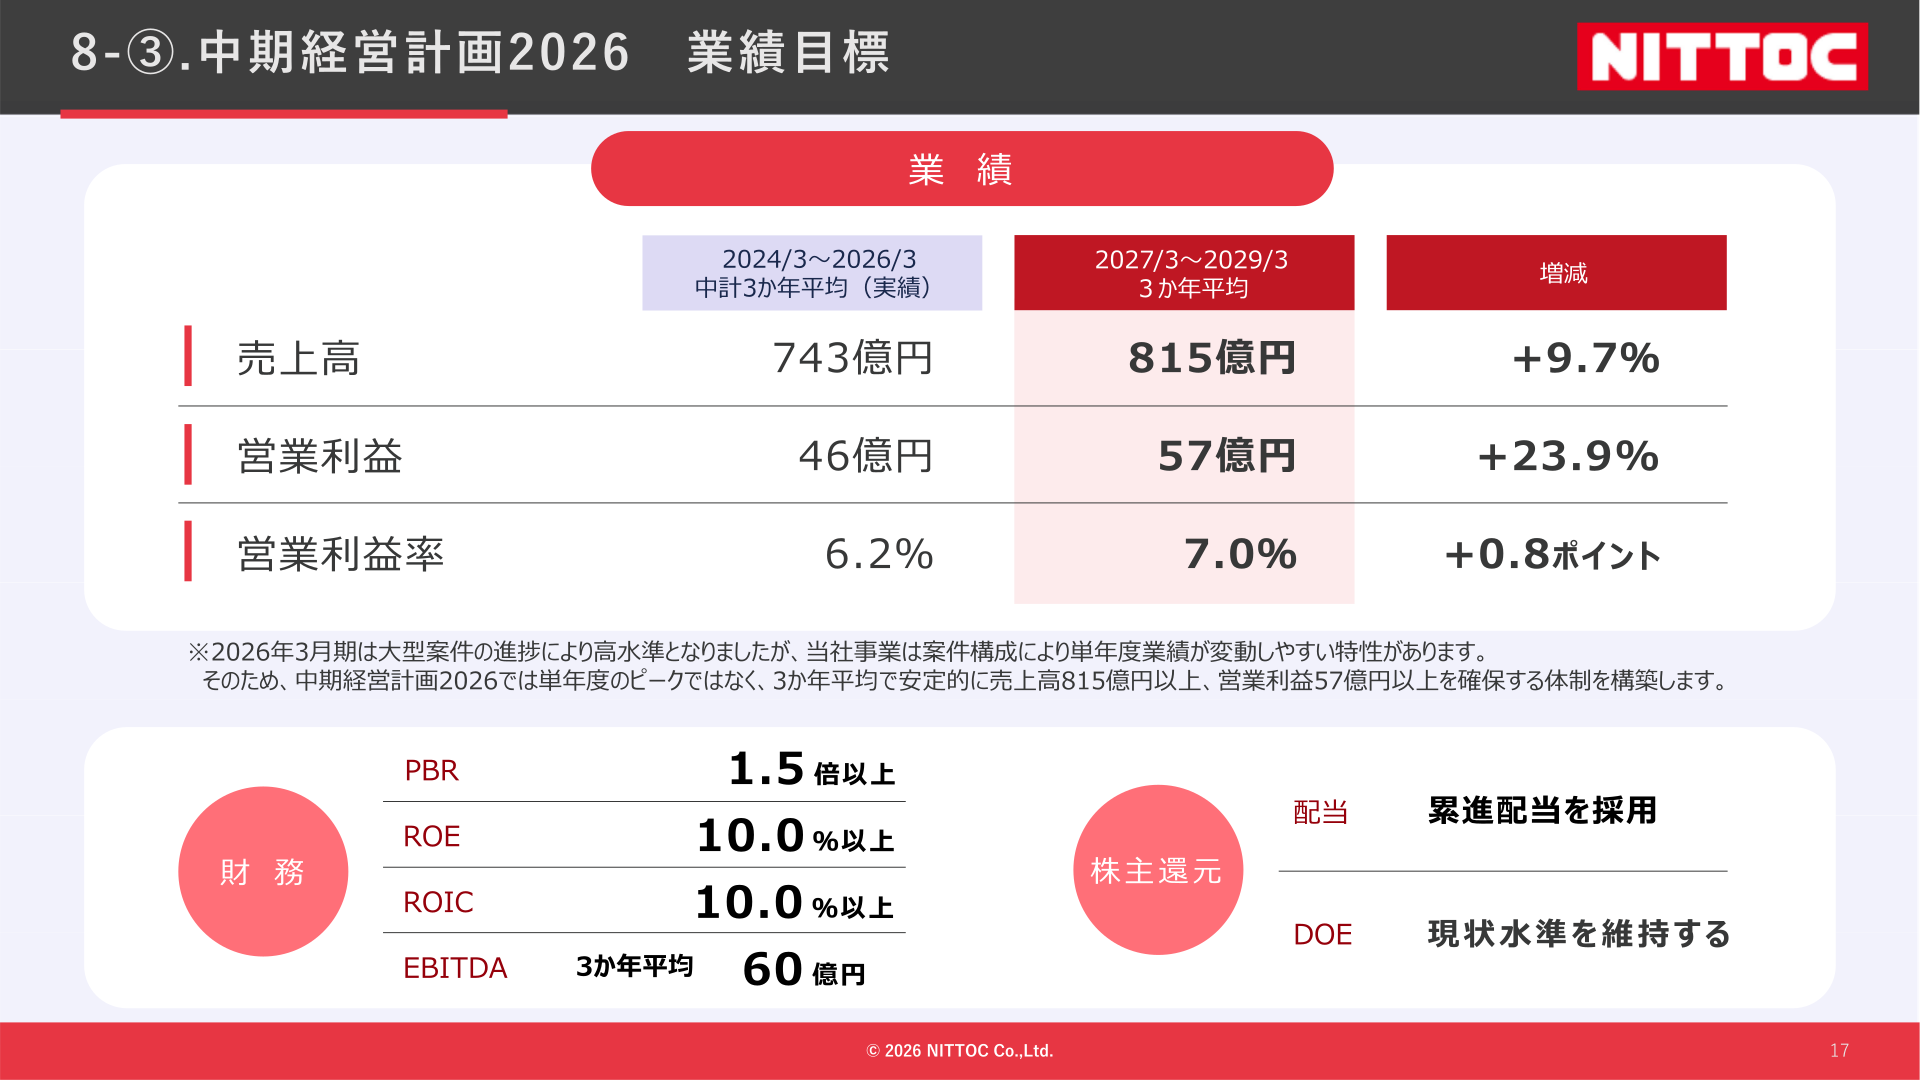
Medium-Term Management Plan 2026, which covers April 2026 through March 2029, adopts “establishing a structure that can stably generate earnings and continue to grow” as its basic policy and addresses a business strategy (establishing three core business pillars and exploring and developing new growth businesses and technologies), a management foundation strengthening strategy (securing and developing human resources), and a financial and investment strategy. Its main management indicators (three-year averages) are consolidated net sales of 81.5 billion yen or more, consolidated operating profit of 5.7 billion yen or more, ROE of 10.0% or more, and ROIC of 10.0% or more. The materials note that although the fiscal year ended March 31, 2026 reached a high level on the progress of large-scale projects, the company’s business has a characteristic tendency for single-year results to fluctuate with project mix, and that it will therefore build a structure that stably secures net sales of 81.5 billion yen or more and operating profit of 5.7 billion yen or more on a three-year average basis rather than at a single-year peak. In addition, to expand in the renewal field associated with the aging of social infrastructure, the company will change its work category classification from fiscal 2026, adding sewer pipeline repair and slope infrastructure repair to the seismic repair and reinforcement work for structures (bridges and tunnels) previously classified as “repair and reinforcement” to form a “Renewal” category. The fiscal 2026 order targets by work category under the new classification are 29,500 million yen for slope protection, 27,500 million yen for foundation and ground improvement, 17,000 million yen for renewal, and 7,000 million yen for other, totaling 81,000 million yen.
| Indicator | Three-year average actual (FY March 2024 to FY March 2026) | Medium-Term Management Plan 2026 target (three-year average, FY March 2027 to FY March 2029) | Change |
|---|---|---|---|
| Net sales | 74.3 billion yen | 81.5 billion yen | +9.7% |
| Operating profit | 4.6 billion yen | 5.7 billion yen | +23.9% |
| Operating profit margin | 6.2% | 7.0% | +0.8 points |
| ROE | – | 10.0% or more | – |
| ROIC | – | 10.0% or more | – |
| EBITDA | – | 6.0 billion yen (three-year average) | – |
| PBR | – | 1.5x or more | – |
Topics introduced include the conclusion of an “Agreement on Joint Research into a Sewer Pipeline Management System” by eight parties, comprising Saitama Prefecture, the Saitama Prefecture Sewerage Public Corporation and six private-sector operators including the company; slope disaster restoration work in Wajima City, Ishikawa Prefecture, which was damaged by the Noto Peninsula Earthquake; and ground improvement work on the No. 2 breakwater at Tottori Port. In research and development, “Hibi Navi AI,” an AI cloud application for mortar-sprayed slopes, was selected for listing in the Ministry of Land, Infrastructure, Transport and Tourism’s “Performance Catalog of Inspection Support Technologies,” and the company is developing “ChemiLogix,” a platform that connects work sites and offices via the cloud for chemical grouting methods.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















